

Where are seniors most likely to outlive their retirement savings — and why?
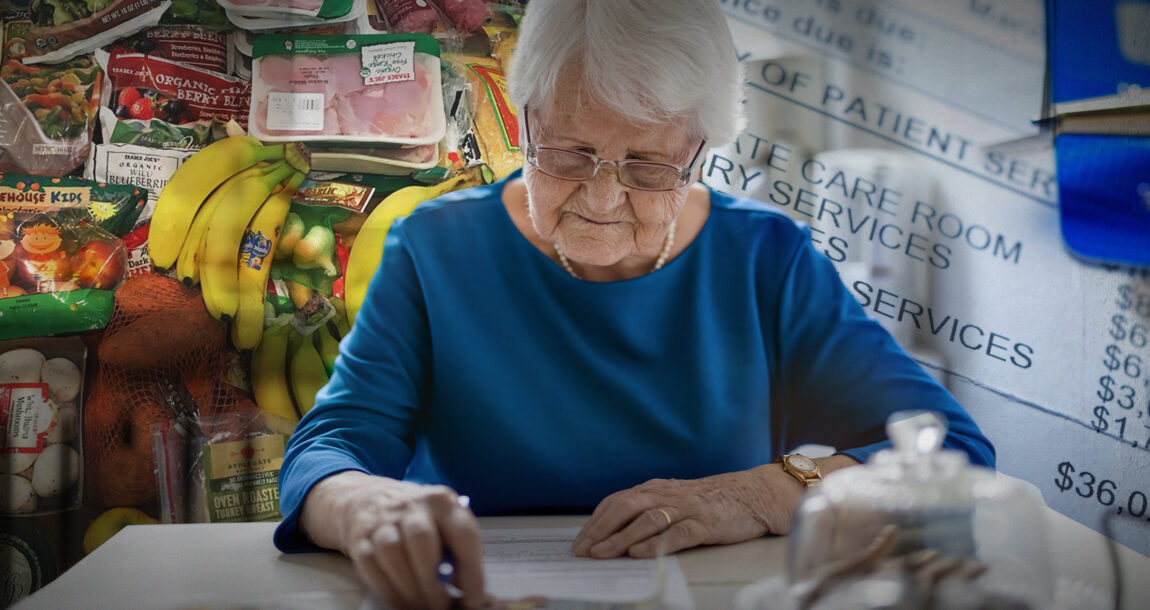
As American seniors contend with a retirement crisis that could see many fall below the poverty line, new research by Seniorly has identified New York, Hawaii, the District of Columbia, Alaska, and California as the top five states where seniors are most likely to outlive their savings.
But that's just the beginning of the story. According to the study, seniors in 41 states plus Washington, D.C. – most Americans – are at a greater risk of outliving their savings.
For many, this poses a difficult question that Joe Buhrmann, senior financial planning consultant at Fidelity’s eMoney Advisor, often puts to his clients: “What if you, tragically, live?”
“Many retirees plan for a short retirement period – perhaps only 20 years. In fact, the number of Americans over age 90 tripled between 1980 and 2010, and is projected to quadruple by 2050, according to census statistics. The likelihood, though, is that they could live much, much longer in retirement,” Buhrmann said.
In light of the new insights into state-level differences in this challenge, Buhrmann shared his advice for how financial professionals can help and what those in high-cost regions can do to prepare. This includes downsizing, strategically relocating, purchasing secure income products and maintaining an adequate emergency fund.
Glen Franklin, assistant VP of Research, Jackson National Life Distributors likewise suggested that seniors leverage financial options like a health savings account or annuities to stave off the worst outcomes.

Both professionals, however, urged American seniors to work with trusted advisors to lock in a retirement plan that can help manage the risk of outliving their savings.
“One of the best ways to mitigate this risk is to work with a trusted financial advisor and put together a plan that is customized to your unique situation and circumstances and can model any number of different scenarios,” Buhrmann said.
Most states face retirement crisis
According to Seniorly’s research, seniors in a whopping 41 states and D.C. risk outliving their savings — meaning a vast majority of Americans. Only in nine states are seniors projected to have a financial surplus.
The five states where seniors are least likely to outlive their savings include:
- Washington
- Utah
- Montana
- Colorado
- Iowa
Seniorly noted that states with higher life expectancy rates, such as Hawaii, will accordingly have a higher likelihood that seniors will outlive their savings.
However, the expected shortfall also varies, with a higher shortfall expected in more expensive states. Most American seniors are expected to have an average shortfall of $115,000 in retirement. But this figure balloons to over $400,000 in states like New York, Hawaii and D.C. due to “high expenses that exceed even strong incomes.”
Outliving savings: Longevity as liability
Advances in healthcare mean people are living longer than previous generations, but few plan for this reality. According to a Jackson study, 32% of Americans “underpredict their own estimated life expectancy,” increasing the likelihood that they could outlive their savings.
“A man that reaches age 65 has a 50-50 chance of living to age 86, a woman to age 89 and one of a couple to age 92 — 50%. There is a 1-in-4 chance, as a couple, that one of them will live to 97,” Buhrmann emphasized.
Although many Americans find the idea of early retirement “very attractive,” they often neglect to consider other factors retirees have to contend with, such as inflation, market risk, interest rate risk, and healthcare.
“Inflation can quickly eat away at retirement savings. Research has also shown that individuals tend to underestimate the impact of healthcare costs in retirement. Additionally, 70% of individuals turning 65 each year will likely need long-term care at some point, yet only 27% of individuals surveyed by Jackson believe they will need such care,” Franklin said.
Where do financial professionals come in?
While retirees face enormous risk, Buhrmann maintains that “the best way to avoid problems is to not get in them in the first place” by working with a financial professional to develop a sound strategy.
He said advisors can talk to clients about:
- Expenses: Determining which are essential, which are discretionary and which can be reduced or eliminated if resources are constrained
- Secure income products: Having payouts designed to provide income for the duration of life, such as social security, pension benefits, annuities and secure income sources
- Emergency funds: Keeping separate funds for everyday emergencies to avoid dipping into retirement accounts in the event of untimely withdrawals
Similarly, Franklin said advisors can encourage clients to think about market risk and portfolio diversification and health savings accounts.
By leveraging the right tools and strategy, both experts said retirees can use portfolio assets to cover discretionary expenses while keeping their retirement savings intact.
“It’s critical that financial professionals have conversations related to different retirement risk factors with their clients as soon as possible. Proactive, early planning and building a diversified retirement portfolio is essential to protect against risks that may threaten future financial security,” Franklin said.
“Not everyone gets to retire according to plan, though,” Buhrmann pointed out. “Oftentimes, as the result of layoffs, downsizings, or healthcare concerns, many retire earlier than they had planned. That’s why it’s important that your financial plan has some cushion built in and that you continuously monitor and review it with a trusted advisor.”
© Entire contents copyright 2025 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Systematize, automate and scale your Medicare practice
Swiss Re’s US CEO discusses excess mortality, long COVID and GLP-1 drugs
Advisor News
- The Gen Z money paradox
- NAIFA applauds final SECURE 2.0 regulations
- What will Democrats in Congress do about healthcare and retirement?
- Election results cloud retirement legislation outlook, experts say
- Planning for the missing chapter
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- Boomers want retirement protection, but their actions don’t match their mindset
- NAIC task force to address LTC riders
- ‘It’s really shocking:’ Regulators scrutinize assets backing annuity sellers
- Jackson Launches Direct-to-Consumer Annuity Offering
More Annuity NewsHealth/Employee Benefits News
- Reports Outline Managed Care Study Results from Harvard University (Inpatient-Only List Removals Shifted Procedures To The Outpatient Setting And Reduced Medicare Spending): Managed Care
- Health and Humor: Picking a Medicare insurance plan is daunting
- Obamacare is getting more expensive in Indiana
- Hays City Commission to consider bids for health insurance, sports complex improvements
- CHOICE arrangements: Not your father’s workplace health insurance
More Health/Employee Benefits NewsLife Insurance News
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- U-Haul Holding Company to Participate in Deutsche Bank Conference
- NAIC task force to address LTC riders
- Protective names Kurt Meyers Chief Legal Officer and Fernando Levy Chief Digital & AI Officer
- Best’s Commentary: Shanghai Cross-Border Investment Pilot Unlocks Overseas Growth Potential of China Non-Life Companies
More Life Insurance News