

Rising health care costs drive sharp increase in retirement anxiety
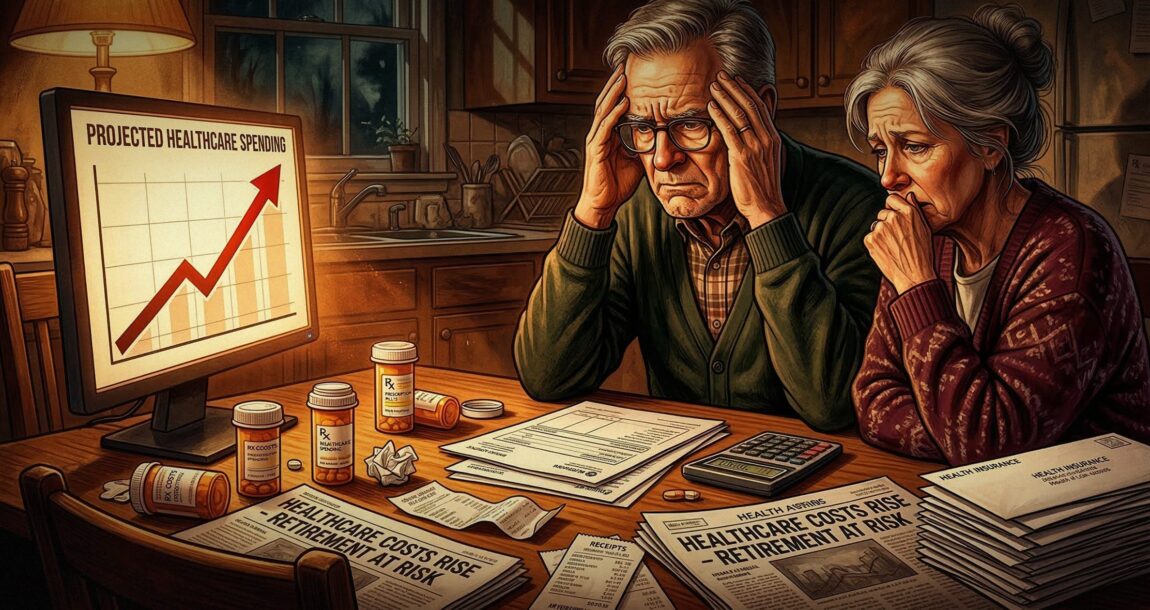
Persistent and rising health care costs, coupled with longer life expectancies, are driving a sharp rise in retirement anxiety, according to MetLife’s new 2026 Paycheck or Pot of Gold Study.
Among preretirees aged 50–75 who are within five years of retirement and are currently enrolled in an employer’s defined contribution plan, 58% worry about running out of money in their DC plan in retirement, MetLife said. And half (51%) of retirees who have money remaining from their DC plan share this concern, a dramatic escalation from 30%, less than a decade ago.
Reasons for the increase
Several forces are converging to drive a sharp increase in anxiety among pre‑retirees. MetLife’s 2026 Paycheck or Pot of Gold study shows that this concern is well‑founded, according to Roberta Rafaloff, vice president and head of institutional income annuities at MetLife. First, she said, people are living longer while facing persistently higher costs of living — especially health care - which means retirement savings must last far longer than many initially planned. “Yet,” she pointed out, “preretirees now expect their savings to last only about 15 years on average, despite the reality that many will spend 20 to 30 years in retirement.”
Second, Rafaloff said, market volatility has made retirement outcomes feel far less predictable. “Even diligent savers worry that external factors beyond their control could derail their plans. That uncertainty is reflected in the data: 58% of pre‑retirees say they are concerned their retirement savings will run out, up from 49% in 2022,” she added.
Finally, many preretirees recognize that the shift from traditional pensions to defined contribution plans has placed the burden of turning savings into income squarely on their shoulders. “Without clear guidance or a dependable income strategy, that responsibility can feel overwhelming,” Rafaloff said. “Together, these pressures are reshaping how people think about retirement and increasing demand for solutions that offer clarity, simplicity and confidence.”
Lump-sum recipients face the greatest financial strain
The survey also pointed out that retirees who chose to withdraw a significant sum directly from their retirement savings face the greatest financial strain, exhausting their savings faster than ever.

And why do lump-sum recipients face so much financial strain? “This is because lump sums often lack the guarantees needed to support long‑term income needs,” explained Rafaloff. “Retirees who take a lump sum are depleting those savings in just 4½ years on average, even though many will spend decades in retirement.
“Without a predictable monthly “paycheck,” retirees are forced to make ongoing spending and investment decisions in an environment shaped by inflation, market swings and unexpected expenses. This can lead to overspending early in retirement, or underspending out of fear, both of which erode financial well‑being,” Rafaloff said.
The consequences are clear, she added. “Half (51%) of retirees who completely depleted their lump sums report financial hardship, and nearly all who have nothing left of their lump sum and experienced a financial hardship (98%) say an additional layer of retirement income could have prevented it.”
By contrast, retirees receiving annuity income report significantly higher satisfaction, including financial security (94%) and peace of mind (92%), according to Rafaloff. “The findings underscore that it’s not simply how much someone saves, but how those savings are converted into income that ultimately determines successful retirement outcomes,” she added.
Reducing the risk of spending retirement savings too quickly
What are some of the steps that financial professionals can take to help their clients reduce the risk of spending their retirement savings too quickly? Financial professionals can play a critical role in helping plan participants navigate the decumulation phase, and the study points to several effective approaches, said Rafaloff. First, reframing retirement decisions as income decisions rather than asset decisions is essential. “When balances are translated into monthly income, participants better understand tradeoffs and are more likely to value predictability and sustainability,” she said.
Second, encouraging partial annuitization can meaningfully reduce risk, Rafaloff added. The research shows that 91% of preretirees prefer a combination of guaranteed income and liquidity, reflecting a desire to cover essential expenses with a reliable income stream while keeping some assets accessible. This approach helps create a stable foundation without sacrificing flexibility, she said.
“Finally,” Rafaloff said, “education and simplicity matter. Participants are more confident when solutions are easy to understand. By emphasizing guaranteed income, longevity protection, and clear budgeting frameworks, financial professionals can help participants avoid rapid depletion and support better long‑term outcomes.”
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Why experts are calling this the ‘golden age’ of underwriting
PHL Variable liquidation: Regulators, investors pivot legal fire to Nassau
Annuity News
- MassMutual Expands Lending Options With New Secured Credit Line
- Corebridge Financial Introduces Progressive Trigger, a First-of-Its-Kind Index Annuity Strategy Designed to Turn Missed Years into Future Opportunity
- Insurer proposes $1.1M deal to resolve CA teachers’ annuity fee lawsuit
- IMOs get frustrated with slow carrier adoption of faster technology
- New class-action lawsuit targets Delaware Life over annuity disclosures
More Annuity NewsHealth/Employee Benefits News
- Answering questions on Medicare open enrollment
Terry Savage: Your questions answered on Medicare open enrollment
- Make sure your Medicare coverage makes sense
Jill On Money: Medicare on my mind
- RESURFACED AUDIO: MIKE ROGERS SAYS HE WANTS TO KICK SICK PATIENTS OFF HEALTHCARE, SUPPORTS NEW COPAYS – MICHIGAN DEMOCRATIC PARTY
- It's 5 a.m. at a Princeton Fitness Center – What Do You Say to the Early Arrivals?
- Your questions answered on Medicare open enrollment
More Health/Employee Benefits NewsLife Insurance News
Property and Casualty News
- DCI urges Missourians to weigh earthquake coverage as premiums rise in high-risk areas
- Goodwin giving Patrick a race for lieutenant governor
Outspent and unknown, Democrat Vikki Goodwin gives Lt. Gov. Dan Patrick his toughest race yet
- Golf cart fire sparks lawsuit
- The credit score your insurer uses isn't your FICO
- Moody’s: Hurricane Isaias to cost insurers an estimated $3.5 billion
More Property and Casualty News