

Could COVID-19 Lead To Higher Life Insurance Sales?
The effect of the COVID-19 pandemic on Americans is immeasurable. Our health and well-being concerns became all-consuming over the course of the last 18 or more months. As vaccines are now widely available and many people have begun to venture out in public, financial advisors and life insurance agents have begun face-to-face meetings with their clients again.
But what about gaining new business? What has the pandemic done in terms of life insurance awareness and purchase intent? LIMRA and Life Happens fielded their 11th annual Insurance Barometer study in January during the height of the “second wave” of the pandemic in much of the U.S.
Historically, the majority of Americans have preferred to purchase life insurance in person with an agent or advisor. As use of technology has become nearly ubiquitous and people have grown accustomed to conducting meetings and transactions online, this trend has shifted. In 2011, 64% of consumers said they preferred to buy in person; by 2020, just 41% felt this way. It is not surprising that the preference for online purchasing nearly doubled from 17% in 2011 to 29% in 2020.
During the pandemic, more Americans of all ages became accustomed to transacting online. Life insurance and other similar products can be confusing for prospective clients, and face-to-face is still the most preferred method of finalizing such purchases. It is clear, however, that the industry must adapt to the changing channel and distribution landscape.
Life events such as births, marriages, job changes and deaths of family and friends prompt people to consider purchasing life insurance. The COVID-19 pandemic is a life event that all of us have experienced at the same time, over an extended period. The pandemic lifted the likelihood of buying life insurance for many consumers; almost one in three (31%) said they were more likely to buy because of the pandemic.
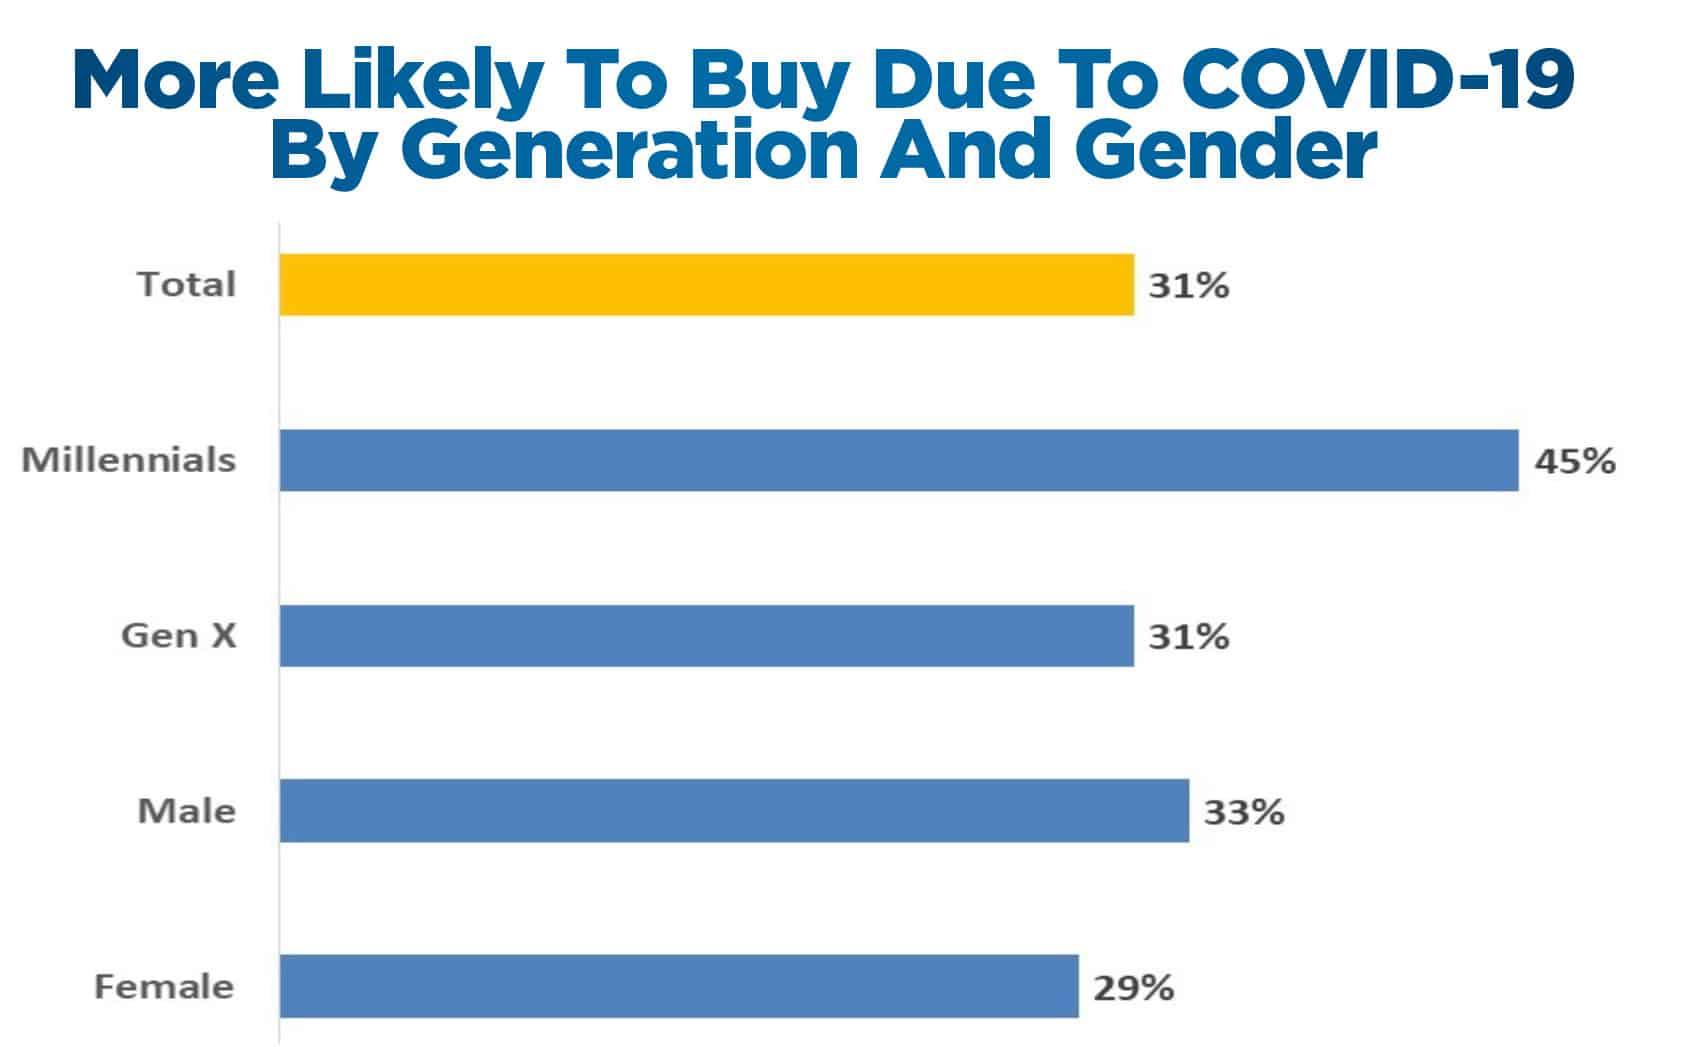
Two-thirds of those surveyed said they personally knew someone who had tested positive for COVID-19. Of those individuals, the likelihood of obtaining life insurance in 2021, at 33%, was nearly the same as it was for the entire respondent pool. For those who tested positive themselves, that number rose to 42%. This shows that it is often personal experience — whether starting a family or battling a dangerous virus — that drives life insurance sales.

Of course, purchase intent does not equate to sales. Even the most well-intentioned consumer may have some perceptions about life insurance and the industry that put roadblocks in their way.
More than half of the survey’s respondents (53%) admit they are unsure what product they would need or how much coverage to purchase. Nearly half (45%) stated that they have simply put off purchasing, and more than a third (36%) believe they would not qualify for coverage.
These are significant obstacles for the industry and indicate the need for compelling communications to help consumers build appreciation for the broad value proposition that life insurance offers.
According to the 2021 Insurance Barometer, slightly more than half (52%) of American adults own some form of life insurance coverage (e.g., individual, employer sponsored), which is a decline of two points from 2020. This marks the lowest level of self-reported ownership to date in the 11 years of this study. Perhaps with online purchasing increasing before the pandemic and so many more people now comfortable conducting business and transactions online, the life insurance industry could be looking at higher sales as it navigates this post-pandemic world.


Advisors Are Helping Clients Grow Greener
The Five W’s Of Creating A Memorable Family Reunion
Advisor News
- The 6X Formula for leveraging content marketing with AI
- When a home becomes difficult to insure, the plan changes
- The inheritance gap: Helping clients plan for money that hasn’t arrived
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
More Advisor NewsAnnuity News
- DOL, trade groups, state AGs file briefs supporting Alcoa in PRT lawsuit
- John Hancock launches new fixed indexed annuity suite
- Annuities to play a larger role in workplace retirement plans
- FHLBank Pittsburgh Announces Results in 2026 Board Election
- Regulators advance shorter, streamlined annuity buyers guide
More Annuity NewsHealth/Employee Benefits News
- Oscar Health Inc. (NYSE: OSCR) Draws the Stock Spotlight on Nov. 12
- Duet Raises $15M to Scale Nurse Practitioner-Owned Clinics, Filling Critical Primary Care Gap
- Sidecar Health Named a Finalist in the 2026 Fierce Innovation Awards
- Open enrollment set to begin Nov. 1
- OPINION: Imperial County’s dental care gap goes beyond insurance coverage
More Health/Employee Benefits NewsLife Insurance News
- Three lawsuits put life insurers’ cost-of-insurance practices under scrutiny
- Military Briefs: November 12-18
- Security Benefit Series B Preferred Stock Dividend Rate Resets to 10.286%
- FHLBank Pittsburgh Announces Results in 2026 Board Election
- New Jackson Study Finds the "Sandwich Generation" Squeeze Comes from More Than Two Sides and It’s Quietly Draining Retirement Savings
More Life Insurance News