

Annuity income: The new 401(k) standard?
TAMPA, Fla. -- The push to include annuity products in 401(k) plans resembles the early evolution of participant-directed investing, said Kent Peterson of Securian Financial Group.
That is, promising, but still in its formative stages.
Speaking on a LIMRA Life Insurance and Annuity Conference panel about retirement innovation, Peterson traced the industry’s transformation back to 1990. In those days, most workplace retirement plans were employer-directed and updated only quarterly.
“A lot of times, you didn't know what your balance was until the end of the quarter," he said. "It was an interesting time."
The shift in the 1990s toward daily valuation and participant control marked what he described as the “first generation” of recordkeeping. Today’s emerging guaranteed income products, usually annuities, are at a similar early stage, with significant barriers to adoption.
Among the biggest challenges: complexity, lack of transparency and limited understanding among fiduciaries responsible for overseeing retirement plans.

Advisors and plan sponsors repeatedly cite complexity as a key obstacle, panelists said, noting that many struggle to evaluate insurance-backed products or explain them to clients.
“They say it takes three times to explain it to me. As a financial advisor, how am I going to explain it to the plan sponsor?” said Peterson, senior vice president, institutional retirement at Securian.
Successful products will need to meet several criteria to gain wider acceptance. They must be transparent, portable between employers, and “modular” — meaning they can be separated from underlying investments if those investments are replaced.
That flexibility is critical in a heavily regulated environment governed by fiduciary standards under the Employee Retirement Income Security Act.
“There’s fiduciary friction when you put a product into a lineup that can’t be fired,” Peterson said.
New rules could help
The Department of Labor recently issued guidance aimed at clarifying how fiduciaries can evaluate such products, including the use of benchmarks and process-based standards. Panelists said the guidance could push providers to improve product design, though some expect further revisions.
Despite the challenges, industry data suggests momentum is building.
Assets in guaranteed income solutions within defined contribution plans now total in the billions, a small share of the roughly $14 trillion 401(k) market but a sign of growing favor.
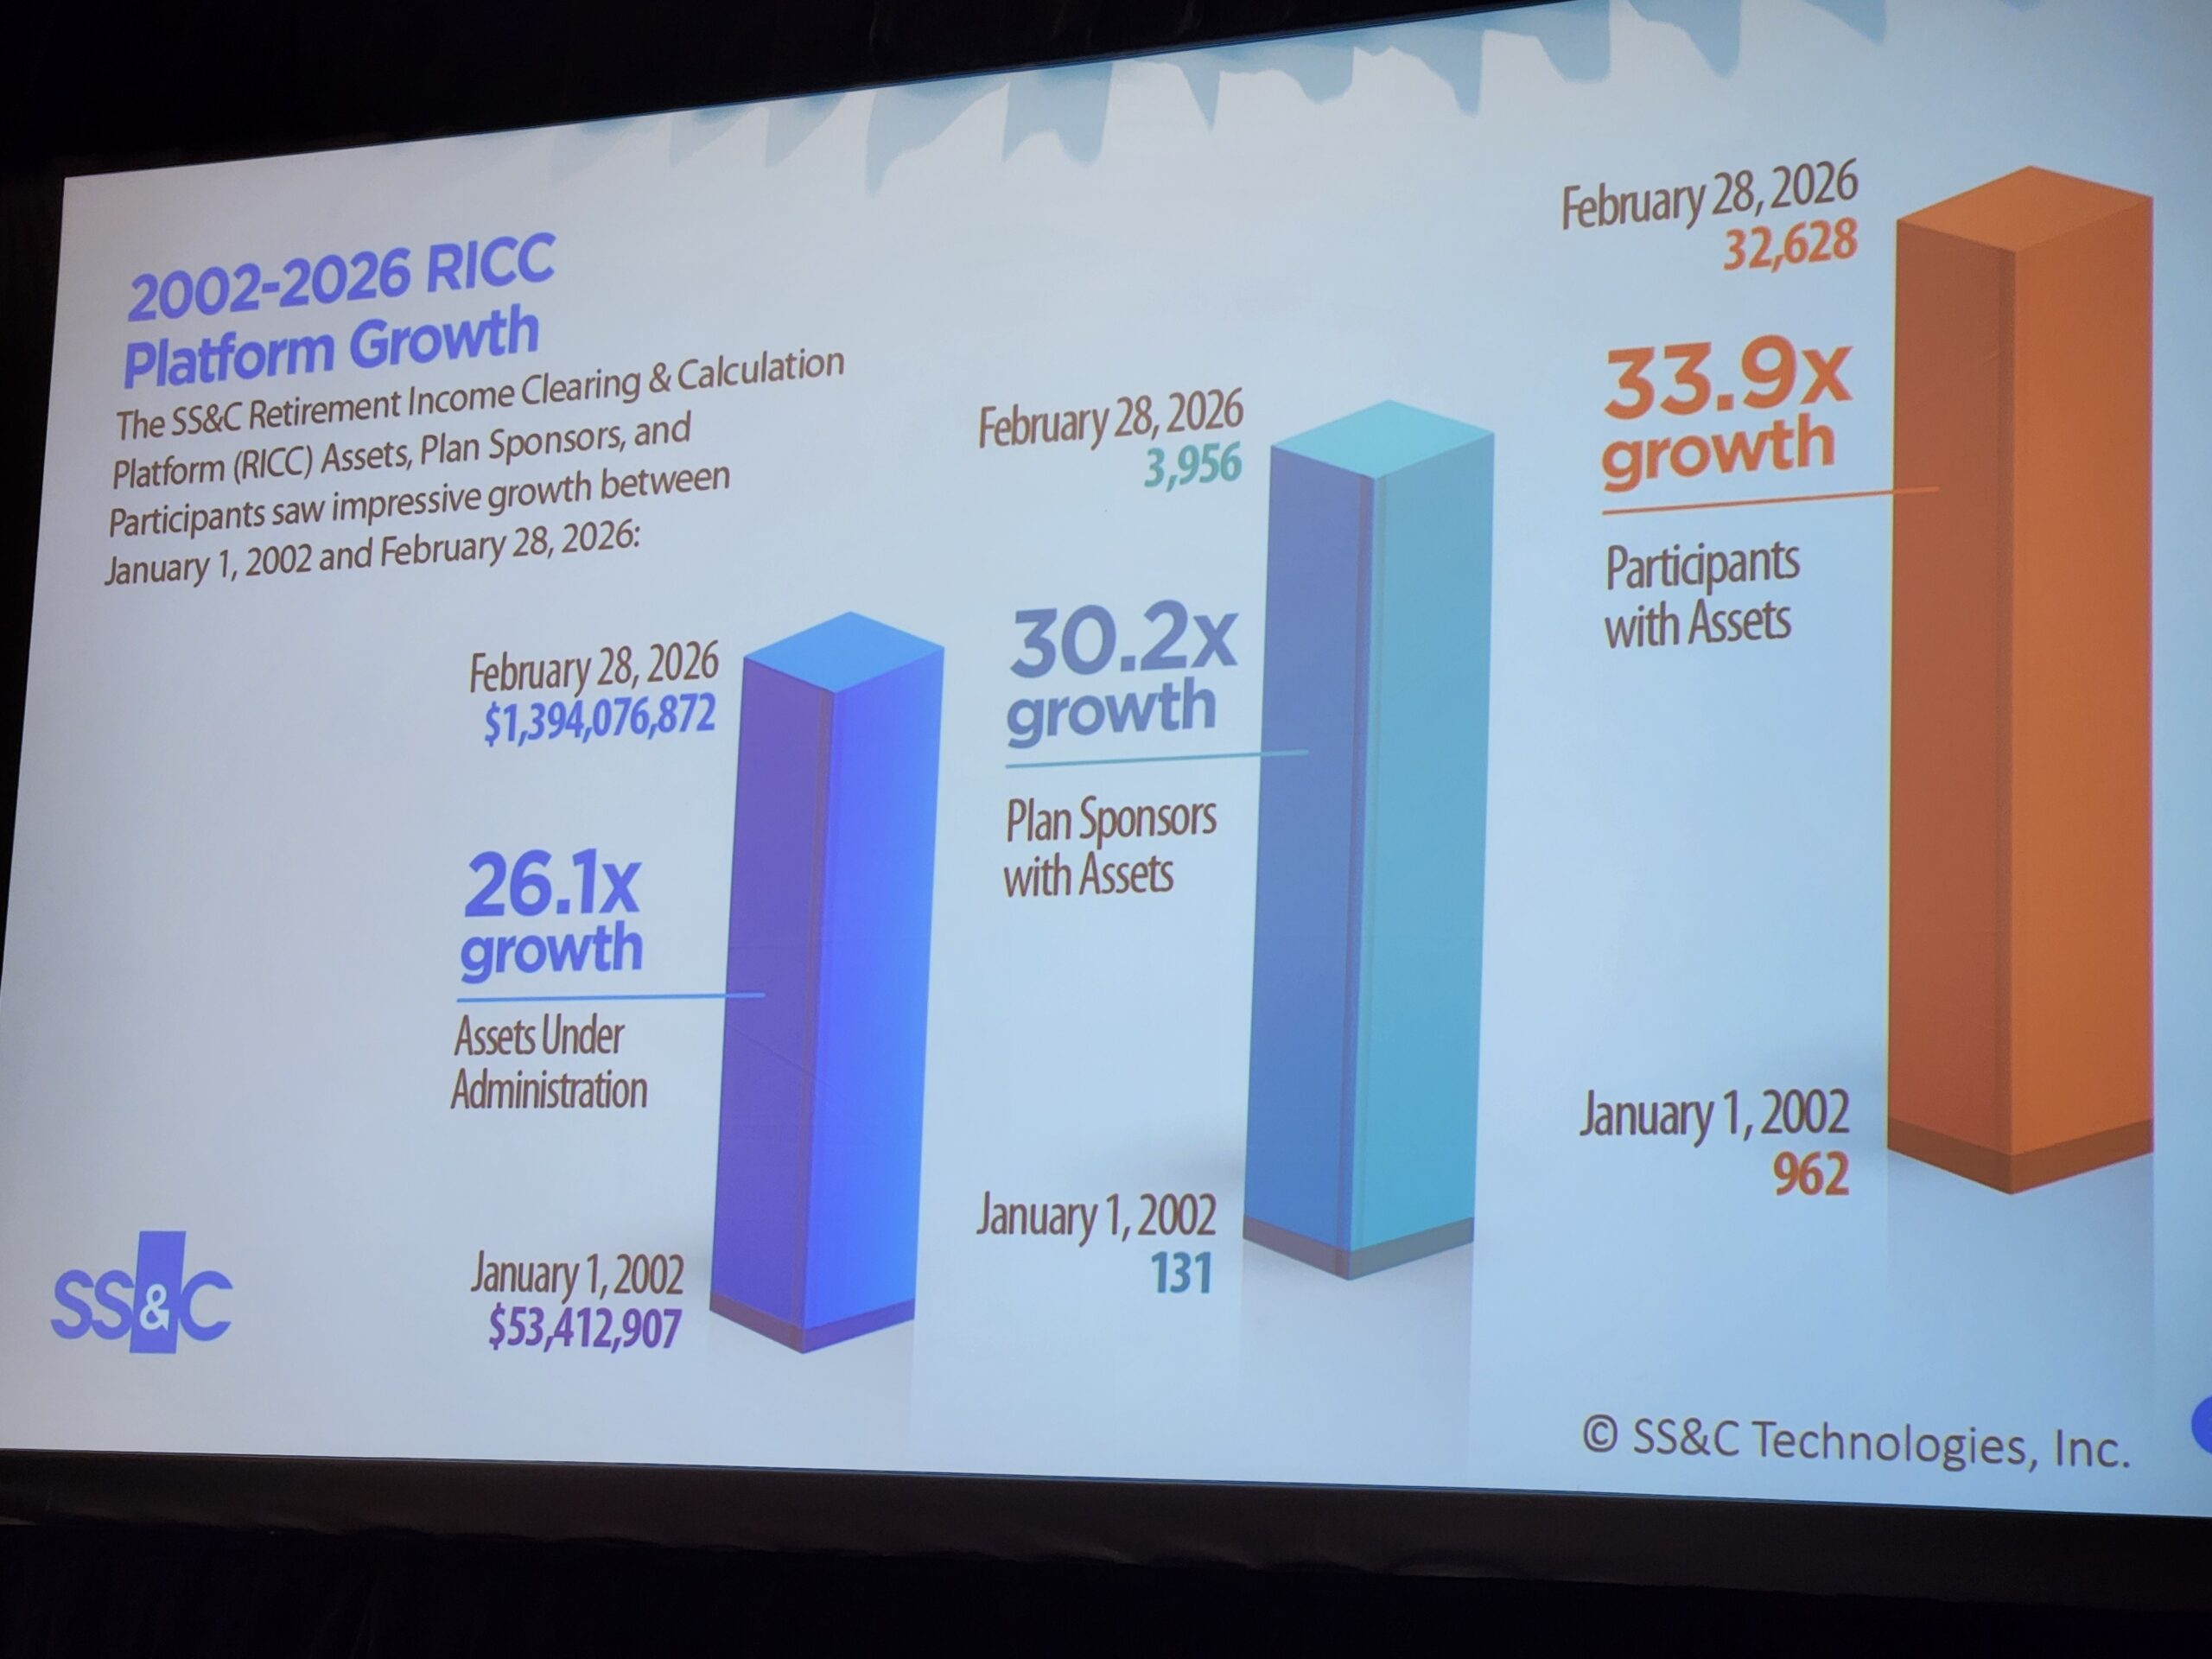
“I think there's still a misperception in the marketplace that this is kind of conceptual, that it hasn't happened yet, that participants aren't actively in these products, plans aren't using it," said Ryan Grosdidier, business development lead for retirement income solutions at SS&C Retirement Solutions. "That's not the case."
Grosdidier shared a slide on the growth SS&C experienced:
Panelists pointed to the passage of the SECURE Act as a turning point, spurring product development and easing some regulatory concerns about offering annuities in workplace plans.
They also highlighted increasing involvement from major asset managers, including Vanguard, as a signal that the market is maturing.
Still, barriers remain — particularly for smaller insurance companies seeking to enter the space. These include technological integration with recordkeeping platforms, distribution challenges and the need to compete with larger, established providers.
For now, speakers agreed, trust will be the deciding factor.
“You have to build trust with the plan sponsors," Peterson said. "You have to build trust with the plan advisors. And then, as you move up this chain, through adoption and retention, there will be great growth in the industry."
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Architecture plays a role in mitigating climate risk
OBBBA can give small-business clients opportunities for saving
Advisor News
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
- How advisors can help frugal retirees finally enjoy their savings
- Wealth planning vs. estate planning: Honoring your client’s wishes
- What to discuss during the first retirement planning meeting
- Inflation, competing priorities and uncertainty erode retirement security
More Advisor NewsAnnuity News
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
- National Life Group expands annuity portfolio
- AM Best to Join Life/Annuity Insurance-Focused Panel Discussion at Capitol Forum Event
- USAA Earns No. 1 Ranking in JD Power Individual Annuity Study for the Third Consecutive Year
More Annuity NewsHealth/Employee Benefits News
- My unhappy day in small claims court | Letters to The Republican
- Enrollment is open for Affordable Care Act coverage. What do New Mexicans need to know?
- A Smarter Approach to Employee Health Insurance Costs
- Are GLP-1s Good for Business? The Jury Says …
- Closing gaps in group disability coverage
More Health/Employee Benefits NewsLife Insurance News
- Unum Group Reports Third Quarter 2026 Results
- First American Financial Corporation Appoints Darryl D. Button to Board of Directors
- Corebridge Financial Announces Third Quarter 2026 Results
- MassMutual announces record $3.3 billion policyowner dividend for 2027
- Protective Completes Acquisition of Obsidian, Establishing Specialty Property and Casualty Business Line
More Life Insurance News