

Pacific Life’s Bold Underwriting Innovation Raises the Bar for Life Insurers
In the life insurance business, every underwriting decision is a promise. It’s a commitment that one day, often decades in the future, a family or business will receive the benefit they were counting on. Few understand that responsibility better than Susan Ghalili, Chief Underwriter at Pacific Life, who has spent more than four decades shaping how the industry evaluates, prices, and delivers life insurance.
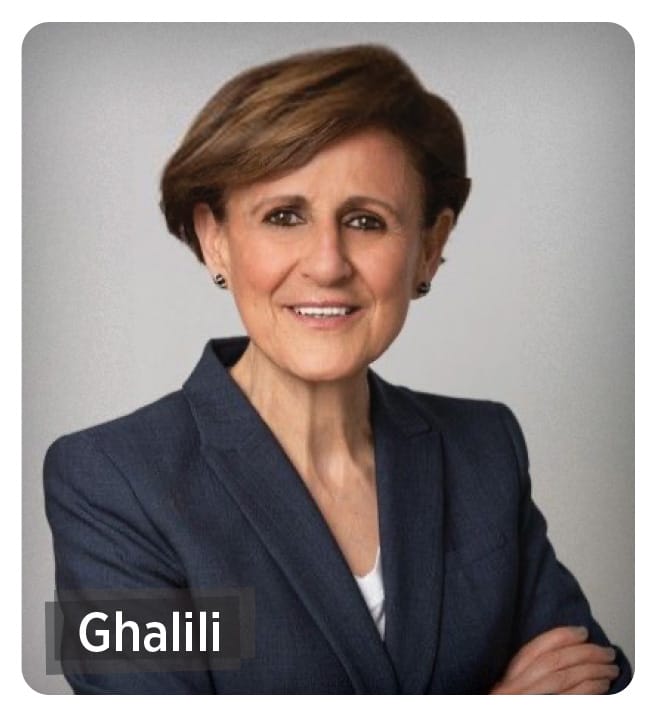 “Every time an underwriter makes a decision to accept a case, they are making a commitment on behalf of the company to deliver on that promise in the future,” Ghalili said. “That’s why underwriting is not just a back-office function. It’s at the very heart of what we do.”
For Pacific Life, underwriting has become a critical differentiator for financial professionals and their clients. By rethinking processes, investing in expertise, and strengthening relationships with financial professionals and reinsurers, the company has positioned itself as a leader in risk assessment at a time when the business of life insurance is evolving rapidly.
Underwriting as a Market Differentiator
In many industries, customer loyalty comes down to brand perception or price. In life insurance, underwriting often determines where the business goes.
“Underwriting is truly the key differentiator and decider of where our clients and financial professionals decide to place business” Ghalili explained. “It’s not just about pricing the risk. It’s about how accessible, transparent, and capable we are in handling complex cases.”
That’s especially relevant in the large-case market, where coverage can exceed $50 million or even $100 million. To serve that segment, carriers must not only have the underwriting expertise to evaluate complex medical and financial profiles but also the capacity to place such large amounts of coverage.
This year, Pacific Life became the first U.S. carrier in decades to expand its individual capacity—the maximum amount of coverage we are able to offer on a single life. Working in partnership with reinsurers, Pacific Life raised its auto capacity from $65 million to $75 million, breaking through a ceiling that had stood for nearly 30 years.
“That announcement was significant because it made us the destination company for financial professionals working with family offices and ultra-affluent individuals,” Ghalili said. “We know others will follow, and that’s a good thing. When one company leads, it helps move the entire industry forward.”
Expertise, Transparency, and Access
At the core of Pacific Life’s approach is the human element: highly experienced underwriters who not only understand complex cases but also remain accessible to financial professionals.
“Access to the underwriter is a key differentiator for us,” Ghalili said. “Financial professionals want a conversation if they don’t understand a decision. They want options and strategies. We’re not hidden behind closed doors.”
That philosophy is built on both technical expertise and client service. Pacific Life underwriters regularly review sophisticated medical records and financial statements, and they work closely with reinsurers to ensure that pricing and risk sharing are aligned. At the same time, they provide transparency to financial professionals without compromising confidentiality, giving them the tools to explain outcomes to their clients.
“Ease of doing business is critical,” Ghalili said. “It’s not just about the decision we make but about how clear and efficient the process is.”
Innovation in Practice
Pacific Life’s underwriting innovations aren’t just about efficiency—they’re about creating a better experience for financial professionals and their clients.
By taking a “concierge” approach to underwriting, clients no longer face the frustration of duplicative medical exams. Instead, Pacific Life, with client authorization, leverages records from the client’s existing physicians. For financial professionals, that means fewer barriers to closing large, complex cases and a smoother path to coverage. For clients, it preserves the premium, white glove experience they expect.
“Concierge underwriting allows us to honor the client’s time and the relationship the financial professional has built,” Ghalili said. “It’s about making the process feel seamless while maintaining the rigor underwriting requires.”
Pacific Life’s Automated Underwriting has also been a game changer. By using self-reported histories and electronic databases, applicants can secure up to $3 million in coverage without invasive exams. “We’ve seen a success rate of more than 40% among eligible clients,” Ghalili said. “It’s about making life insurance more accessible while maintaining discipline around risk.”
Pacific Life has also expanded underwriting guidelines for foreign nationals, offering coverage to individuals with financial and physical ties to the U.S. This progressive approach, developed in consultation with reinsurers and compliance teams, has expanded Pacific Life’s competitive edge in this growing market while setting an example for peers.
The Role of Reinsurers
Reinsurers play a pivotal role in underwriting capacity and credibility. Carriers rely on them to share risk, but reinsurers must trust the carrier’s underwriting discipline.
“In order for reinsurers to agree to take part of the risk, they have to have confidence in our practices and standards,” Ghalili said. That credibility enabled Pacific Life to secure reinsurer support for the industry-changing increase in auto capacity and jumbo limits. “What’s good for us is good for the reinsurers. What’s bad for us is bad for them,” Ghalili explained. “We’re in it together.”
A Holistic View of Risk
Pacific Life has also taken a holistic approach through its Pacific Healthy Rewards program, which considers not just medical conditions but how clients manage them. For example, two individuals may have diabetes, but one who follows treatment and maintains a healthy lifestyle may receive better pricing.
“It’s about looking at the risk holistically rather than just checking boxes,” Ghalili said. “Healthy practices matter, and we want to reflect that in our underwriting.”
Unlike other carriers experimenting with wellness incentives, Pacific Life has extended Healthy Rewards across its full product portfolio.
Supporting Financial Professionals
Ultimately, underwriting succeeds when financial professionals can confidently guide their clients. That requires ongoing education and communication.
“We want to make sure financial professionals fully understand our practices, requirements, and processes so they can deliver the best outcomes,” Ghalili said.
Pacific Life wholesalers, who maintain close relationships with financial professionals, play a central role in that effort. They serve as quarterbacks, bridging communication between financial professionals and underwriters to ensure cases move smoothly. “No organization can be successful just by having strong underwriting,” Ghalili said. “It takes strong distribution, strong products, and strong underwriting working together.”
Always Moving Forward
Differentiation in underwriting, Ghalili notes, is never permanent. Competitors catch up, and clients’ expectations continue to rise.
“In any market, your differentiation is short-lived,” she said. “You have to continuously move forward.” For Pacific Life, that means pushing the boundaries of underwriting capacity, simplifying processes, and finding new ways to balance risk with client experience. Underwriting may be invisible to most policyholders, but as Ghalili makes clear, it is where promises are made and trust is built.
“It’s always about striking that balance—pricing the risk appropriately while making it easier for people to get access to life insurance,” Ghalili said. “That’s what makes underwriting such a powerful differentiator.”
See How We Can Help
For more information, financial professionals are invited to click here.


How Bestow Helped a Top-10 Carrier Grow Final Expense Sales 200% Year-Over-Year
Leading the Way: Simplicity’s Playbook for Success
Advisor News
- The Gen Z money paradox
- NAIFA applauds final SECURE 2.0 regulations
- What will Democrats in Congress do about healthcare and retirement?
- Election results cloud retirement legislation outlook, experts say
- Planning for the missing chapter
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- Boomers want retirement protection, but their actions don’t match their mindset
- NAIC task force to address LTC riders
- ‘It’s really shocking:’ Regulators scrutinize assets backing annuity sellers
- Jackson Launches Direct-to-Consumer Annuity Offering
More Annuity NewsHealth/Employee Benefits News
- Reports Outline Managed Care Study Results from Harvard University (Inpatient-Only List Removals Shifted Procedures To The Outpatient Setting And Reduced Medicare Spending): Managed Care
- Health and Humor: Picking a Medicare insurance plan is daunting
- Obamacare is getting more expensive in Indiana
- Hays City Commission to consider bids for health insurance, sports complex improvements
- CHOICE arrangements: Not your father’s workplace health insurance
More Health/Employee Benefits NewsLife Insurance News
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- U-Haul Holding Company to Participate in Deutsche Bank Conference
- NAIC task force to address LTC riders
- Protective names Kurt Meyers Chief Legal Officer and Fernando Levy Chief Digital & AI Officer
- Best’s Commentary: Shanghai Cross-Border Investment Pilot Unlocks Overseas Growth Potential of China Non-Life Companies
More Life Insurance News