

Training consumers to make confident financial decisions
Annuities, guarantees, term life, surrender charges, health supplemental plans, voluntary benefits, critical illness, Roth 401(k), target date funds, living benefits, riders — and the list goes on. The financial services lexicon is complex and continues to grow. Things get further complicated when you bring up major financial themes such as savings, budgets, insurance coverage needs, debt, taxes and personal longevity. It’s hard for anyone to have the skills to make confident financial decisions.
Although the COVID-19 pandemic has increased awareness of life insurance and health, knowledge on financial topics is still abysmal. According to the TIAA Institute-GFLEC Personal Finance Index survey, U.S. adults could correctly answer only about half of the financial literacy questions. Eighteen percent correctly answered more than 75% of the index questions, while 23% correctly answered 25% or fewer of the questions. As bad as these results were, the grades were even worse for Generation X and millennial respondents.
In fact, data from the FINRA Investor Education Foundation’s National Financial Capability Study shows a strong correlation between respondents with higher financial literacy (scoring above the median on a seven-question financial literacy quiz) and those who feel financially secure. That finding is exacerbated when, according to LIMRA’s 2022 Insurance Barometer Study, 2 in 5 parents say they are barely or not at all financially secure.
The strength coach analogy
As a 46-year-old coming out of the pandemic, I made my physical fitness a priority. Although I can’t control every aspect of my health, I do want to increase my odds of having a long and active retirement. If I weren’t staying active, it would become harder and harder to exercise and more likely that I would have health issues later in life. I stay active by running every other day, and I use fitness apps that provide on-demand coaching, gamification and ways to track my performance. While I’m using technology to support my fitness, many of my friends use personal trainers and strength coaches. Improving your physical fitness doesn’t have to be a one-size-fits-all approach.
The same logic can apply to finances. By investing time and effort in reading books, listening to podcasts, or using budget tools and programs, some might be able to build financial literacy on their own. Others will need a financial professional, friend, coach, trainer or advisor to increase their financial knowledge, ultimately leading to financial success.

From inertia to action
Why don’t more individuals invest time and effort in improving their financial acumen? Research shows that time, topic discomfort and being overwhelmed are three of the key areas of inertia. So what can you do? Here are three things to consider.
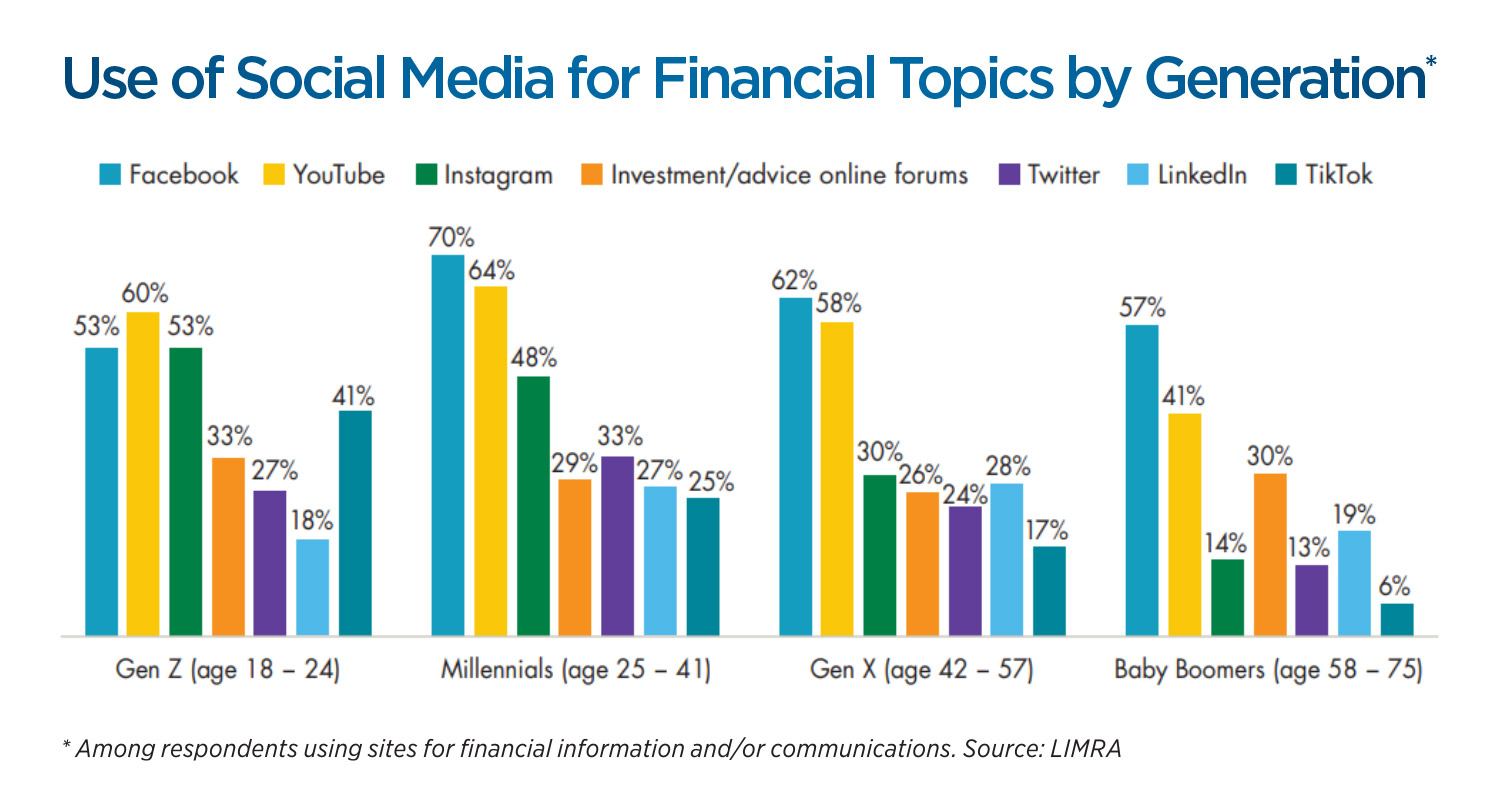
1. Have a social media presence. In LIMRA’s 2022 Insurance Barometer Study, the respondents indicating the use of social media sites for financial purposes more than doubled in the past three years, to 53%. Your online presence should not be about pushing product. Connect the dots for your clients.
2. Be human. Bring expertise and empathy to topics like end-of-life, adult care and holistic advice. According to LIMRA’s 2022 Insurance Barometer Study, 40% of respondents felt discomfort during end-of-life discussions. Advisors and agents can build trust with clients by starting with basic topics like emergency savings, budgeting and longevity.
3. Connect at a deeper level. People love stories. They want to feel emotions. Storytelling is powerful because it can create an emotional connection between you, your personal brand and the client. You can share 1,000 facts with a client with little success, but a powerful story will have a greater chance of moving a client closer to action.


Annuities: Gaps can lead to opportunities
Leaning into technology and change
Advisor News
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- New Congress must address drug affordability
- AM Best Upgrades Issuer Credit and National Scale Ratings of Auna Seguros, S.A.
- MAKE AMERICA HEALTHY AGAIN MEETS PUBLIC CHOICE
- Genworth reports loss of $41M in CEO Tom McInerney’s final earnings
- Kansas Silver Haired Legislature renews call for Medicaid expansion
More Health/Employee Benefits NewsLife Insurance News
- National Life Group Approves $23 Million Dividends for 2027
- Milliman’s proposed $15.5 million settlement puts life insurance underwriting data in focus
- Brighthouse Financial Announces Third Quarter 2026 Results
- Prudential earnings dip as Japan sales suspension offsets U.S. growth
- U-Haul Holding Company Reports Second Quarter Fiscal 2027 Financial Results
More Life Insurance News