

What agents need to know about the cost of long-term DI
Disability insurance replaces a portion of a policyholder’s regular income — usually between 40% and 60% — if physical injury, medical illness or mental health issues leave them unable to work and earn a paycheck.
When compared to life insurance, disability insurance is a massively undersold product, even though statistics should suggest otherwise. Here’s what brokers and advisors who may be interested in adding this relatively untapped product to their arsenal need to know about its cost.
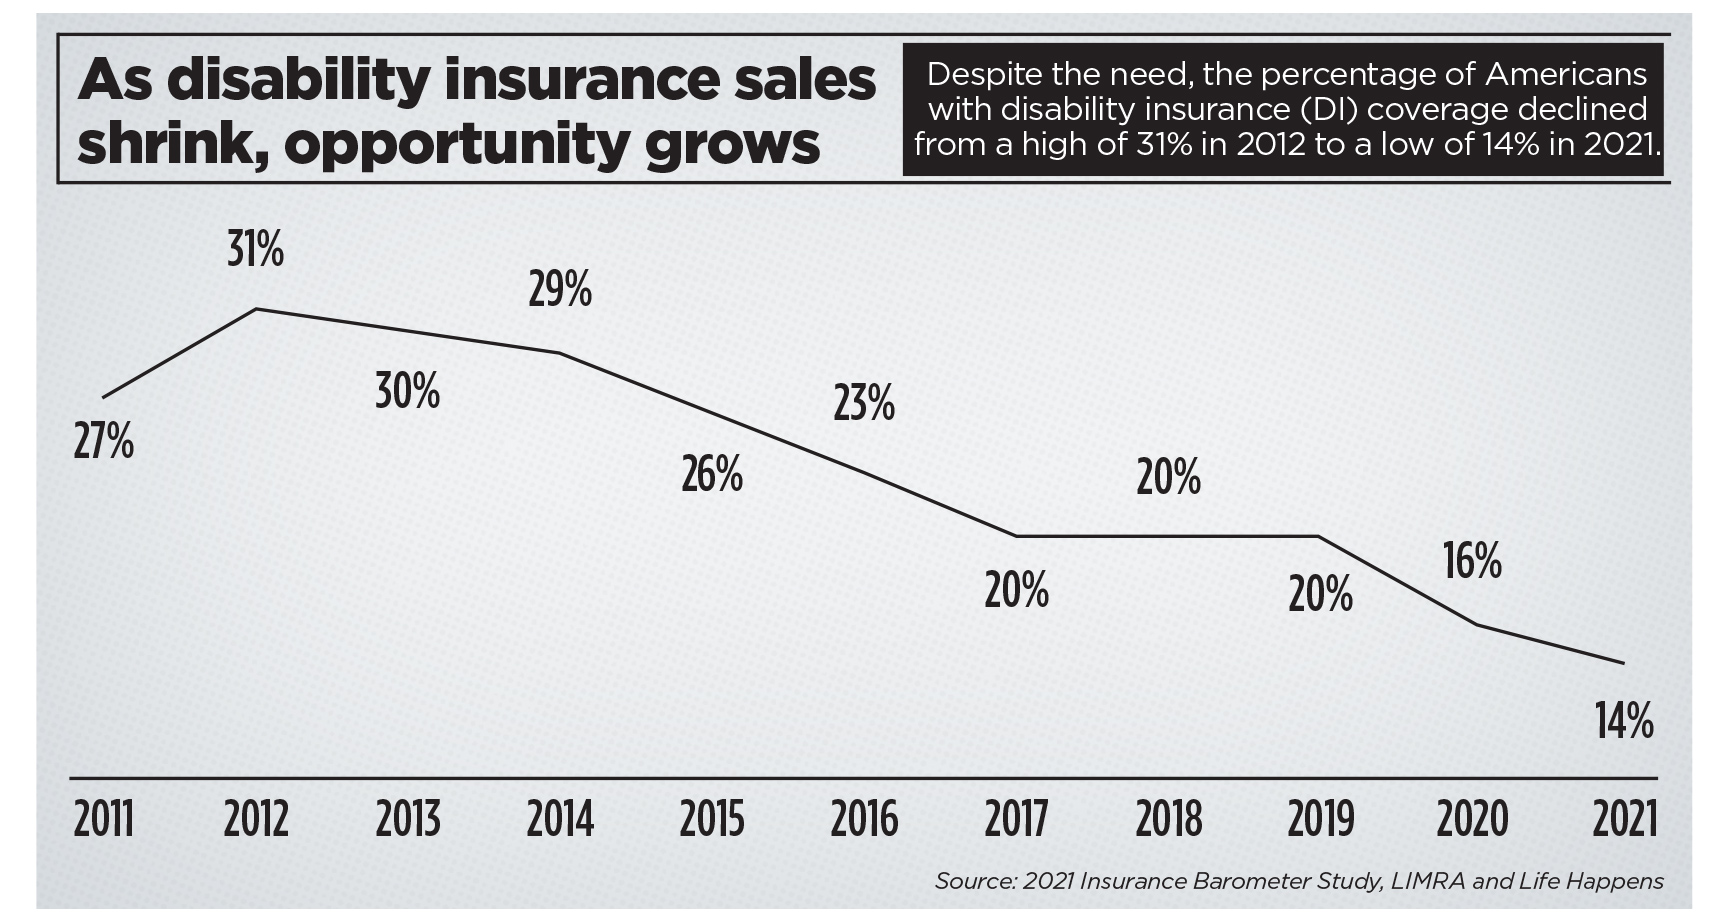
According to LIMRA, 52% of Americans own life insurance, compared to only 14% who own disability insurance.
Yet the Social Security Administration estimates today’s 20-year-olds have a 1 in 4 chance of becoming disabled during their career. Comparatively, a 25-year-old man has a 1 in 6 chance of dying before retirement, while that chance is 1 in 9 for a 25-year-old woman.
Moreover, 48% of mortgage foreclosures are due to disability, compared to only 3% due to death.
With only 14% of Americans owning disability insurance, DI presents a big opportunity for insurance agents.

There are some challenges in selling the product. Chief among those challenges is a complicated and lengthy application and underwriting process. This challenge is being addressed by insurtechs that have brought the process online and use predictive analytics to expedite underwriting.
Another challenge is a lack of awareness and knowledge about the product. A Consumer Federation survey found that only 13% of employees know “a lot” about disability insurance, compared to 52% who know “nothing at all.”
Another survey found 38% of millennials are not very familiar with either long-term or short-term disability insurance. Considering their chances of facing disability, this is concerning. With this disability insurance knowledge gap in mind, let’s focus on the cost of disability insurance so that agents, advisors and brokers can have the most up-to-date pricing data when their clients ask for it.
The cost of DI
When talking about the cost of disability insurance, the general rule of thumb is that either type (long term or short term) will have an annual premium cost between 1% and 4% of a policyholder’s annual income.
Another rule to follow is that policyholders should expect to pay between 2% and 6% of their monthly benefit amount in premium.
While those are generalizations about the cost of disability insurance, Breeze recently put together a report on disability insurance pricing. We analyzed all of our long-term disability insurance quote data from the past two full years to provide the average cost of long-term disability insurance by age, gender, occupation and state.
According to the report, the average annual disability insurance cost in 2021 was $1,297, which breaks down to $108.11 in monthly premium. In 2020, this annual figure was $1,084, or $90.33 monthly.
Although that does represent a year-over-year increase in the price for long-term disability insurance, it’s important to note consumers were looking for a much larger benefit in 2021 compared with 2020.
In 2020, the average monthly disability insurance benefit, according to our data, was $2,561. This figure surged 23% in 2021 to $3,151. It’s possible the COVID-19 pandemic encouraged consumers to seek a larger financial security net by way of a larger disability insurance benefit.
By age, there were significant differences in the annual long-term disability insurance cost. For the 18-24 age group, the annual premium cost in 2021 was $451. For those between 25 and 34, it was $863, while it was $1,354 for those ages 35 to 44.
For the 45-54 age group, the average annual cost was $1,800, while it was $1,642 for those ages 55 to 64.
There’s a significant financial advantage to taking out disability insurance at a younger age, which is something to note with clients.
Also, the average annual premium cost for women ($1,352) was higher than for men ($1,117), which falls in line with historical data that shows more women than men suffer disabilities that impact their careers.
When it comes to occupation, physicians ($3,027) and dentists ($2,460) had the highest annual premium figures, while drivers ($509) and customer service professionals ($619) had the lowest.
Factors impacting disability insurance cost
Many factors can impact the price of disability insurance, so it’s important to have this information handy for inquiring clients. Like all insurance prices, the price of disability insurance is tied to risk.
In terms of physical factors, the healthier a client is, the less they likely will pay. A nonsmoking 25-year-old with no negative health history will likely pay a lower rate than a 45-year-old smoker who has undergone multiple medical procedures.
When it comes to occupational factors, income and occupation will come into play. The higher their income, the more a client will likely pay, because the benefit will have to be bigger. The riskier the occupation, the higher premium one might pay. A roofer has a much greater chance of getting injured than an accountant does.
Policy details also will have an impact on the cost of disability insurance. Selecting a longer benefit period likely will increase the premium, as will selecting a shorter waiting period. And last, selecting a larger benefit amount will also probably raise the premium rate for disability insurance.
Disability insurance is a great opportunity for insurance agents, advisors and brokers, but client education remains a hurdle. Keeping your clients informed on what they might pay for disability insurance will go a long way toward producing policies.


Three things advisors want recruiters to know
On a journey to understand the changing financial landscape
Advisor News
- How advisors can help frugal retirees finally enjoy their savings
- Wealth planning vs. estate planning: Honoring your client’s wishes
- What to discuss during the first retirement planning meeting
- Inflation, competing priorities and uncertainty erode retirement security
- As health premiums rise, 1 in 8 workers cut retirement savings
More Advisor NewsAnnuity News
- Jackson Announces New Annuity Offering for AARP Members
- National Life Group expands annuity portfolio
- AM Best to Join Life/Annuity Insurance-Focused Panel Discussion at Capitol Forum Event
- USAA Earns No. 1 Ranking in JD Power Individual Annuity Study for the Third Consecutive Year
- How flexible annuities fit today’s retirement portfolios
More Annuity NewsHealth/Employee Benefits News
- MDHS announces open enrollment assistance for eligible families through SHIP
- Findings in Health Policy and Planning Reported from University of Kentucky (The Enrolment Paradox: Qualitative Evidence on Gendered Barriers to National Health Insurance for Ghana’s Poorest Households): Health and Medicine – Health Policy and Planning
- It's ACA open enrollment time. Here are the changes for health insurance shoppers
- Gottheimer joins North Jersey families helped with military pension back pay, health insurance coverage, IRS refunds and more
- Mending Health moves into conservatorship as Oklahoma steps up oversight
More Health/Employee Benefits NewsLife Insurance News
- Corebridge Financial Announces Third Quarter 2026 Results
- MassMutual announces record $3.3 billion policyowner dividend for 2027
- Protective Completes Acquisition of Obsidian, Establishing Specialty Property and Casualty Business Line
- Jackson Announces New Annuity Offering for AARP Members
- Open Enrollment Starts November 1: Tampa Broker Ryan Michalek Urges Families and the Self-Employed to Check 2027 Costs Before They Auto-Renew
More Life Insurance News