

Navigating the maze of long-term care insurance
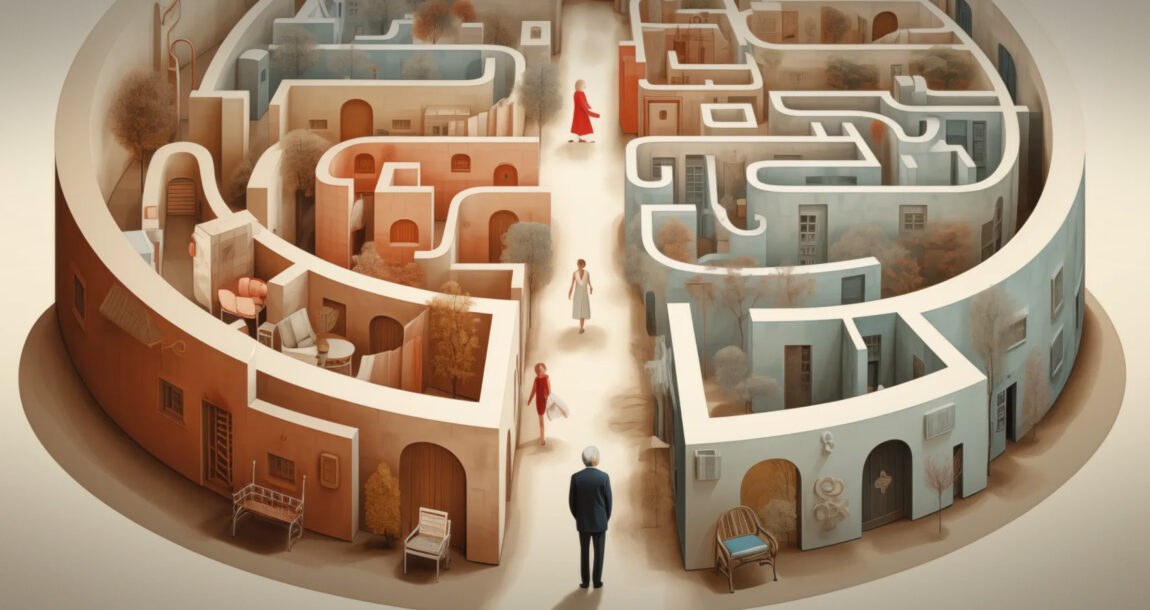
As the population ages and life expectancy continues to rise, the need for long-term care insurance has become increasingly evident. While the demand for such coverage has grown, so too have the challenges associated with selling LTCi. A recent study showed that the average person who obtains private LTCi has a household net worth of $1.4 million. Obviously, there is a greater need for such coverage beyond those with a high net worth. Financial advisors must recognize the changing landscape of aging demographics and the importance of developing expertise in this complex field.
The challenges of selling LTCi are multifaceted, ranging from client misconceptions to the intricacies of policy options. One of the primary hurdles is dispelling the myths surrounding LTCi. Many individuals believe that their health insurance or Medicare will cover the costs associated with long-term care, only to discover the reality when they face substantial bills for services such as nursing home care, assisted living or in-home assistance.
Clients must be educated about the limitations of existing health care coverage and the financial risks associated with long-term care. Moreover, the stigma attached to aging and the reluctance to confront the possibility of needing assistance add to the challenge. Advisors must approach the conversation with empathy and tact, emphasizing the importance of proactive planning to secure a comfortable and dignified future.
In a world where people are living longer, LTCi is no longer a luxury but a necessity. With advanced medical technologies and improved health care, the aging population is experiencing increased longevity. Although this is undoubtedly a positive development, it also underscores the importance of preparing for the potential need for long-term care services. As individuals age, the likelihood of requiring assistance with activities of daily living rises, making it imperative to have a financial safety net in place.
Clients should understand that planning for long-term care is not just about protecting assets but also about maintaining independence and quality of life in the golden years. LTCi acts as a crucial tool in achieving this goal, providing the means to access necessary care without depleting one’s savings or burdening family members with exorbitant caregiving responsibilities. Many of those obtaining LTCi say they do so in order to help prevent their family from taking on the burden of providing care should the need arise.
To navigate the diverse landscape of LTCi products, advisors must develop expertise in the various options available. Traditional LTCi policies, which provide coverage for nursing home and home health care services, are just one piece of the puzzle. Hybrid or linked products that combine life insurance with long-term care benefits have gained popularity, offering a death benefit if care is not needed and addressing concerns about “use it or lose it” inherent in traditional policies.

Another innovative approach involves riders that can be added to life insurance or annuity policies to provide long-term care benefits. These hybrid solutions offer flexibility and a broader range of choices for clients with different financial needs and preferences. The key is tailoring the solution to the individual, considering factors such as health, budget and risk tolerance.
The challenges of selling long-term care insurance should be seen as opportunities for advisors to make a meaningful impact on their clients’ lives. As people live longer, the need for financial protection against the costs of long-term care becomes increasingly urgent. Advisors must overcome misconceptions, address the emotional aspects of aging and develop expertise in the evolving landscape of LTCi products. By doing so, they can guide their clients toward comprehensive and personalized solutions that not only safeguard their financial well-being but also contribute to a dignified and independent aging experience.
John Forcucci
Editor-in-chief


Your client is the executor. Now what?
Tech-savvy younger clients can find HSAs a strategic tool
Advisor News
- The Gen Z money paradox
- NAIFA applauds final SECURE 2.0 regulations
- What will Democrats in Congress do about healthcare and retirement?
- Election results cloud retirement legislation outlook, experts say
- Planning for the missing chapter
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- Boomers want retirement protection, but their actions don’t match their mindset
- NAIC task force to address LTC riders
- ‘It’s really shocking:’ Regulators scrutinize assets backing annuity sellers
- Jackson Launches Direct-to-Consumer Annuity Offering
More Annuity NewsHealth/Employee Benefits News
- Vermont public schools expect the lowest health insurance increase in years. For districts, it’s only a small relief.
- Vt. public schools expect the lowest health insurance increase in years
- Samantha Wildow: Mercy Health warns thousands of Medical Mutual of Ohio patients may go out-of-network in 2027
- Reports Outline Managed Care Study Results from Harvard University (Inpatient-Only List Removals Shifted Procedures To The Outpatient Setting And Reduced Medicare Spending): Managed Care
- Health and Humor: Picking a Medicare insurance plan is daunting
More Health/Employee Benefits NewsLife Insurance News
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- U-Haul Holding Company to Participate in Deutsche Bank Conference
- NAIC task force to address LTC riders
- Protective names Kurt Meyers Chief Legal Officer and Fernando Levy Chief Digital & AI Officer
- Best’s Commentary: Shanghai Cross-Border Investment Pilot Unlocks Overseas Growth Potential of China Non-Life Companies
More Life Insurance News