

LTCi: Growing number of options available to fit client needs
Life insurance with either long-term care riders or chronic illness riders are picking up steam in the marketplace, said Steve Cain, national sales leader with LTCI Partners.
Cain spoke about the rising interest in hybrid life policies during the National Association of Insurance and Financial Advisors Peak 65 Impact Day.
“Most clients like the idea of a dual-purpose policy,” he said. “Life with chronic illness rider is seeing the lion’s share of the new business written but I still think there’s a time and a place for traditional long-term care insurance.”
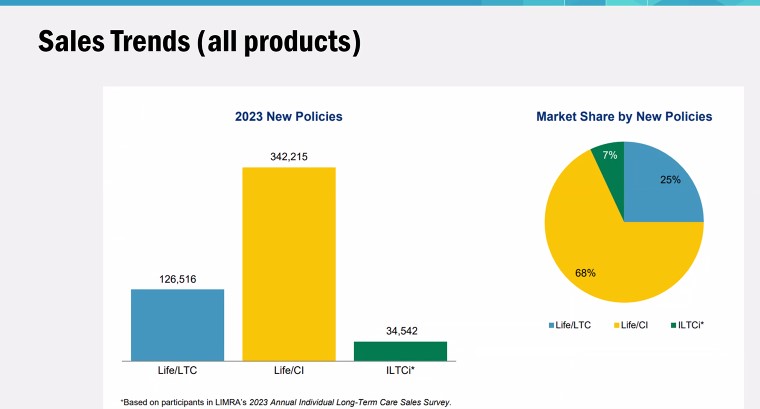
Cain cited LIMRA’s 2023 annual individual long-term care sales survey, which showed that 68% of new policies sold that year – more than 342,000 policies – were life/chronic illness combination policies. Twenty-five percent – about 126,000 policies – were life/LTC combinations while only 7% - about 34,000 policies – of new sales were traditional individual LTCi.
Consumers have several LTCi planning solutions available to them, Cain said. Those solutions include:

- Short-term care insurance.
- Traditional LTCi.
- Hybrid life plus qualified long-term care insurance.
- Life insurance with chronic illness/accelerated death benefit or QLTCi riders.
- Annuities with LTC riders.
Short-term care insurance is growing in popularity, he said. These policies may be suitable for an older client who has some health concerns. Discussing STC with an older client would be a complimentary discussion to a Medicare conversation.
Hybrid life and annuities with LTC riders are seeing some growth in the marketplace, Cain said. “Our job is to look through these and find the right solutions for your clients,” he said.
Cain said that to find the product that is the best fit for a client, advisors must ask the following:
- What is the client’s health condition?
- How much coverage does the client need now and at age 85?
- Does the client need life insurance?
- What is the client’s budget?
- Is the client comfortable paying for a “pure protection” product?
- Are premium guarantees important to the client?
Buying long-term care coverage is “a mind share and a wallet share issue,” Cain said.
“I have to think about protecting my family, but beyond that, I have to be able to afford it.”
© Entire contents copyright 2024 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


How SECURE impacts inherited IRA beneficiaries
Police announce arrest in connection with murder of UnitedHealthcare CEO
Advisor News
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- Open enrollment is now for 2027 health insurance coverage in Illinois: What to know
- Idaho insurance director details $13M school trust collapse
- Insurance program's collapse detailed at ISBA conference
- Boeing retirees ‘shocked’ by 400% jump in health insurance premiums
- MEDICAID PAYMENT TRANSPARENCY RULES: STATE REPORTING REQUIREMENTS AND LIMITATIONS
More Health/Employee Benefits NewsLife Insurance News
- Best’s Market Segment Report: Health and Property Lines of Business Drive Hong Kong’s Non-Life Insurance Growth
- AM Best Affirms Credit Ratings of Central States Indemnity Co. of Omaha and Its Subsidiary
- National Life Group Approves $23 Million Dividends for 2027
- Milliman’s proposed $15.5 million settlement puts life insurance underwriting data in focus
- Brighthouse Financial Announces Third Quarter 2026 Results
More Life Insurance News