

Is financial security possible in the longevity economy?

Every year, the Society of Certified Senior Advisors brings together longevity professionals on the front lines of aging in America — the advisors, advocates, and caregivers who help families navigate the single most expensive, least understood phase of retirement.
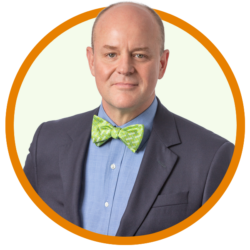
At this year's 11th Annual CSA Meeting in Denver, that conversation took center stage in a plenary session titled "Financial Security — Is It Possible in the Longevity Economy?" As a panelist alongside four colleagues from across insurance, financial planning and consumer protection, I came away convinced the industry has the tools it needs. What's missing is the roadmap for how to use them.
An iceberg, not a speed bump
Moderator Carmen Perry, chair of the National Aging in Place Council, opened the session with a line that set the tone for everything that followed: Aging may be a state of mind, but no mindset pays a nursing home bill. Too many people build a retirement plan around vacations and grandchildren while quietly assuming that the need for extended care "won't happen to me." The numbers say otherwise, and the financial consequences of that assumption can be severe — the cost of assisted living, memory care or skilled nursing can erode a lifetime of savings in a matter of months, not years.
Dennis Rinner, director of strategic accounts for GoldenCare, an Integrity company, opened the panelist discussion by naming the stakes directly. A care event, he explained, is "the single biggest unplanned, unfunded liability that an individual will encounter in their lifetime." Even people who did everything right on the accumulation side of retirement planning can find themselves financially exposed the moment a health crisis hits. Rinner's prescription is a layered one: long-term care insurance for those who need robust, extended coverage, and short-term care insurance as a more accessible, affordable complement for shorter-duration needs or those who don't qualify for traditional LTCi. Together, he noted, the two create "a layered defense against care costs at every stage of aging."
The ‘Big 5’ and the case for stacking
As the panel turned to private pay solutions, I walked through the "Big 5" private pay tools — long-term care and short-term care insurance, annuities with LTC riders, life settlements, home equity release and VA benefits. The critical takeaway: None of these tools is mutually exclusive. Many people already collecting Social Security and enrolled in Medicare also have a home, a life insurance policy, an annuity or veteran's benefits without realizing each can be tapped — sequentially or simultaneously — to build a "funding stream." Knowing which resources to activate in advance, and which to hold in reserve until care is needed, is the difference between navigating the long-term care industrial complex successfully and being blindsided by it.
Where public programs fall short
Martha Shedden, president and cofounder of the National Association of Registered Social Security Analysts, brought the conversation back to the public side of the ledger. More than 74 million Americans receive Social Security and over 66 million rely on Medicare, yet widespread misconceptions about both programs continue to drive poor financial decisions with lifelong consequences. The most damaging, Shedden noted, is the assumption that Medicare covers long-term care — it does not.

She pointed to a growing shift toward integrated planning models that align Social Security claiming strategy with Medicare enrollment and longevity projections, arguing that coordinated decision-making, rather than isolated choices made in a vacuum, is where the industry must head next.
Fraud is the fastest-growing threat
No conversation about senior financial security is complete without addressing fraud, and Jonas Roeser, CEO and founder of AgentReview.net, delivered one of the session's most sobering assessments.
Deceptive marketing, unauthorized enrollments, lead-generation abuses and now AI-powered scams — deepfakes, voice cloning and increasingly convincing impersonation schemes — are targeting seniors and retirees at a scale the industry has never seen. Roeser's point cuts both ways: the same artificial intelligence being weaponized against consumers can also be deployed to protect them, through stronger identity verification, greater transparency and tools that help people confirm exactly who they're working with before making a decision.
His closing thought is one worth repeating across the industry — as retirement and healthcare planning grow more interconnected and complex, the organizations and professionals who earn and demonstrably maintain trust will be those best positioned to serve consumers in the future.
The middle-class bulge
When the panel turned to "the elephant in the room," the conversation converged quickly. There is a rapidly expanding population of households that earn too much to qualify for Medicaid but not nearly enough to comfortably absorb the cost of a major care event. This middle-class bulge needs products and guidance that combine public benefits expertise with flexible income solutions — and right now, awareness of that combination is in short supply.
Sequencing, not guesswork
John W. Wheeler Jr., executive senior partner at Totus Wealth Management and incoming President of the National Association of Insurance and Financial Advisors, offered the session's most useful metaphor for how to do this work. Holistic financial planning is like assembling a jigsaw puzzle, and you can't build the picture without first understanding the picture on the box — a client's actual goals, values and priorities. From there, sequencing public and private resources becomes a deliberate exercise rather than a guessing game, one that starts with honest reflection about the kind of life a person hopes to live as they age.
Timing is the real skill
The panel closed on timing — some tools, such as LTCi and annuities, work best when purchased proactively, years before they're needed. Others, such as life settlements and reverse mortgages, are built to be activated at the point of crisis. Knowing which lever to pull, and when, is arguably the most valuable skill an advisor can offer a client.
As Perry said in her closing remarks, the need for extended care is an iceberg in the path of an otherwise "unsinkable" retirement. The tools to avoid that collision already exist. The families who fare best are the ones who start the conversation early, ask the right questions, and build their own funding stream before a crisis forces their hand. That's the work our industry is best positioned to do.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Advisors await SEC decision on Vanguard fair fund distribution
Mending Health lands under Oklahoma supervision following ACA exit
Advisor News
- Are families ready for the costs of aging at home?
- When a client moves, their insurance plan needs to move, too
- A rising retirement challenge: The license to spend
- Financial stress leaves less room for retirement saving
- Giving while you’re living: 3 frequently asked questions about gifting
More Advisor NewsAnnuity News
- Global Atlantic names Dan Farrelly head of IMO and IBD channels
- A rising retirement challenge: The license to spend
- What lower interest rates mean to annuity payouts
- AM Best downgrades A-Cap insurers amid financial and regulatory troubles
- Lawsuit claims Delaware Life hid billions in insurer-linked investments
More Annuity NewsLife Insurance News
Property and Casualty News
- State Farm raising Illinois homeowners insurance rates by 8%
- Today’s consumers have ‘zero tolerance’ for slow claims payouts
- WARREN, HAWLEY PRESS HOME AND AUTO INSURERS ON SURGE IN CLAIMS RESOLVED WITHOUT PAYMENT
- wildfire-mitigation-insurance-savings
- TEXAS SENIORS GET PROPERTY TAX BREAK
More Property and Casualty News