

Why Social Security alone isn’t enough — Is Tony Robbins’ warning still relevant?
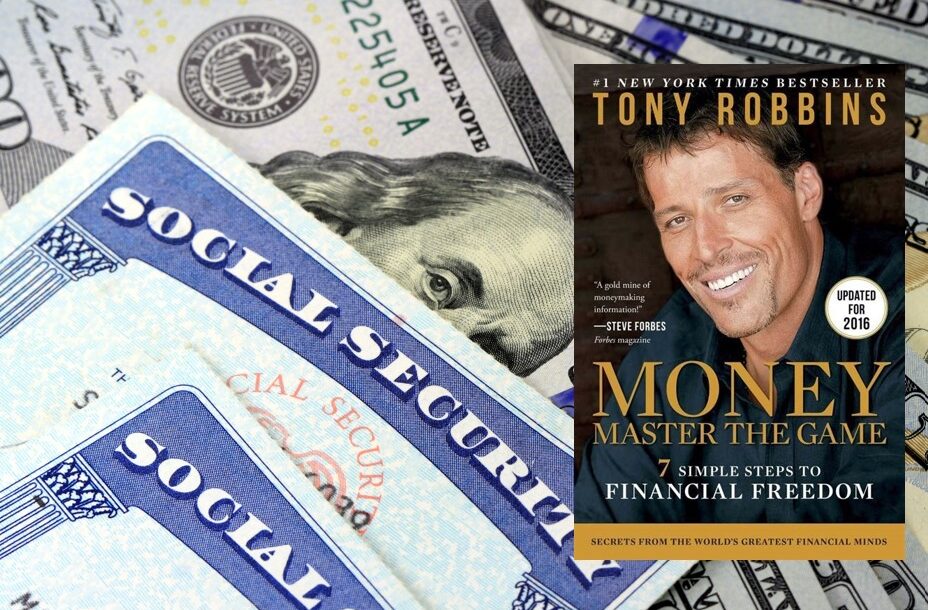
As Social Security is squarely in the spotlight under the current administration, with cuts to government staff and funding uncertainty, InsuranceNewsNet looks back on Tony Robbins' book, "Money: Master the Game," to see if Robbins' thoughts and advice on Social Security still apply today.
In his 2014 book, Tony Robbins doesn’t mince words when it comes to Social Security. He makes a clear and urgent case: while Social Security can be a helpful piece of retirement planning, it is grossly insufficient on its own. For financial advisors working with clients across generations, Robbins’ perspective offers not just caution, but a roadmap for smarter income planning.
As Robbins says in his book: “The Social Security Act eased the suffering of millions of Americans during a time of crisis, but it was never intended to become a replacement for retirement savings—just a supplement to cover the most basic needs.”
Built for a shorter life
Robbins reminds readers that when Social Security was introduced in the 1930s, life expectancy in the U.S. was just 62 years. Retirement benefits didn’t begin until 65, meaning few people were expected to collect for long. Today, that landscape has shifted dramatically:
“There’s a 50% chance that, among married couples, at least one spouse will live to the age of 92 and a 25% chance that one will live to 97,” Robbins writes.
The implications are profound. Retirement now spans decades, not years, and the math no longer adds up:

“It is not realistic to finance a 30-year retirement with 30 years of work. You can’t expect to put 10% of your income aside and then finance a retirement that’s just as long.”
The numbers no longer work
In the 1950s, 16.5 workers supported each retiree. Today? That number has fallen to 2.9.
"The math doesn’t pencil out, but since when has that stopped Washington?" asks Robbins.
Add in increasing longevity, market volatility, and inflation, and the already strained program becomes even shakier. According to Robbins:
"With 10,000 baby boomers turning 65 every day... [Social Security] may not even be around, at least as we know it."
A false sense of security
Robbins illustrates the emotional impact of this gap using a powerful statistic:
"The number one fear of baby boomers was outliving their savings. (Death, by the way, checked in a distant second.)"
And with the average monthly benefit at just $1,294:
"How far do you think that will stretch if you live in New York, Los Angeles, Chicago, or Miami?"
Case Study: The role of Social Security
In his book, Robbins introduces us to Angela, a woman who didn’t start saving until age 48. Initially, she thought she needed $34,000 in income annually to reach financial security. But once she factored in $1,250/month in projected Social Security benefits, her gap narrowed significantly:
"She shaved a full decade off her timeline. Instead of getting to Financial Security at 72, she was going to get there at 62!"
Angela’s story underscores a critical point: while not sufficient on its own, Social Security still plays a valuable role when paired with other income streams.
Advisors: It’s time for hard conversations
For financial advisors, Robbins’ view presents both a challenge and an opportunity. The challenge is confronting outdated client assumptions about government-backed guarantees. The opportunity is helping clients pivot toward more sustainable, diversified income strategies.
"Almost half of us have yet to take one of the first steps toward planning for our financial futures—and our time of reckoning is coming."
Guaranteed Income: The Holy Grail
"A paycheck for life without ever having to work again... That’s income for life, and there’s a way to get it," writes Robbins.
Robbins explains how products like FIAs provide upside potential without downside risk. These annuities offer:
- 100% principal protection
- Market-linked gains
- Tax-deferred growth
- Guaranteed income for life
- No annual management fees
He stresses that while these tools may sound too good to be true, they are viable and regulated.
What makes FIAs appealing
"It’s probably hard for you to imagine that there’s a structure available today that can deliver for you... But it’s here!"
Robbins is candid: FIAs aren’t just for the ultra-wealthy. With as little as $300/month, clients can begin building guaranteed income stream.
"You’ll be able to create a guaranteed income stream, allowing you to build, manage, and enjoy your own personal ‘pension’ on your own terms."
Don’t wait for the market to rescue you
Traditional 401(k)s or IRAs alone may not be enough. Robbins warns against the myth of simply accumulating assets without a distribution plan:
"Achieving critical mass without having a plan and strategy for how to turn it into income... will leave you like George Mallory: dead on the back side of a mountain."
A new era of retirement planning
The pension is dead, Robbins declares, and today’s retirees must be their own CFOs.
"You are ultimately responsible for whether or not your money will last. That’s quite a burden to bear."
This is where income planning takes center stage. Financial advisors should focus not just on asset growth but on strategies that provide income regardless of market conditions.
Final word for financial advisors
For advisors, Robbins’ message is clear: educate clients on the new retirement reality and introduce them to tools that offer both growth and guaranteed income. The earlier clients start planning for income—not just accumulation—the greater their long-term security.
"You can stop imagining—it’s here!"
.


Partnership formed to confront rise in illness, premature death in young Americans
Corebridge Financial rides RILA rollout success amid choppy Q1 waters
Annuity News
- National Life Group expands annuity portfolio
- AM Best to Join Life/Annuity Insurance-Focused Panel Discussion at Capitol Forum Event
- USAA Earns No. 1 Ranking in JD Power Individual Annuity Study for the Third Consecutive Year
- How flexible annuities fit today’s retirement portfolios
- Foresters Financial appoints Tom Ross as chief distribution officer for U.S. annuity sales
More Annuity NewsHealth/Employee Benefits News
- As WA open enrollment begins, far fewer than expected have lost coverage
- Pennsylvania Health Plans Must Cover Colon Cancer Screening at 45
- In Miami-Dade court, health insurer fights an order to cover $48,500 cancer drug
- Fed judge blocks Medicaid work requirement rule
- Health insurers leave millions unpaid for mental health crisis care in California
More Health/Employee Benefits NewsLife Insurance News
- AM Best Affirms Credit Ratings of Insignia Life S.A. de C.V.
- FINANCIAL FRAUD
- Security Benefit Announces Planned Dividend Rate Reset for Series B Preferred Stock
- Palmetto Heritage and Atlantic Coast Life Announce Discussions Regarding Potential Acquisition
- Jury finds insurance company acted in bad faith, awards Nebraska woman $11.3M
More Life Insurance NewsProperty and Casualty News
- AROUND TOWN: Birrell raises more in latest filing, but Redmon maintains overall fundraising lead
- Commentary: Mark Gongloff: Why home insurance costs more than property tax
- Vehicle insurance ordinance brings Bluefield in line with W.Va. code
- Genworth CEO to retire at year's end
- New Pennsylvania Law Will Make Home Sellers Disclose Flood History, FEMA Zone and Past Flood Claims
More Property and Casualty News