

Overcoming the all-or-nothing mindset
It is clear that there is a life insurance need gap — the difference between those who say they need life insurance and those who actually own it — and therefore a large opportunity for more individuals to obtain coverage. However, booming sales have not materialized. According to LIMRA, total U.S. retail life insurance new annualized premium fell 7% in the first quarter of 2023 to $3.7 billion. How do we grow this market?
One area to consider is helping consumers overcome the all-or-nothing mindset. This mindset refers to a thought process where individuals perceive things in extremes, considering situations or outcomes as either completely successful or completely unsuccessful. This mindset can make it challenging to find balance and to create realistic expectations. In many cases, individuals will just procrastinate and be inert.
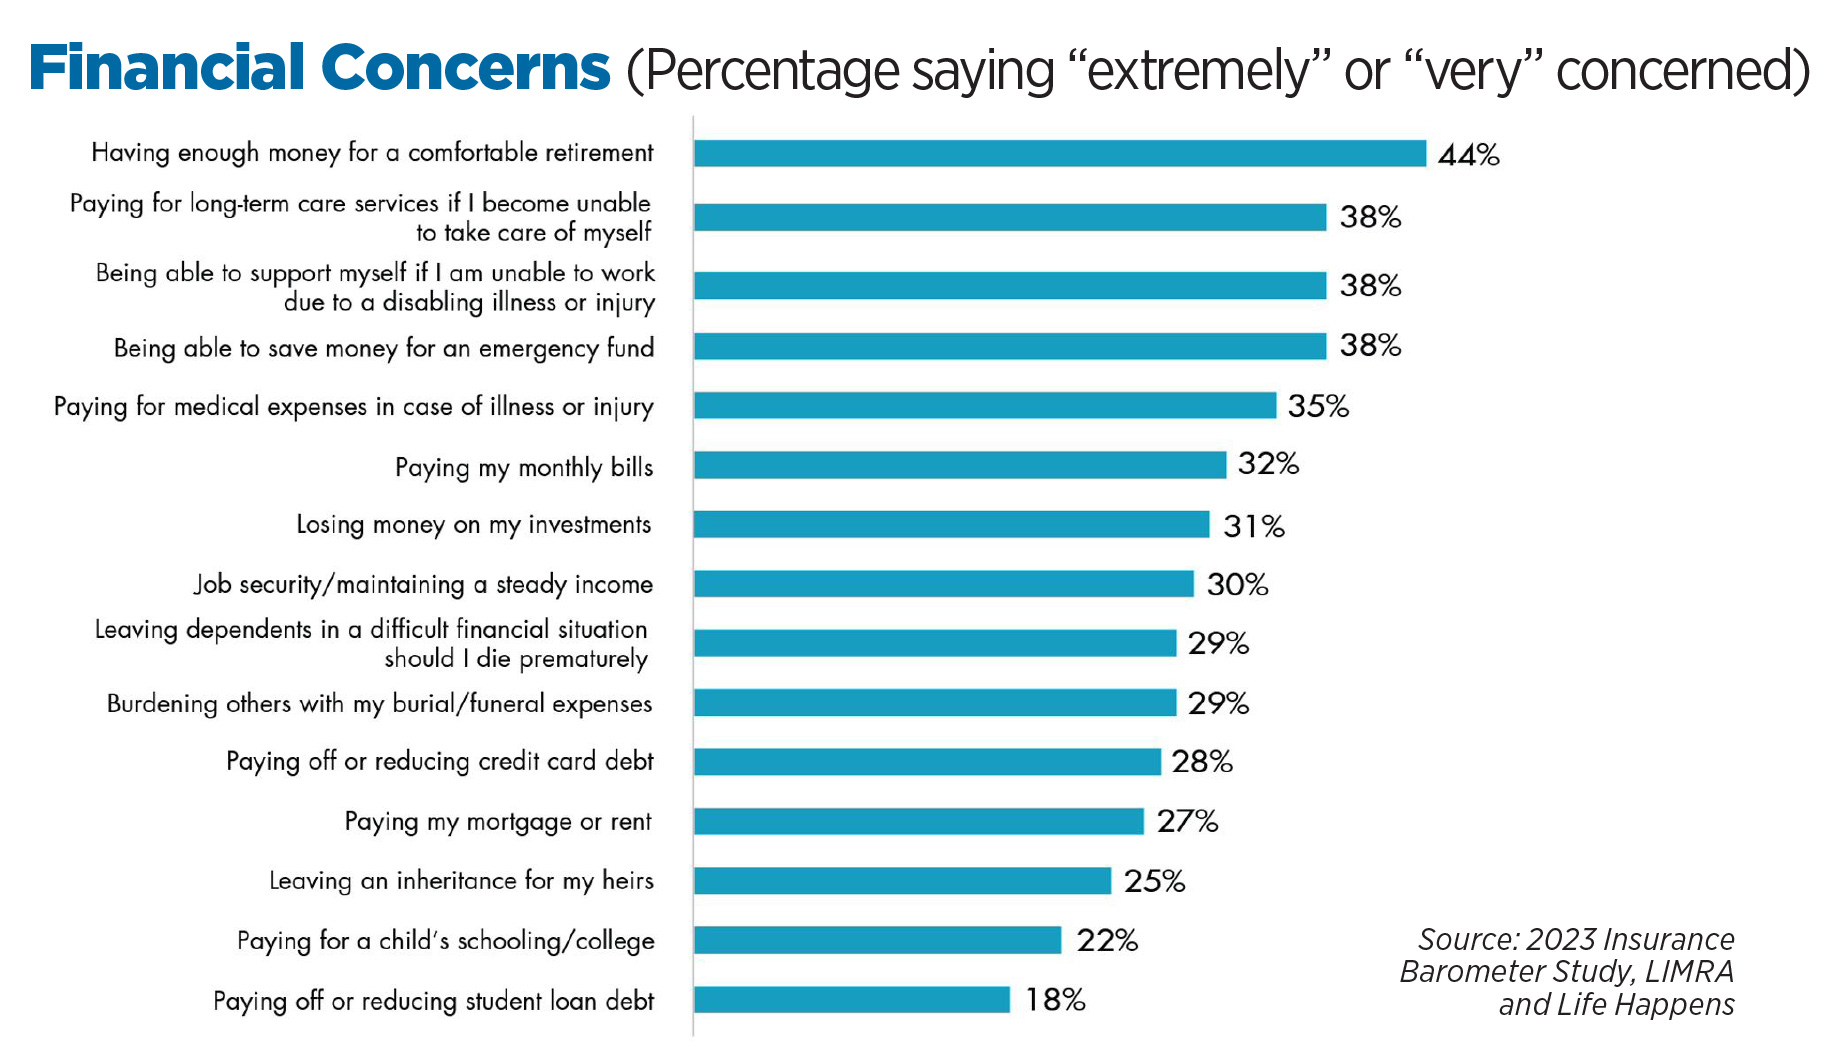
According to the 2023 Insurance Barometer Study, conducted by LIMRA and Life Happens, today’s consumers are trying to manage a multitude of financial concerns. Things such as saving money, paying monthly bills and paying down debt, or burdening others with their expenses are top of mind. These financial concerns could lead to consumer paralysis or result in consumers coming up with excuses. Two key reasons for not purchasing life insurance are “having other financial priorities” and “haven’t gotten around to it.”
Here are three things agents/advisors could do to help close the need gap.
1. Help individuals focus on small goals. Let them achieve and make progress. It doesn’t have to be all doom and gloom. Let them build momentum and see results.

In some cases, full-blown financial planning can be overwhelming and lead to customer concerns. According to a survey by Schroders, 76% of Americans say they feel overwhelmed by the thought of creating a financial plan and 56% say life is too uncertain for a plan to have any value.
2. Illustrate the impact of a dollar. Consumers can more easily visualize small dollar amounts through mental accounting. How much insurance could you buy instead of buying a latte? A relatively small change can amplify positive outcomes at relatively minimal cost.
There is also the potential to use subscription-based terminology and marketing to align with the growth of plans such as Netflix or Amazon Prime. According to eLabs, 64% of respondents say that they feel which connected to companies with which they have a direct subscription experience versus companies whose products they simply purchase as one-off transactions. In addition, 78% of adults globally have a subscription service.
3. Embrace digital in order to be relevant for younger consumers. For the first time, consumers are more likely to say they would prefer buying life insurance online than by any other method.
This is especially true for young adults. They expect a seamless experience and streamlined process that enables them to purchase coverage quickly and easily.
Younger customers also appreciate flexibility and personalized options. As you build trust over time, having the ability to offer your customers customized coverage based on their specific needs and budget will be crucial. You could start with simple and easy product options like term life insurance and increase coverage with other products as their circumstances change.
The financial services industry has always been based on relationships. That hasn’t changed. But to be effective, approaching these relationships must evolve to include a better understanding of clients’ needs, trying new sales tactics and embracing technology.
This will increase sales of life insurance across different and new demographics and help more Americans get the coverage they need to protect their loved ones.


Charting the course of life insurance
Annuities can help manage income risks in retirement
Advisor News
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
- How advisors can help frugal retirees finally enjoy their savings
- Wealth planning vs. estate planning: Honoring your client’s wishes
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- Researchers from Federal Reserve Bank of Philadelphia Report New Studies and Findings in the Area of Managed Care (Missouri’s Medicaid Contraction and Consumer Financial Outcomes): Managed Care
- Research Results from University of Maryland Update Knowledge of Heart Failure (Alcohol screening, counseling, and medication treatment among older adults with heart failure: A missed opportunity): Heart Disorders and Diseases – Heart Failure
- Take 5: What You Need to Know About Open Enrollment and the Affordable Care Act
- As WA open enrollment begins, far fewer than expected have lost coverage
- Genworth Financial Announces Third Quarter 2026 Results
More Health/Employee Benefits NewsLife Insurance News
- U-Haul Holding Company Reports Second Quarter Fiscal 2027 Financial Results
- Genworth Financial Announces Third Quarter 2026 Results
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Why the market doesn’t need more carriers
- Unum Group Reports Third Quarter 2026 Results
More Life Insurance News