

Determining tipping points for climate risk management
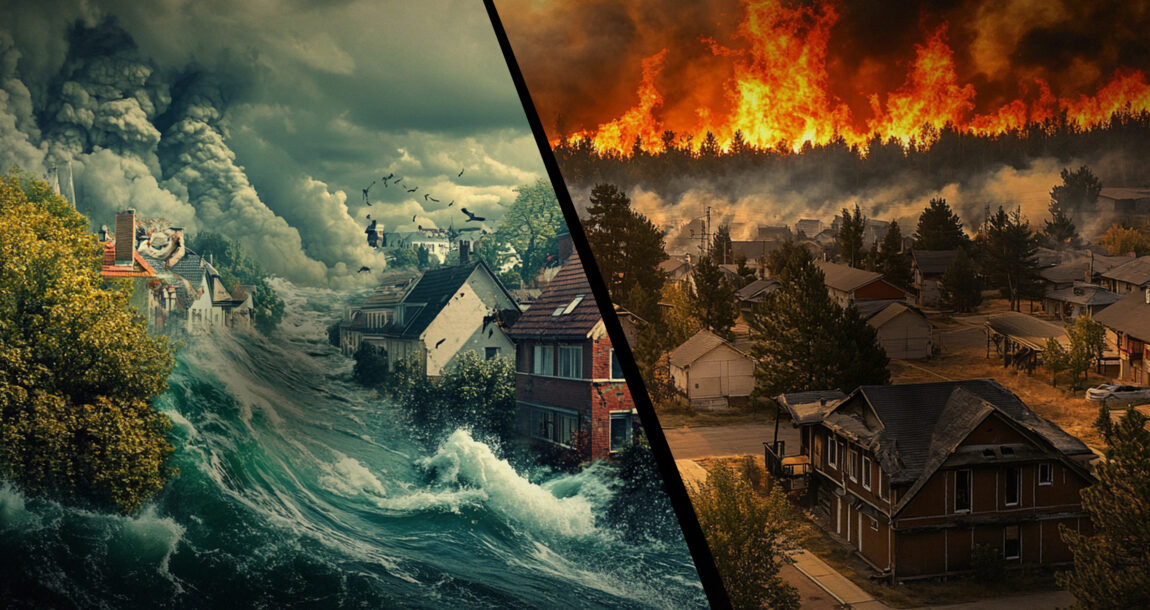
The year 2024 was the world’s hottest on record, according to the U.S. Oceanic and Atmospheric Administration. Global land and ocean temperatures were 2.32 degrees F (1.29 degrees C) above the 20th-century average, approaching the 2.7-degree F (1.5-degree C) limit that many scientists believe must not be exceeded to avoid the more severe effects of climate change.
As climate change progresses, actuaries and insurance professionals require a method for identifying climate scenarios that could constitute a regime shift. “Tipping points,” which are thresholds in a system, can signal a regime shift when crossed.
What constitutes a different future?
Examples of physical climate tipping points include the thawing of Arctic-tundra permafrost and the loss of Arctic sea ice. Climate change has contributed to both of these phenomena, which contributes to further warming. This creates a positive feedback loop that reinforces the changes until they are irreversible.
Climate tipping points can also have societal impacts. For instance, melting Arctic sea ice may lead to rising sea levels, forcing populations to relocate from coastal areas. This migration could cause additional abrupt changes, such as declines in home values.
Socioeconomic tipping points can sometimes drive positive outcomes, such as advancements in technology or behavioral changes that mitigate climate risks. However, they can also lead to financial risks. Insurability is one example of an SETP that could result in financial risk for businesses and communities. Climate tipping points could cause insurers to withdraw from local areas or entire markets, leaving businesses and individuals without insurance protection. The unavailability of insurance could thwart recovery efforts after climate-related disasters.
Insurability tipping points can have profound implications. Developing methods to identify these tipping points is crucial for developing resilience, mitigating the impacts of climate change, and ensuring the continued availability of affordable insurance coverage.

Tipping points: Three criteria
Actuaries, who analyze risk for insurance companies and other industries, use models to predict potential outcomes. Although climate tipping points continue to be an active area of scientific research, they have not yet been incorporated into actuarial models. Tipping points are typically applied to geologic timescales — which can span millions of years — so, they are not currently factored into climate projections.
However, actuaries can focus on climate systems operating on shorter, more relevant timeframes. By adopting a a narrower climate framework, actuaries can apply statistical metrics to identify important changes in local climates, and manage associated risks and opportunities for their organizations. In particular, actuaries can watch for three statistical benchmarks that signal a tipping point.
- Lag-1 autocorrelation: Identifies abrupt changes based on correlations between values from two consecutive time periods.
- Variance: Metrics showing one stable state moving into another stable state.
- Mean: Reflects fundamentally different average values before and after a regime shift.
For a regime shift to be confirmed, all three benchmarks should consistently signal the same transition point.
Framework for identifying regime shifts
The Society of Actuaries Research Institute report, Tipping Points in Climate-related Insurance Models, aims to bridge the gap between climate science and actuarial practices by applying a seven-step framework to identify regime shifts. Actuaries can use climate projections to identify tipping points under both moderate and high emissions environments, which can help insurers understand how the frequency and intensity of extreme weather events might impact their businesses.
Regime shifts in heat-related deaths in Seattle
For example, climate experts predict an increase in the number of days with dangerously high temperatures in Seattle. At the same time, residents in this region are less likely to have air conditioning, making them more vulnerable to extreme heat. A regime shift in heat extremes could lead to a rise in heat-related illnesses.
Following the framework for identifying regime shifts, researchers analyzed the Seattle wet-bulb globe temperature, a measure that estimates the impact of temperature, humidity, radiant heat and air movement on the human body. WBGT is considered a more accurate measure of the effects of heat on people. The report’s authors examined whether WBGT trends meet the three regime-shift criteria: change in lag-1 autocorrelation, change in variance, change in mean. Researchers analyzed both moderate and high emission climate scenario models.
The findings suggest that the number of days in which WBGT exceed Seattle’s historic 90th percentile will increase with higher greenhouse gas emissions.
Under a low-emissions scenario, abrupt shifts in WBGT coincide with mean and variance shifts in the years 2058 and 2061. This could mean that heat stress and heat-related deaths will likely experience a regime shift within these years (2058-2061). Under a high emissions scenario, abrupt changes coincide with mean and variance changes a number of years earlier, in 2046 and 2049, marking a new regime shift in heat-related deaths in the late 2040s.
Spotting changes in societal norms
Socioeconomic tipping points often cascade, where a small change in underlying factors triggers large nonlinear societal responses. Climate-related examples include populations moving away from areas impacted by sea-level rise or climate events, making it unfeasible to underwrite property insurance there.
Insurers can improve climate-risk management by determining potential regime shifts and SETPs and then incorporating these into their decision-making. For example, indicators of a SETP resulting from higher rates of death due to heat-related illness include increased rates of hospitalization, mortality, outdoor work accidents, morbidity, grid failure and low rates of air conditioning use.
Actuaries can use publicly available data and straightforward statistics to pinpoint potential regime shifts that may impact their organizations. They can then develop strategies to mitigate the risks and identify potential opportunities. For example, in response to increased heatwaves, insurers can offer parametric insurance policies, which pays policyholders a set amount when a specified event occurs instead of paying for losses, or they can develop heat-stress insurance in response to workers’ exposure to extreme heat.
As climate change progresses, the insurance industry needs methods to identify regime shifts. By incorporating a framework to spot tipping points into risk management, underwriting, pricing and investment management processes, insurers can be better prepared to adapt to our changing climate.
© Entire contents copyright 2025 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Morningstar: U.S. life insurers maintaining cash liquidity levels
Globe Life hit with a pair of lawsuits over handling of 2024 data breach
Advisor News
- Navigating client communication in a digital age
- Can your advisory firm survive without you?
- I started using AI, but what now?
- How to support an entrepreneur client with multiple businesses
- Could a narrower focus help grow your practice?
More Advisor NewsAnnuity News
- Solen Software Group Acquires Cooperative Technologies, Provider of 1035 Exchange and Annuity Replacement Software
- MassMutual Expands Lending Options With New Secured Credit Line
- Corebridge Financial Introduces Progressive Trigger, a First-of-Its-Kind Index Annuity Strategy Designed to Turn Missed Years into Future Opportunity
- Insurer proposes $1.1M deal to resolve CA teachers’ annuity fee lawsuit
- IMOs get frustrated with slow carrier adoption of faster technology
More Annuity NewsHealth/Employee Benefits News
- Seniors can get help wth Medicare sign-ups
- Oscar Introduces a New Wave of Consumer Health Products
- MAYOR MAMDANI LAUNCHES OUTREACH TEAM TO HELP NEW YORKERS KEEP MEDICAID AS FEDERAL CUTS THREATEN COVERAGE
- Legislators hear report on thin hospital margins, advance prior authorization reform
- Researchers from Department of Research and Innovation Report on Findings in Managed Care (Quantifying Medicare prescription payment plan benefits under Medicare Part D): Managed Care
More Health/Employee Benefits NewsLife Insurance News