

Post-Pandemic Economic Growth Could Last ‘For Many Years’
By Ryan Detrick
The economic recovery continues, as the recipe of vaccines, the reopening, and record stimulus all have combined to produce what should be one of the best years for growth ever.
Although some economic indicators could be peaking or about to peak, the stage is set for this cycle of growth to continue for many years, which may surprise some investors. We discuss why inflation might be in the headlines, but still shouldn’t be a major worry for investors.
Young Economic Cycle
The U.S. economic recovery is now in full swing. Despite the natural challenges of ramping back up, the recovery still seems capable of providing upside surprises. As a result of strides toward full reopening, rapid vaccine distribution, massive stimulus efforts, and support from the Fed, we recently upgraded our 2021 forecast for U.S. gross domestic product (GDP) growth to 6.25%-6.75%.
Toss in a record number of earnings beats, resulting in S&P 500 Index first-quarter earnings growth of nearly 50% (FactSet), which is more than double the expectations at the start of the quarter, and it is clear the economy is humming right along. Last year’s 3.5% drop in GDP, the worst year since the Great Depression, is a thing of the past.
Technically, the U.S. may still be in a recession, as the National Bureau of Economic Research (NBER) hasn’t called the end yet. But considering we’ve seen various levels of output match or exceed pre-pandemic levels, it’s clear we aren’t in a recession anymore, as it likely ended last summer.

Retail sales, for instance, were making new highs by June 2020 and have soared higher over the past year. NBER isn’t about being first, they are about being right, and it isn’t abnormal for them to call the end of a recession a year or more after it officially ended. We’ve found that ISM manufacturing and services data tend to peak about a year after a recession ends, and both appear to have peaked in the spring—another clue the recession ended sometime last summer.
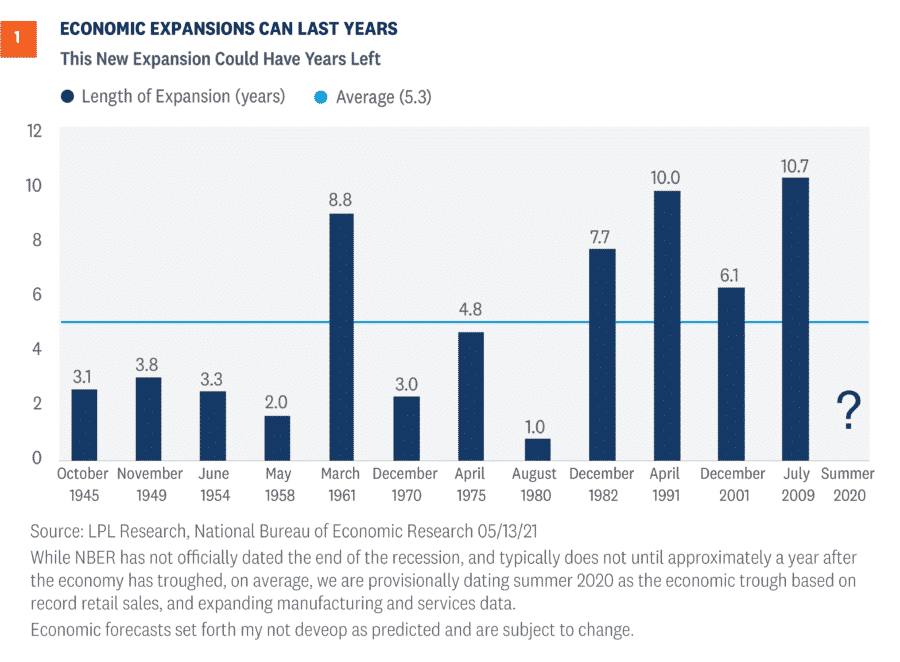
Just because economic data is peaking doesn’t mean the new expansion is over. In fact, it’s perfectly normal to see the year-over-year levels of growth peak about a year after a recession ends, and be followed by many more years of growth. As shown in [Figure 1], the average expansion has lasted more than five years, with the last four cycles all lasting longer.
The last expansion was the longest ever, making it to 11 years old before COVID-19 struck, and otherwise might have gone on even longer. However, this cycle may not last as long as the last one, as this wasn’t your average recession.
Because the recession last year was likely the shortest ever (besting the six-month recession in the early 1980s) and the economy was supported by historic stimulus, some imbalances weren’t worked off like we tend to see in a normal recession. Corporate debt levels remain high, supported by low interest rates, and stock valuations never really reset.
The good news is this new cycle of growth has enough going for it to be at least average, and even that would mean it still has another four years of economic growth left. There’s nothing wrong with being average!
Let's Talk About Inflation
The U.S. Bureau of Labor Statistics released its monthly report on inflation on Wednesday, May 12, revealing that the headline Consumer Price Index (CPI) rose 0.8% month over month and 4.2% year over year, well above expectations.
Core CPI, which strips out volatile food and energy, rose 0.9% month over month, its highest reading since the early 1980s, and 3.0% year over year, again well above what economists thought. As a result, stocks had one of their worst days in months over fears higher inflation could mean the Fed will be forced to hike rates sooner.
The market took notice, pushing the market-implied five-year breakeven inflation rate—the difference between five-year Treasury and five-year TIPS yields—up to a 13-year high. When there is a wide spread, market participants are expecting higher inflation. Meanwhile, various industrial metals, which are linked to higher inflation, are trading at 52-week—or even all-time highs. Copper, for instance, made a new all-time high last week and is also signaling higher inflation ahead.
Here are some reasons we expect inflation to be transitory:
• The root cause. The reopening is happening, supply chain issues are making it harder to get goods, some jobs are hard to fill, and massive stimulus has created high savings levels, all of which have caused price pressures to build. But once the reopening has taken place and these bottlenecks have cleared, we would expect inflation readings to come back down. The Fed agrees, having said for months that any higher inflation numbers will be transitory, which means things should go back to normal once we get past the shock of reopening.
• Easy comparisons. In the midst of the pandemic last spring, CPI was negative three consecutive months in a row and April saw one of the largest drops ever. Now with the economy improving, comparisons from those dark days are extremely easy, likely distorting the yearly inflation numbers.
• Recovery plays accounted for most of the jump. Used car and truck prices jumped a record 10%, lodging climbed 7.6%, airfare 10.2%, car rentals 16.2%, and sporting events 10.1%. All of these are heavily impacted by the reopening process and accounted for nearly all of the jump. As these prices get back to normal, we expect inflation to calm down. How many more cars can people buy? And, of course sporting events were cheaper a year ago when no one was going to them. Meanwhile, other major components of CPI, like rents (0.2%), showed much more modest increases.
• Bigger forces still in play. Yes, near-term inflation has spiked, but in the longer-term a 1970s-style scare is extremely unlikely. Technology, globalization, the Amazon effect, increased productivity and efficiency, automation, and high debt (which puts downward pressure on inflation) are among the major structural forces that have put a lid on inflation the past decade plus—and will likely continue to do so.
Conclusion
The economy continues to strengthen and, so far, this year is off to a better start than even the most bullish economist could have expected. There are always risks though, including COVID-19 spread outside the U.S., deficit spending, geopolitics, inflation, tax increases, and a potential policy mistake. Not to mention after a record 89% rally for the S&P 500, a well-deserved break or consolidation during a historically weak time seasonally would be perfectly normal.
But, amid a backdrop of an improving economy, massive levels of fiscal and monetary stimulus, and rising vaccination rates, we don’t expect any pullbacks to last very long, and we’d use any that appear as a buying opportunity.
We upgraded our forecast for the global economy and U.S. corporate earnings in April, and last week upgraded our 2021 year-end S&P 500 fair-value target range to 4,400-4,450. We continue to recommend an overweight to equities and underweight to fixed-income position relative to investors’ targets, as appropriate.
Ryan Detrick is chief market strategist for LPL Financial


Connecticut Regulators Fine Company, Producer For Improper Plan Sales
Indexed Life Sales Back On The Uptick In 4Q
Advisor News
- The inheritance gap: Helping clients plan for money that hasn’t arrived
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
More Advisor NewsAnnuity News
- Annuity sales hit record $126.3B as RILA sales top $25B
- More pre-retirees rethink retirement as income-planning concerns grow
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
More Annuity NewsHealth/Employee Benefits News
- Study Results from Hospital of the University of Pennsylvania in the Area of Managed Care Reported (Ten-year Performance of the Multi-Layer Insulated Defibrillation Lead in the Medicare Population): Managed Care
- Insurance cost hikes, fewer Medicare options add to Wyomingites' healthcare struggles
- Insurance Barriers to Mental Health Care Are Breaking Down
- States push short-term insurance as healthcare costs climb
- UnitedHealthcare calls Fairview lawsuit ‘mudslinging,’ asks judge to dismiss it
More Health/Employee Benefits NewsLife Insurance News
- Samsung Fire & Marine Insurance to Acquire Outstanding Stake in Canopius with KKR and KIC
- Start estate planning before the family needs it
- Best’s Market Segment Report: Health and Property Lines of Business Drive Hong Kong’s Non-Life Insurance Growth
- AM Best Affirms Credit Ratings of Central States Indemnity Co. of Omaha and Its Subsidiary
- National Life Group Approves $23 Million Dividends for 2027
More Life Insurance News