

Raising the 10-year Treasury yield year-end forecast
By Lawrence Gillum
The LPL Research Strategic and Tactical Asset Allocation Committee (STAAC) uses a number of quantitative models to help inform investment decisions.
For interest rate forecasts specifically, we utilize a range of econometric models that take into consideration economic growth and inflation expectations, foreign interest in U.S. Treasury markets, equity volatility and Federal Reserve (Fed) terminal rates, to name just a few of the factors.
Because of the recent release of the Fed’s “dot plot”, however, we’ve increased our expectation of where the fed funds rate will end the year. Add to that still elevated inflationary pressures and presumably less interest by foreign investors in U.S. Treasury markets going forward, and we think the 10-year Treasury yield can end the year between 3.25% and 3.75%, up from our previous year end forecast range of 2.75% to 3.25%.
Moreover, with this new range, we think the risks to both the upside and downside are more balanced. The increased yield target is in concert with our recent decision to increase our recommended interest rate exposure in tactical allocations from underweight to neutral.
As seen in the LPL Chart of the Day, the yield on the 10-year Treasury yield was up over 3.4% from its August 2020 lows and has already seen the biggest move higher in yields since 1983-84, when rates moved higher by 3.8%. Since the 1980s, the average trough-to-peak increase in 10-year Treasury yields has been closer to 2.5%, but that includes large rate increases in early 1980s when Treasury yields were much higher.

Since 2000, the average increase in the 10-year yield during major moves higher is around 1.8%. Clearly, we’re not in normal times but the move on the 10-year Treasury yield since it bottomed in August 2020 has been significant.
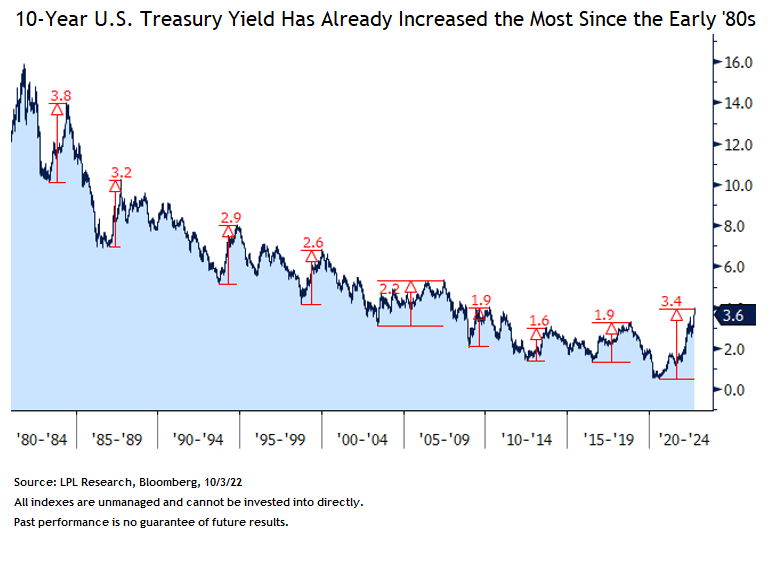
The significant increase in yields, especially this year, is because of changing Fed rate hike expectations. Late in 2021, markets expected the Fed to largely stay on the sidelines and keep short-term interest rates low. However, as inflationary pressures remained (and still remain), the Fed has embarked on a historically aggressive rate hiking campaign.
Because of the Fed’s stated desire to front-load rate hikes, the current rate hiking cycle is the most aggressive campaign since the early 1980s in both the speed and magnitude of rate hikes. The Fed has signaled that more interest rate hikes will likely be necessary to arrest the generationally high consumer price increases we’re currently experiencing.
Markets have already priced in what we think is an appropriate terminal Fed Funds rate. As such, we think we may be at or near peak “hawkishness” from the Fed, which should allow fixed income yields to stabilize at or near current levels.
Lawrence Gillum is a fixed income strategist for LPL Financial


Mass. ballot initiative may represent start of nationwide dental insurance reform
Mythbusters: the impact investing edition
Annuity News
- Annuity sales hit record $126.3B as RILA sales top $25B
- More pre-retirees rethink retirement as income-planning concerns grow
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
More Annuity NewsHealth/Employee Benefits News
- Study Results from Hospital of the University of Pennsylvania in the Area of Managed Care Reported (Ten-year Performance of the Multi-Layer Insulated Defibrillation Lead in the Medicare Population): Managed Care
- Insurance cost hikes, fewer Medicare options add to Wyomingites' healthcare struggles
- Insurance Barriers to Mental Health Care Are Breaking Down
- States push short-term insurance as healthcare costs climb
- UnitedHealthcare calls Fairview lawsuit ‘mudslinging,’ asks judge to dismiss it
More Health/Employee Benefits NewsLife Insurance News
- Samsung Fire & Marine Insurance to Acquire Outstanding Stake in Canopius with KKR and KIC
- Start estate planning before the family needs it
- Best’s Market Segment Report: Health and Property Lines of Business Drive Hong Kong’s Non-Life Insurance Growth
- AM Best Affirms Credit Ratings of Central States Indemnity Co. of Omaha and Its Subsidiary
- National Life Group Approves $23 Million Dividends for 2027
More Life Insurance NewsProperty and Casualty News
- Samsung Fire & Marine Insurance to Acquire Outstanding Stake in Canopius with KKR and KIC
- AM Best upgrades Nationwide P&C outlook to positive
- Weathering business interruption coverage in a super El Niño
- Mark Gongloff: Why home insurance costs more than property taxes
- AM Best Affirms Credit Ratings of Mercantil Seguros y Reaseguros, S.A.
More Property and Casualty News