

A More Balanced Approach to Comparing Policy Illustrations
Factoring in non-guaranteed elements adds objectivity
Life insurance illustrations are designed to provide clients some perspective on how their policy may perform over time, based on unchanging assumptions. However, assumptions are inherently variable. Let’s take a look at indexed universal life insurance policies and some of the factors involved, including how you might level the playing field.
THE ART OF THE ILLUSTRATION
Since interest crediting is a selling point and a concept most clients understand, it’s commonly used as a way to compare carriers and as a differentiator on illustrations. We run illustrations using assumptions based on the current environment. However, assessments of the environment and appropriate assumptions are open to interpretation.
In reality, no one knows what the future holds. Crediting rates are not guaranteed and will vary unpredictably over the long term. But interest crediting is not the only non-guaranteed element of a policy. Policy fees and charges can also vary. In fact, several carriers have recently taken to raising non-guaranteed charges on in-force blocks. You just don’t know how long current charges will apply or how often they will change. What we do know are the charges today and maximum charges allowed by the policy.
As a result of these factors, illustrations are required to contain various scenarios to help paint the picture. Every illustration shows policy performance based on:
- Interest rate assumptions and current charges
- An alternate scenario of level fixed account crediting with current charges
- Mid-point values between current and guaranteed charges and credits
- Guaranteed minimum crediting and maximum charges
Clients need you — their agent — to help interpret it all and compare their options. With interest crediting volatility and charges that are not locked in, how can you be sure you are comparing apples to apples?
A MORE BALANCED APPROACH
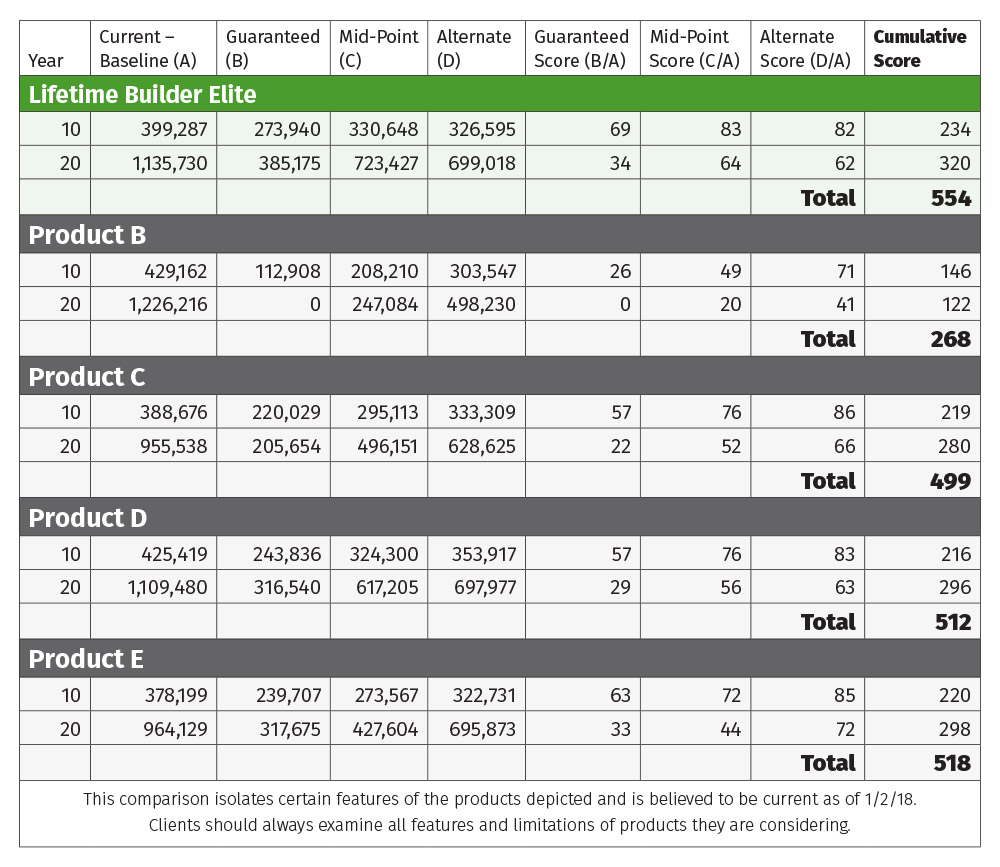
Comparing cash surrender values over time to current account values could be a tool to help level the playing field and provide a more objective comparison of products, given the nature of non-guaranteed elements. To devise a scale and formula:
- Assume a cash surrender value that equals the current ledger’s account value earns a score of 100.
- If the surrender value is half that of the account value, it earns a score of 50, and so on.
- Using a weighted average at both 10- and 20-year durations, available in illustrations, add scores for guaranteed, alternate and mid-point scenarios.
- Combine the cumulative results of the two durations for a total score for comparison.
Take a look at the accompanying table to see how it looks using different products on the market today, starting with Global Atlantic’s Lifetime Builder Elite. The higher the score, the less susceptible cash surrender values will be to changes in non-guaranteed assumptions.
 Next time you’re presenting an IUL product to a client, try this little experiment for a more balanced approach to comparing policies. For more information please visit www.GlobalAtlanticLife.com.
Tom Doruska, FSA, MAAA, is Senior Vice President, Life Products, at Global Atlantic, and Chair of the ACLI IUL task force.


The Future of Underwriting in the Palm of Your Hand
5 important steps a client should take following an auto accident
Advisor News
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
- How advisors can help frugal retirees finally enjoy their savings
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- The percentage of people without health insurance is growing
- Health agents victorious against CMS moratorium
- US Department of Justice Intervenes in Health Insurance Whistleblower Lawsuit Brought by Lieff Cabraser Against Centene Corporation
- The caregiving generation doesn’t want to repeat their parents’ mistakes
- Lawmakers warming to discussing long-term care
More Health/Employee Benefits NewsLife Insurance News
- Prudential earnings dip as Japan sales suspension offsets U.S. growth
- U-Haul Holding Company Reports Second Quarter Fiscal 2027 Financial Results
- Genworth Financial Announces Third Quarter 2026 Results
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Why the market doesn’t need more carriers
More Life Insurance News