

CoreLogic US Housing Credit Index Shows a Decrease in Mortgage Credit Risk
—In Q4 2016 Access to Mortgage Credit Remained Tighter Than One Year Ago—
This Smart News Release features multimedia. View the full release here: http://www.businesswire.com/news/home/20170321005173/en/
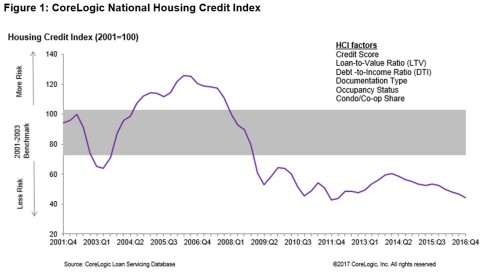
Figure 1: CoreLogic National Housing Credit Index Q4 2016 (Graphic: Business Wire)
The current HCI shows mortgage loans originated in Q4 2016 continued to exhibit low credit risk consistent with the previous quarter and tighter than in Q4 2015. In terms of credit risk, Q4 2016 loans are among the highest-quality home loans originated since 2001.

“Mortgage loans closed during the final three months of 2016 had characteristics that contribute to relatively low levels of default risk,” said Dr.
Nothaft observed that mortgage rates have moved higher since November and are anticipated to rise even further during 2017. “Refinance volume will decline with higher mortgage rates, and lenders generally will respond by applying the flexibility in underwriting guidelines to make loans to harder-to-qualify borrowers. As this occurs, we should observe our index signaling a gradual increase in default risk. The evolution to a more purchase-dominated lending mix is also likely to increase fraud risk.”
HCI Highlights as of Q4 2016 (Figures 2-3):
- Credit Score: The average credit score for homebuyers increased 4 points year over year between Q4 2015 and Q4 2016, rising from 733 to 737. In Q4 2016, the share of homebuyers with credit scores under 640 was about one-tenth of those in 2001.
- Debt-to-Income: The average DTI for homebuyers in Q4 2016 was similar to Q4 2015, remaining at 36 percent. In Q4 2016, the share of homebuyers with DTIs greater than or equal to 43 percent had increased slightly compared with 2001.
- Loan-to-Value: The LTV for homebuyers increased by less than 1 percentage point year over year between Q4 2015 and Q4 2016, rising from 86.7 percent to 87.1 percent. In Q4 2016, the share of homebuyers with an LTV greater than or equal to 95 percent had increased by more than one-fourth compared with 2001.
Figures 1 through 3 include originations through
For ongoing housing trends and data, visit the CoreLogic Insights Blog: http://www.corelogic.com/blog.
Methodology
The CoreLogic Housing Credit Index (HCI) measures the variation in mortgage credit risk attributes and uses loan attributes from mortgage loan servicing data that are combined in a principal component analysis (PCA) model. PCA can be used to reduce a complex data set (e.g., mortgage loan characteristics) to a lower dimension to reveal properties that underlie the data set.
The HCI combines six mortgage credit risk attributes, including borrower credit score, loan-to-value (LTV) ratio, debt-to-income (DTI) ratio, documentation level (full documentation of a borrower’s economic conditions or incomplete levels of documentation, including no documentation), occupancy (owner-occupied primary residence, second home, or non-owner-occupied investment), and property type (whether property is a condominium or co-op). It spans more than 15 years, covers all loan products in both the prime and subprime lending segments and includes all 50 states and the
Source:
The data provided are for use only by the primary recipient or the primary recipient's publication or broadcast. These data may not be re-sold, republished or licensed to any other source, including publications and sources owned by the primary recipient's parent company without prior written permission from
About
View source version on businesswire.com: http://www.businesswire.com/news/home/20170321005173/en/
For real estate industry and trade media:
bill@campbelllewis.com
or
For general news media:
lguyton@cvic.com
Source:


Auto Insurance Discounts Are Useful for Saving Money
Emails to Emanuel raise questions about dozens of possible lobbying violations
Advisor News
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
- How advisors can help frugal retirees finally enjoy their savings
- Wealth planning vs. estate planning: Honoring your client’s wishes
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- Democrat Annie Andrews Wins South Carolina Senate Seat in a Stunning Upset
- Researchers from Federal Reserve Bank of Philadelphia Report New Studies and Findings in the Area of Managed Care (Missouri’s Medicaid Contraction and Consumer Financial Outcomes): Managed Care
- Research Results from University of Maryland Update Knowledge of Heart Failure (Alcohol screening, counseling, and medication treatment among older adults with heart failure: A missed opportunity): Heart Disorders and Diseases – Heart Failure
- Take 5: What You Need to Know About Open Enrollment and the Affordable Care Act
- As WA open enrollment begins, far fewer than expected have lost coverage
More Health/Employee Benefits NewsLife Insurance News
- U-Haul Holding Company Reports Second Quarter Fiscal 2027 Financial Results
- Genworth Financial Announces Third Quarter 2026 Results
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Why the market doesn’t need more carriers
- Unum Group Reports Third Quarter 2026 Results
More Life Insurance News