

The rise of deductible insurance
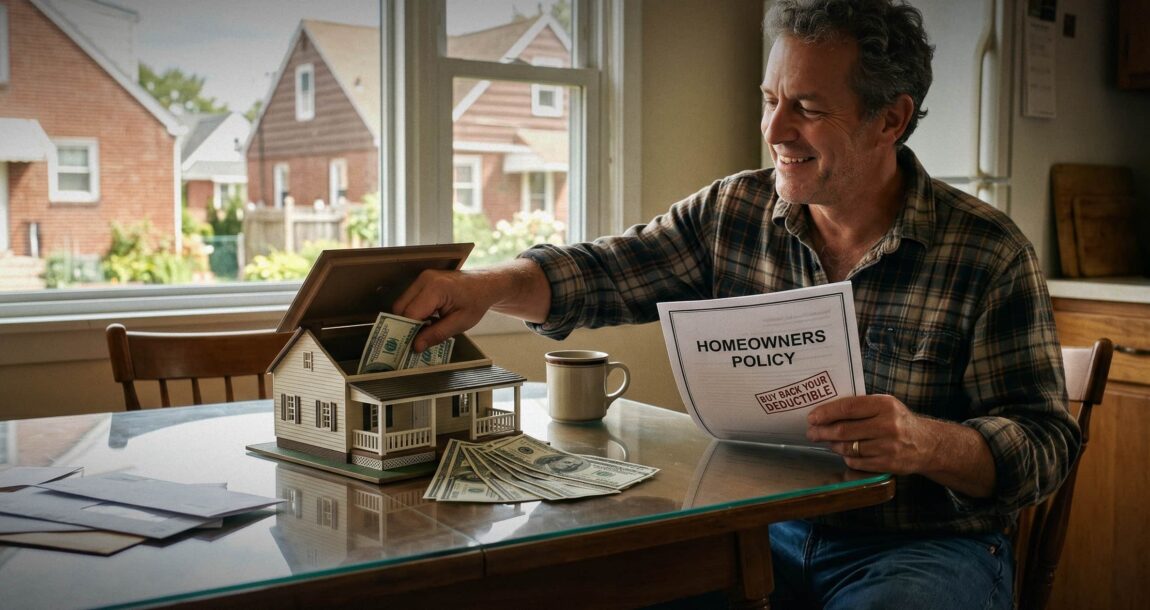
Insurance premiums have surged, with homeowners seeing their premiums increase by an average of 24% over the past three years. But rising premiums are only part of the story. Deductibles in homeowners insurance are also rising. Average deductibles increased by more than 20% in 2025 alone, marking the second consecutive year of double-digit increases. Climate volatility is intensifying, reinsurance costs remain high, and carriers are refining their risk models. These factors make high deductibles a primary target for maintaining profitability.
Insurance is not only becoming more expensive, but it is also becoming harder to access when it matters most. It’s also worth noting that while most of the conversation focuses on homeowners, the same structural pressures are increasingly affecting commercial property owners as well.
The hidden consequences of high deductibles
When deductibles reach a certain threshold, many homeowners simply stop using their insurance. Instead of filing claims, they delay repairs or patch over damage. A cracked exterior might get a coat of paint. A leaking roof might be temporarily sealed rather than replaced.
In the short term, this avoids the cost of a claim. Over time, it leads to more severe damage, higher repair costs and properties that deteriorate faster than they should.
The impact extends beyond individual homeowners. Poorly maintained properties become harder to insure and can affect surrounding property values. Insurers, in turn, face larger losses when deferred damage eventually results in more severe claims. The system begins to work against itself.
Mortgage lenders are also exposed. If a homeowner cannot afford to repair storm damage because their deductible is too high, the underlying value of the property declines. A $400,000 home that remains unrepaired after a major loss is likely no longer a $400,000 asset.

As a result, high deductibles are no longer just a pricing mechanism. They are emerging as a structural risk within the insurance ecosystem. This dynamic creates a growing gap between what insurance promises and what policyholders can realistically access. That gap is now large enough to support an expanding category of solutions.
Deductible buyback isn’t new
The insurance industry has a long history of evolving to address structural gaps. Umbrella policies, excess liability coverage and gap insurance in auto all emerged to solve mismatches between what primary coverage provides and what policyholders actually need.
Deductible buyback follows the same logic. At its core, a deductible buyback is a supplemental policy designed to cover the insured’s financial exposure within a primary policy’s deductible. It allows homeowners to insure the portion of a loss they would otherwise have to pay out of pocket, effectively restoring the usability of their primary insurance.
Importantly, this is not a new concept. Deductible buyback products have existed for years, but saw limited adoption when deductibles were relatively stable and manageable. What has changed is the scale of the problem. As deductibles rise sharply, the need for this type of coverage has become far more immediate.
Unlike parametric insurance products, which rely on predefined triggers such as wind speed or rainfall, deductible buyback coverage is usually tied directly to the underlying insurance policy. It activates only when a loss is approved under the primary policy and applies specifically to the deductible portion of that claim.
If a claim is not covered by the primary policy, the buyback does not apply. This makes it a complementary layer of protection rather than a stand-alone product.
This distinction is critical. The value of deductible buyback is not speed of payout based on external triggers, but alignment with the actual coverage homeowners already have in place. It ensures that when a covered loss occurs, the policyholder can access their insurance without facing a prohibitive upfront cost.
Making coverage work again
The fundamental purpose of insurance is to provide financial resilience in the face of loss. That purpose breaks down when the cost of accessing coverage becomes a barrier in itself.
What is happening today is not just a pricing shift, but a usability problem. Homeowners are paying for coverage that, in many cases, they cannot afford to use.
The good news is that the industry is well-positioned to address this gap. The rise of deductible buyback products reflects a broader recognition that coverage must function in real-world conditions, not only on paper.
The next major insurance innovation will not replace existing policies, but will make them work as intended. By closing the gap created by rising deductibles, these solutions have the potential to restore trust in a system that is increasingly under strain.
This is one of the most significant and under-addressed challenges in the U.S. property insurance market today. Solving it will define the next phase of industry innovation.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Prudential extends Japan sales ban another 6 months at a total $1B loss
Life insurance tips: 5 underwriting concerns for clients living abroad
Advisor News
- How advisors can help frugal retirees finally enjoy their savings
- Wealth planning vs. estate planning: Honoring your client’s wishes
- What to discuss during the first retirement planning meeting
- Inflation, competing priorities and uncertainty erode retirement security
- As health premiums rise, 1 in 8 workers cut retirement savings
More Advisor NewsAnnuity News
- Jackson Announces New Annuity Offering for AARP Members
- National Life Group expands annuity portfolio
- AM Best to Join Life/Annuity Insurance-Focused Panel Discussion at Capitol Forum Event
- USAA Earns No. 1 Ranking in JD Power Individual Annuity Study for the Third Consecutive Year
- How flexible annuities fit today’s retirement portfolios
More Annuity NewsHealth/Employee Benefits News
- Anthem Blue Cross and Blue Shield Announces Agreement with Brokers Holding Group to Expand Reach in Georgia’s Small and Mid-Markets
- New Findings from Bar Ilan University Describe Advances in Mental Health Diseases and Conditions (Did Nationwide Mental Health Insurance Reform In Israel Increase Access To Community-based Care? a Population-based Retrospective Cohort Study): Mental Health Diseases and Conditions
- The closing argument for Republicans
- NYC public hospitals brace for coverage crisis as federal Medicaid work requirements loom
- MDHS announces open enrollment assistance for eligible families through SHIP
More Health/Employee Benefits NewsLife Insurance News
- Corebridge Financial Announces Third Quarter 2026 Results
- MassMutual announces record $3.3 billion policyowner dividend for 2027
- Protective Completes Acquisition of Obsidian, Establishing Specialty Property and Casualty Business Line
- Jackson Announces New Annuity Offering for AARP Members
- Open Enrollment Starts November 1: Tampa Broker Ryan Michalek Urges Families and the Self-Employed to Check 2027 Costs Before They Auto-Renew
More Life Insurance News