

Regulators urged to sharply limit hypothetical data in annuity illustrations
A National Association of Insurance Commissioners working group is closing in on changes that would limit the use of historical investment returns in annuity illustrations.
The Life Insurance and Annuities Illustrations Working Group held its fifth weekly call – one more than initially scheduled – Tuesday as members completed an intense review of the model law governing annuity illustrations.
Regulators undertook the time-consuming effort after a checkup on the industry found some annuity products illustrating as high as 27%.
On Tuesday, the group discussed ways to provide consumers with more consistent ways to see how indexed products could perform.
Longtime consumer advocate Birny Birnbaum, executive director of the Center for Economic Justice, spoke at length and told regulators that responsible illustrations cannot include hypothetical scenarios.
“Companies cherry-pick returns from the past in order to show even the worst-case scenario is going to give you a phenomenal return,” Birnbaum said. “If you continue to allow insurance companies to do hypothetical scenarios, then you will continue to allow insurance companies to game the illustrations.”

A choice of options
The working group wrapped up its review with debate on “additional scenarios and supplemental information.” Working group chairman Ben Slutsker, director of life actuarial valuation at the Minnesota Department of Commerce, gave members four options to discuss:
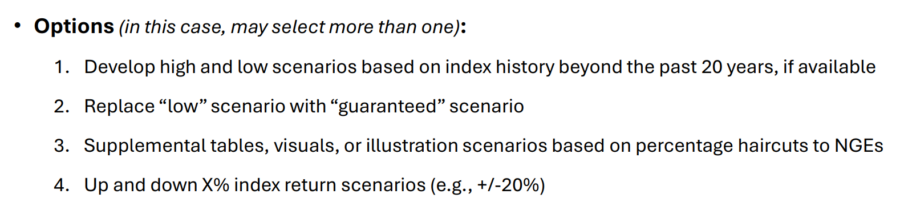
The group expressed little support for extending the historical period used to generate high- and low-return scenarios. But options two through four are workable, members agreed, with some tweaks to option three.
Regulators and consumer representatives generally favored prescribed scenarios based on fixed index returns.
Bill Carmello is chief life actuary for the New York State Department of Financial Services. He supported using scenarios similar to the approach taken by the Securities and Exchange Commission for variable products, with fixed levels of stock-market returns rather than projections based on historical index performance.
The working group ultimately agreed to include prescribed up-and-down index scenarios in the next exposure of proposed changes.
Show the actual performance
Oregon regulator Joshua Blakely also supported fixed return scenarios, saying they would move illustrations toward education about how products work rather than projected future performance.
“We see index facts sheets pretty regularly that do call out performance historically of indexes," Blakely noted. "Is there a reason that all the stuff needs to be included in the illustration, or could those be supplemental documents the insurers provide to show that history for context?"
Blakely suggested calling the additional information "alternate" rather than "supplemental" scenarios and said fixed scenarios could provide greater uniformity among illustrations.
Consumer representatives emphasized that any changes should make illustrations easier to understand rather than simply adding more information.
Bonnie Burns of California Health Advocates said uniformity would help consumers compare products but cautioned against sacrificing disclosures and explanations in an effort to shorten illustrations.
"In addition to the illustration itself and the number of pages involved, if there are supplemental pieces of information, that tends to start really obscuring the reason that people are buying these and what that product is actually doing," Burns said.
Guaranteed vs nonguaranteed elements
Carmelo and Michigan regulator Danielle Torres supported giving consumers information about what is guaranteed as well as what might be possible under a specified market return.
But Birnbaum argued that even guaranteed scenarios can be misleading if insurers have discretion to change certain product charges. He pointed to insurers' ability to change caps, floors, expenses and other nonguaranteed elements as factors that can alter product performance over time.
Birnbaum pointed out how illustrations have historically influenced the product design of indexed universal life, with insurers tweaking IUL products after every rules change designed to keep illustrations in check.
His preferred approach would show consumers the mechanics of a product during a particular crediting period rather than projecting results decades into the future.
Under that approach, an illustration for a two-year crediting period, for example, could demonstrate how the product would operate under specified market conditions during that period.
"There should be no scenario going forward other than explaining and demonstrating how the product operates during a particular crediting period," Birnbaum said.
Birnbaum also urged the NAIC to conduct consumer testing before adopting a redesigned illustration.
"I would submit to you that it is impossible for you to understand how a consumer who's new to a product will react to this information," he said. "And I don't say that as a criticism."
Working group pause
The working group plans to issue an exposure seeking specific proposals rather than broad conceptual comments.
The proposed format will call for a concise, roughly one-page description of the proposed change followed by a mockup of the resulting illustration, visual example or other details showing how the proposal would work.
The working group plans to pause its calls while interested parties develop specific proposals. The next discussion is expected in roughly two to three months, Slutsker said, after a nearly two-month submission period.
The goal, Slutsker explained, is to move from broad discussions about what illustrations should contain to concrete proposals showing regulators and consumers what the revised illustrations would actually look like.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Your client wants to cash out an annuity. Here’s what to consider
Agent groups speaking out against possible moratorium on new ACA brokers
Advisor News
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- Boeing retirees ‘shocked’ by 400% jump in health insurance premiums
- MEDICAID PAYMENT TRANSPARENCY RULES: STATE REPORTING REQUIREMENTS AND LIMITATIONS
- Medicare open enrollment continues through Dec. 7
- Pike County facing year-end employee healthcare lapse
- Investigators at University of Pennsylvania Report New Data on Managed Care (In-hospital Medicaid enrollment facilitates follow-up care for emergency general surgery patients): Managed Care
More Health/Employee Benefits NewsLife Insurance News
- AM Best Affirms Credit Ratings of Central States Indemnity Co. of Omaha and Its Subsidiary
- National Life Group Approves $23 Million Dividends for 2027
- Milliman’s proposed $15.5 million settlement puts life insurance underwriting data in focus
- Brighthouse Financial Announces Third Quarter 2026 Results
- Prudential earnings dip as Japan sales suspension offsets U.S. growth
More Life Insurance News