

Partial annuitization: How advisors can help clients balance income, growth
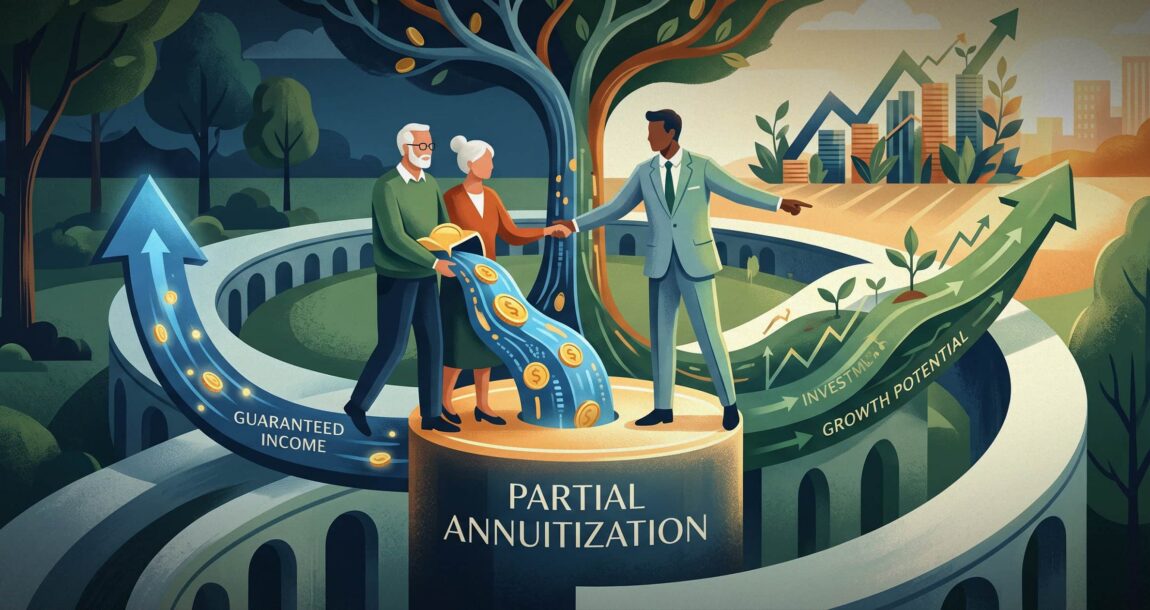
In recent years, we’ve seen greater market volatility, higher inflation, uncertainty about the future of Social Security, and longer life expectancies. These concerns are changing the conversation many people are having about how to allocate their nest egg.
“More retirees are warming up to the idea of partial annuitization to assure a guaranteed lifetime income stream,” said Angie Welsh, founder and president of My Annuity Agents.
Allocating a portion of their nest egg to guaranteed income means they can focus on growth for the rest of their portfolio without the anxiety that comes with potential market downturns.
That being said, advisors should understand that annuities aren’t an all-or-nothing decision.
“Partial annuitization allows guaranteed income to complement existing sources of retirement income while keeping the remainder of a portfolio available for growth, liquidity and legacy goals,” explained Tom Buckingham, chief growth officer at Nassau Financial Group.
Finding the right balance
Every client scenario is different, so there’s no magic formula to determine what percentage of someone’s portfolio should be annuitized versus invested for growth and liquidity.

It all depends on their income needs, their risk tolerance, and the size of their nest egg. However, the best rule of thumb is to start conservatively.
“Once funds are annuitized, there is no going back,” Welsh explained.
Start with the absolute minimum income requirements. Remember that additional lifetime income annuities can always be added in the future.
Chris Walsh, senior advisor and regional director at Capital Choice Arizona, agrees and tries to solve each client’s need first.
“I want to understand what their absolute bottom need for retirement is going to be,” Walsh explained.
He calculates each client’s Social Security benefit, their pension, and what their projected annuity payment would be, so even in a down market, they can still hit their needs for retirement.
“We keep some cash on the side for emergencies, generally six months to two years depending on the individual, then the rest is in equities to grow with the market for their wants in retirement and legacy planning,” Walsh said.
For example, let’s say a client wants to retire with $7,000 a month, but their need is $5,000 a month, and Social Security at 67 is $2,000 a month.
“We need a pension or annuity source of $3,000, and we're projecting they'll have $1.5 million at 67,” Walsh explained.
Closing that gap with an immediate annuity at recent payout rates runs roughly a third of the portfolio. Run it instead as a deferred annuity purchased at age 60 with income starting at 67, assuming a 9% average rate of return along the way, and that $1.5 million backtracks to roughly $820,000 at 60.
The same $3,000 a month costs closer to half of the smaller portfolio. Payout rates depend on the carrier and the contract.
Ideal candidates for partial annuitization
Good candidates for annuitization lack a pension, can’t rely solely on Social Security, and don't have a portfolio that can sustain withdrawals during a prolonged market downturn.
“It’s also a good option for those who do not have or are not concerned with their beneficiaries, have strong longevity genes, or anyone with a very low tolerance for risk,” Welsh said.
Walsh explained that one of the first questions he asks a client is when they want to retire.
He joked that practically every client will tell him today would be their desired retirement. Therefore, he asks them what's stopping them from retiring today, and they let him know they need their paycheck.
“Then I'll ask, ‘If you had your paycheck today, 100% of it, for the rest of your life, would you retire?’ The answer typically is yes, I could live comfortably off of that,” Walsh said.
Next, he asks, “If you had consistent, reliable income you can count on, that would give you the confidence to retire, wouldn't it? That's where partial annuitization makes a lot of sense for people.
It’s important to note that while parietal annuitization is a smart choice for some individuals, it’s not right for everyone.
“I don’t recommend it to those poor longevity genes or nest eggs that are sufficient to provide income by using interest earned and keeping their principal intact,” Welsh added.
How advisors can position partial annuitization
Guaranteed income should be considered the foundation of a financial plan, not the entire house. It’s a small part of a larger portfolio. It should be used only to cover living essentials.
“This strategy allows clients to maintain their market accounts without drawing during market downturns,” Welsh said.
It also creates greater confidence because knowing essential expenses are covered with a lifetime income strategy increases peace of mind and improves quality of life.
When recommending partial annuitization to clients, advisors must also reinforce the fact that annuities are versatile.
Expose clients to other benefits, like long-term care riders. In some instances, those can increase monthly payments if a critical injury or illness prevents someone from doing two out of six activities of daily living.
Additionally, Walsh suggested asking a client if they’d be upset if the market paused or crashed a year or two before their retirement and they had to delay it an extra couple of years.
“I like using the deferred purchase as a way to de-risk their portfolio so they can at least retire when they want to,” Walsh added.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Guide women along the walk through widowhood
4 things every agent should know about succession planning
Advisor News
- CT governor’s candidates claims: What’s true, and what’s misleading
- Retaining clients by giving them a memorable experience
- Addressing the longevity paradox
- Employers shift focus from retirement access to financial outcomes
- Helping widowed clients navigate their new financial reality
More Advisor NewsAnnuity News
- Foresters Financial appoints Tom Ross as chief distribution officer for U.S. annuity sales
- Symetra and TIAA Announce Launch of Mariner Re
- Jackson Launches Suite of Fixed Index Annuities Focused on Accumulation
- Farm Bureau P&C insurers post first underwriting gain since 2021
- Legacy Marketing, Malibu Life launch two fixed indexed annuities
More Annuity NewsHealth/Employee Benefits News
- NC's State Health Plan taps retiree funds amid cash crisis, reaches deal with Atrium Health
- Study: Colorado’s Medicaid covers more services than private insurance
- Studies from Northwell Health Describe New Findings in Managed Care (The Relative Value Scale Update Committee: Understanding How Dermatologists’ Work Is Valued): Managed Care
- Hofstra University Details Findings in Managed Care (A University and Community Partnership to Address Diaper Insecurity Among Infants in Suburban Communities Through Home Visiting Services): Managed Care
- Reports Outline Managed Care Study Results from Brown University School of Public Health (Organizational Perspectives on Access to Care Among Persons With End-Stage Kidney Disease After Enrollment in Medicare Advantage): Managed Care
More Health/Employee Benefits NewsLife Insurance News