

Changing client priorities are reshaping annuity conversations
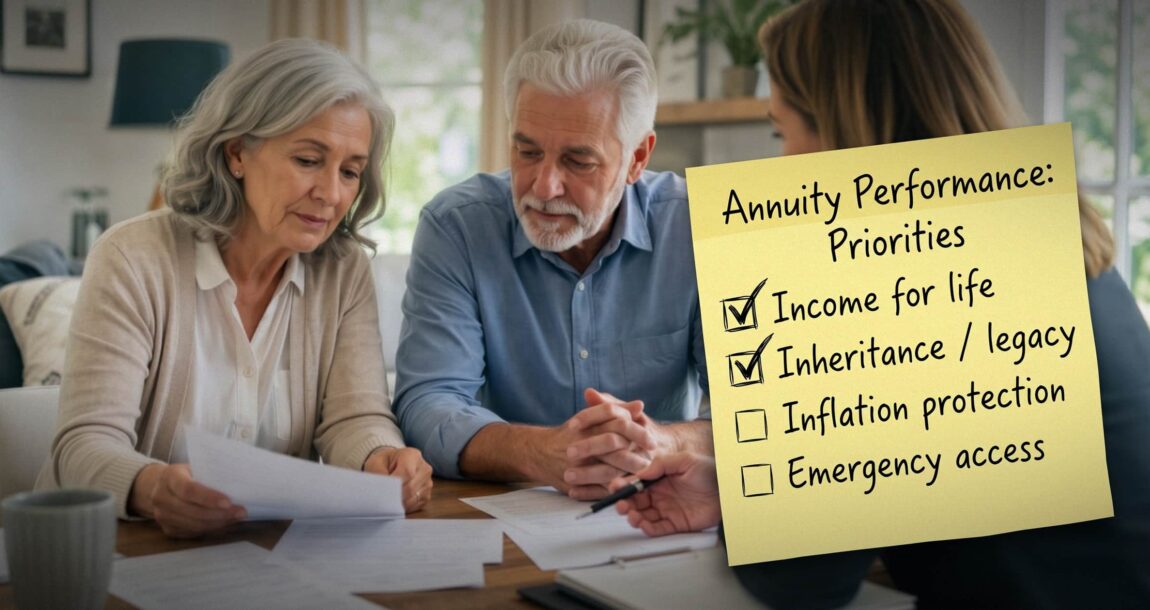
Guaranteed income used to be the primary selling point of annuities. According to a recent survey by LIMRA, however, today’s annuity buyer has different needs.
While guaranteed income remains important, principal protection, growth opportunities, retirement asset accumulation, and professional guidance are also top priorities.
“After experiencing significant market volatility over the past several years, many consumers are seeking solutions that can help them capture upside potential while providing a measure of downside protection,” said Jon Cressman, head of annuities distribution at Transamerica.
By recognizing this shift in their clients, advisors can have more meaningful conversations about how annuities fit into their broader financial plan.
Rather than focusing solely on guaranteed income, advisors can explore how different annuity options align with clients’ goals, from principal protection to growth potential.
Why principal protection and insurer strength matter
In the LIMRA survey, respondents placed significant weight on principal protection and insurer strength when evaluating annuities.

When you consider that retirement can last 20, 30, or even more years, this is no surprise. Clients are simply seeking the confidence that their savings will be there when they need them.
“People aren't just looking for growth. They're looking for stability, reliability, and confidence that their retirement strategy can stand the test of time,” Cressman explained.
Jason Caudill, founder of My Annuity Store, echoes Cressman’s thoughts.
“An annuity is a contract. The guarantee is only as strong as the company’s claims-paying ability. Buyers are smartly evaluating the promiser, not just the promise,” Caudill said.
For advisors, all of this underscores the importance of discussing long-term income needs, longevity risk, and the financial strength of the companies behind the solutions they recommend.
Balancing growth, protection, and retirement income
When discussing annuities with clients, advisors should clarify that growth and protection don't have to compete. The right approach starts with understanding what matters most to each client.
“Factors like retirement timeline, income needs, risk tolerance, and liquidity requirements all play an important role in determining the right mix,” Cressman said.
Fortunately, today’s annuity marketplace offers a range of solutions that can help clients pursue growth opportunities while maintaining a level of protection.
As advisors work with their clients to evaluate them, the most important question isn’t necessarily 'Which annuity has the highest return?' It's 'Which solution best supports the retirement outcome I'm trying to achieve?'
“The ability to construct a portfolio that meets the risk tolerance, growth objectives, and unique circumstances of each individual client is crucial to helping answer that question,” Cressman explained.
Regardless of which annuities advisors recommend, they should take the time to translate the contract.
“What does it actually do versus what the headline rate implies?" Caudill asked. "Surrender charges, withdrawal rules, fees, and insurer ratings often matter far more than a fraction of a percent on an advertised rate. A great rate on the wrong contract is a bad fit."
Ultimately, the role of annuities in a retirement plan is about the outcome. Many retirees worry about seeing their account values decline just as they're beginning to rely on those savings, and that can make the transition from accumulating assets to spending them more challenging.
“Annuities can help clients approach retirement spending with greater confidence and make the most of the savings they've worked decades to build,” Cressman added.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


SpecialtyCare sues Anthem over $2.5 million in unpaid awards
The 72-hour crisis many families face
Advisor News
- The 6X Formula for leveraging content marketing with AI
- When a home becomes difficult to insure, the plan changes
- The inheritance gap: Helping clients plan for money that hasn’t arrived
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
More Advisor NewsAnnuity News
- Regulators advance shorter, streamlined annuity buyers guide
- Annuity sales hit record $126.3B as RILA sales top $25B
- More pre-retirees rethink retirement as income-planning concerns grow
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
More Annuity NewsHealth/Employee Benefits News
- ACA premium increases in double digits for second year
- New Va. subsidies help lure people back to health insurance
- Oscar Launches New Wave of Consumer Health Insurance Products to South Carolina Individuals and Families
- STATE AUDITOR JAMES BROWN HELPS STOP ADDITIONAL $9.5M IN UNSUPPORTED PAYOUTS CONNECTED WITH OBAMACARE FRAUD SCHEME, BRINGING TOTAL SAVINGS TO $55.6M
- Will CVS corporate break-up impact Aetna’s Hartford campus? Not for ‘time being’
More Health/Employee Benefits NewsLife Insurance News
- New Jackson Study Finds the "Sandwich Generation" Squeeze Comes from More Than Two Sides and It’s Quietly Draining Retirement Savings
- Samsung Fire & Marine Insurance to Acquire Outstanding Stake in Canopius with KKR and KIC
- Start estate planning before the family needs it
- Best’s Market Segment Report: Health and Property Lines of Business Drive Hong Kong’s Non-Life Insurance Growth
- AM Best Affirms Credit Ratings of Central States Indemnity Co. of Omaha and Its Subsidiary
More Life Insurance News