

Canvas steps into the direct-to-consumer market that has yet to take off
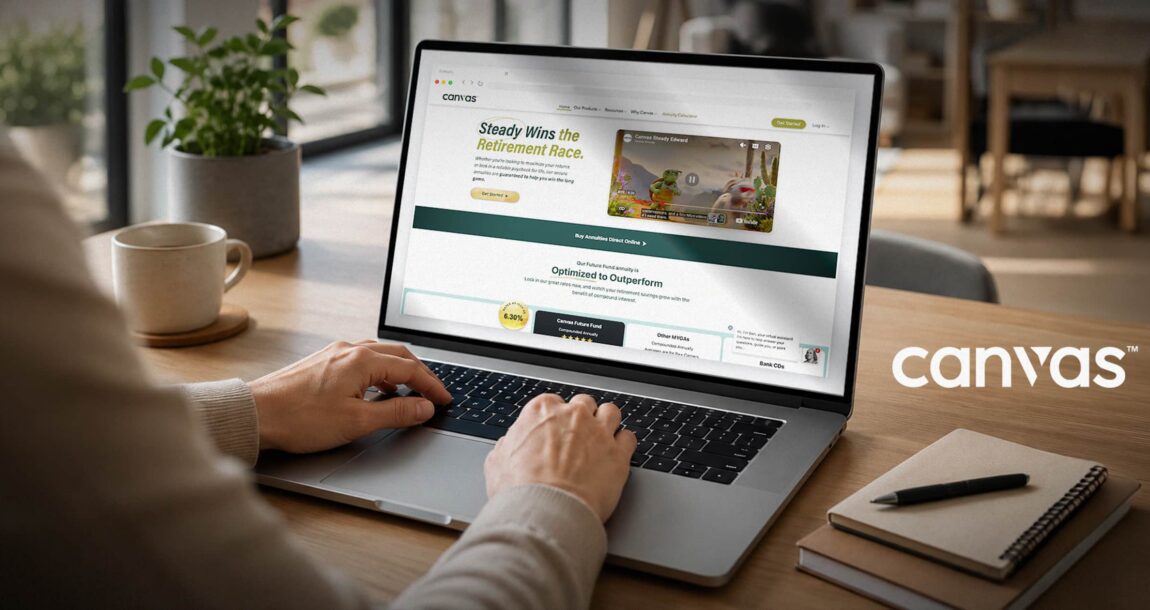
Recently, Canvas Annuity, a digital direct-to-consumer annuities provider, announced a new 10-year multi-year guaranteed annuity. This marks the company's first new term since its launch in 2020.
The product debuts with an initial 6.3% interest rate, which is guaranteed for the entire term.
“We launched the 10-year MYGA Future Fund to provide consumers who are currently planning for retirement with a full decade of guaranteed stability,” said Devon Askew, team lead at Canvas Annuity.
With inflation currently running at around 4%, the company sought to offer individuals a solution that can safely protect and actively grow their purchasing power.
“By locking in an interest rate of 6.3% for the entire ten-year term, we're helping people remove the guesswork from retirement planning while reducing reinvestment risk,” Askew explained.
The distribution problem
According to Askew, products like the 10-year MYGA Future Fund haven’t gained wider adoption due to distribution challenges, not customer demand.

Currently, Canvas sells two annuity products: a MYGA and a single premium immediate annuity (SPIA). Both are relatively straightforward for individuals to understand. A MYGA offers a fixed rate locked for a set term, while an SPIA provides lifetime income.
However, most annuities are sold these days through commissioned agents and fee-based broker-dealer channels. Their typical commission payment structure can reduce the rates the consumers actually receive.
“We compete against two types of players: traditional carriers that sell annuities primarily through commissioned agents and banks selling other savings products such as CDs,” Askew said.
While CDs can be useful for those needing shorter-term liquidity, MYGAs can usually beat the interest rate banks can offer with a CD while simultaneously providing tax-deferred growth.
“Since Canvas was built as a direct-to-consumer company from the start rather than retrofitted onto a commission-based sales model, we're able to pass the benefits directly to consumers in the form of higher crediting rates or increased lifetime income payments,” added Askew.
Who could benefit from these products
Generally speaking, products like the 10-year (MYGA) are ideal for individuals between 55 to 80.
“We’re seeing the demand for stable, low-risk retirement income options hit a historic peak with nearly the entire baby boomer generation reaching retirement,” Askew said.
However, that doesn’t mean others can’t reap its benefits.
Canvas is actively working to expand the market and reach demographics that have historically been left behind, including women, rural consumers, and first-time annuity buyers.
With a bit of education, experts say many of these groups could gain a better understanding of the role these products may have in their overall retirement plan.
Where advisors fit in
Canvas operates strictly as a direct-to-consumer platform, so most of its clients come to the company directly rather than through an advisor relationship.
However, they do sometimes receive referrals from advisors who are looking at a client's full financial picture.
“Even without a commission on the referral, if a client needs a portion of their portfolio allocated toward a guaranteed rate of growth with no market exposure, some advisors will steer them our way because it's the right fit for that piece of the plan,” Askew explained.
That being said, it’s important for advisors to familiarize themselves with these types of products as they may serve as one piece of a client’s broader retirement plan.
“There will always be plenty of room for more complex products where a financial professional's expertise and compensation come in,” Askew added.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Regulators: ‘No firm conclusions’ from first offshore reinsurance filings
Opinion: We must clear the insurance industry’s name
Advisor News
- Navigating client communication in a digital age
- Can your advisory firm survive without you?
- I started using AI, but what now?
- How to support an entrepreneur client with multiple businesses
- Could a narrower focus help grow your practice?
More Advisor NewsAnnuity News
- Solen Software Group Acquires Cooperative Technologies, Provider of 1035 Exchange and Annuity Replacement Software
- MassMutual Expands Lending Options With New Secured Credit Line
- Corebridge Financial Introduces Progressive Trigger, a First-of-Its-Kind Index Annuity Strategy Designed to Turn Missed Years into Future Opportunity
- Insurer proposes $1.1M deal to resolve CA teachers’ annuity fee lawsuit
- IMOs get frustrated with slow carrier adoption of faster technology
More Annuity NewsHealth/Employee Benefits News
- SpecialtyCare sues Anthem over $2.5 million in unpaid awards
- Americans Worry They Can’t Afford Health Care in Retirement, Allianz Life Study Finds
- Lawmakers urge USCIS to address immigration backlog affecting healthcare access
- Pennsylvania sues pharma and PBMs over insulin prices
- Seniors can get help wth Medicare sign-ups
More Health/Employee Benefits NewsLife Insurance News