

Annuity laddering strategies that should be in every advisor’s toolkit
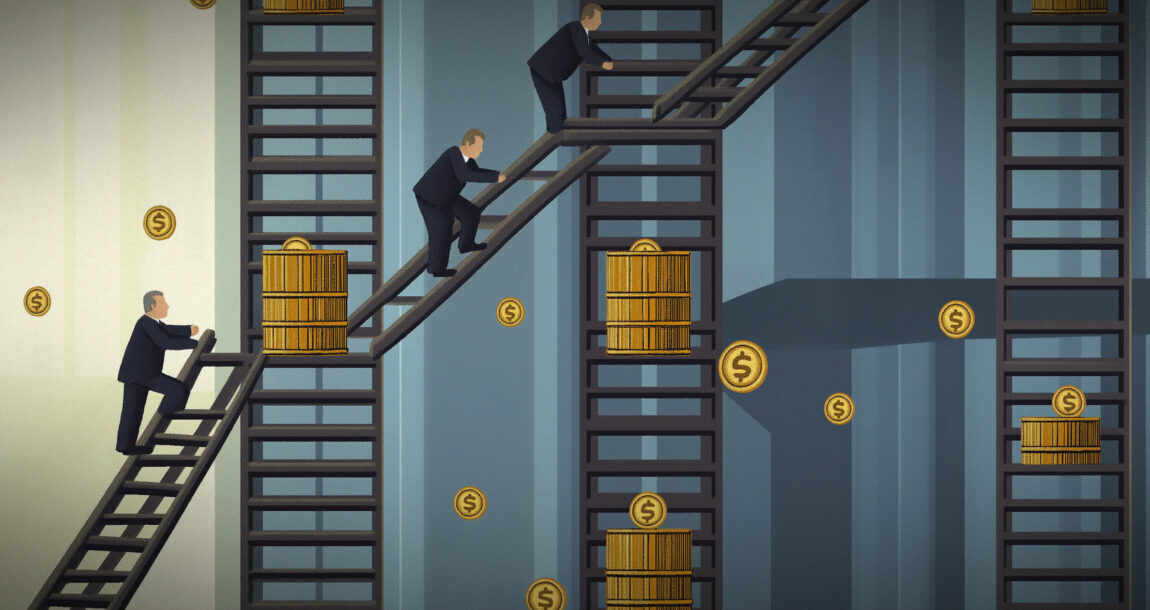
Retirement income planning can be an exciting journey, and annuity laddering is a simple concept that most agents can understand and share with ease. It's not a complicated idea at all — once it’s clearly understood, it can be put into action effectively!
I've seen agents either overuse it or water it down, both of which lead to confusion and missed opportunities. Laddering isn't new. It's borrowed from bond strategies — breaking up one significant investment into smaller, staggered parts.
But in retirement income planning, laddering isn't only spreading out maturities. It's about giving people income and flexibility, reducing reinvestment risk, and creating built-in checkpoints along their retirement journey.
Start with time, not yield
Every successful laddering strategy starts with your client's timeline, not the annuity's features. Help your clients map out three basic phases:
- Short-term needs.
- Mid-term stability.
- Long-term security.
From there, identify when each layer of income should begin and for how long it should last.
For example, suppose someone plans to retire at age 65 but wants to delay receiving Social Security until age 70. A multi-year guaranteed annuity can cover the early years post-retirement, while additional rungs are structured to initiate income at ages 70 and 75. This allows income to align with the client’s evolving needs.
Combat interest rate risk and avoid trying to time the market
Laddering provides our clients with protection from rate volatility. Most people don't want to gamble on whether annuity rates will be better next year. They want options now. By locking in some income immediately and leaving room for future purchases, laddering lets them "average in" over time.
Explain it like this: "If you commit everything today and rates rise, you're stuck. However, if you divide your purchases across multiple years or durations, you're better positioned to benefit from future rate increases.”
That's how laddering takes the pressure off trying to "time the top."
Match product to purpose
Here's where some of us go wrong: We use the same product across the entire ladder, which defeats the purpose. The goal is for each rung to serve a distinct role, not to duplicate the same annuity contract with different start dates.
Try this breakdown:
- 0-5 years: Fixed annuities or multi-year guaranteed annuities with guaranteed rates may be the best option here, as they provide the client with predictability without exposure to market fluctuations.
- 5-10 years: Leverage fixed indexed annuities during this phase, using credit strategies with downside protection and moderate upside potential.
- 10+ years: Continue with deferred annuities that allow for tax-deferred growth and eventual income activation.
Built-in liquidity and flex points with annuity laddering
Our clients rarely say they need access to all their money, but they often want to feel like they could. That's why it's smart to build ladders that leave room for flexibility. Sometimes, that means choosing shorter surrender schedules upfront or keeping a portion of assets liquid.
When potential health care costs are a concern, it may be wise to design the initial ladder rungs with greater liquidity and build in long-term growth through the later stages.
It's also essential to look for income flex points — built-in review moments where the client can decide to start taking income or defer again. This gives them control over their timeline and creates natural touchpoints to revisit their strategy.
Income raises that feel like pay raises
Clients sometimes describe staggered income activation as their "retirement raise plan." They see it as a helpful way to frame the psychological benefit of phased income increases.
One of the most underrated benefits of laddering is its ability to combat inflation without relying on COLA riders. When new rungs of the ladder kick in - such as at ages 70, 75 and 80 - those added income streams can act like pay raises precisely when clients need them.
This staged activation is especially helpful in hybrid retirement scenarios. In phased retirement scenarios, income can be gradually layered in to offset declining wages, providing a smoother transition into full retirement and alleviating income disruption for retirees.
Reinvestment risk? Minimized
Reinvestment risk is a genuine concern. A client locking into a five-year rate today has no idea where rates will be in 2030. By spreading maturity dates across multiple contracts, laddering gives clients reinvestment opportunities at different market points. Instead of hoping for a better rate later, they're positioned to capture one when it arrives.
This shift — from uncertainty to confidence — is often what makes laddering such an effective retirement planning strategy.
Keep annuity laddering visual and straightforward
It often helps to start the conversation with a broad conceptual overview before introducing product-specific details or numbers. Providing too much detail too soon can create confusion. Instead, use a few key metrics, spaced out over time, tied to tangible goals. Once that clicks, walk through how each contract fits the big picture.
Most people won't remember product names, but they'll remember the strategy: "We have income starting now, more coming later and room to adjust if we need to." That's the story they'll tell their spouse, their kids, or their CPA. And that's how you know the plan made sense for them.
The real value of annuity laddering
Laddering isn't about showing off a product menu. It's about structuring income to match real life — income that starts when needed, grows with flexibility, and gives clients the confidence to adjust, adapt and stay on track. It's a strategy that provides long-term financial security and peace of mind.
When done well, a ladder gives people clear direction, confidence and a path forward. For you, it fosters long-term trust through regular, meaningful client engagement-and strengthens your value as a partner to the client and the insurance company behind the products.
© Entire contents copyright 2025 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Is long-awaited insurance industry transformation arriving — finally?
Most financial advisors compensated using fee-based models
Advisor News
- Ask the right questions to turn clients into raving fans
- The first 5 years of your career could determine the next 50
- Your client’s $3 million portfolio doesn’t tell you their insurance needs
- How life insurance can provide liquidity for wealthy families
- Retirement providers turn to digital engagement to retain assets
More Advisor NewsHealth/Employee Benefits News
Life Insurance News
Property and Casualty News
- GALLEGO CELEBRATES SENATE PASSAGE OF HIS BIPARTISAN BILL TO EXTEND TERRORISM RISK INSURANCE
- Millions who need flood insurance the most don’t have it as flawed federal program raises prices
- AM Best Assigns Credit Ratings to Beibu Gulf Property & Casualty Insurance Company Ltd.
- Cloverleaf Analytics Introduces Autonomous Analytics for P&C Insurers: an AI-Native Solution that Surfaces What's Important and Explains What's Driving It
- SENATE COMMITTEE PASSES TERRORISM RISK INSURANCE PROGRAM REAUTHORIZATION ACT
More Property and Casualty News