

Why Gen X needs a new retirement playbook
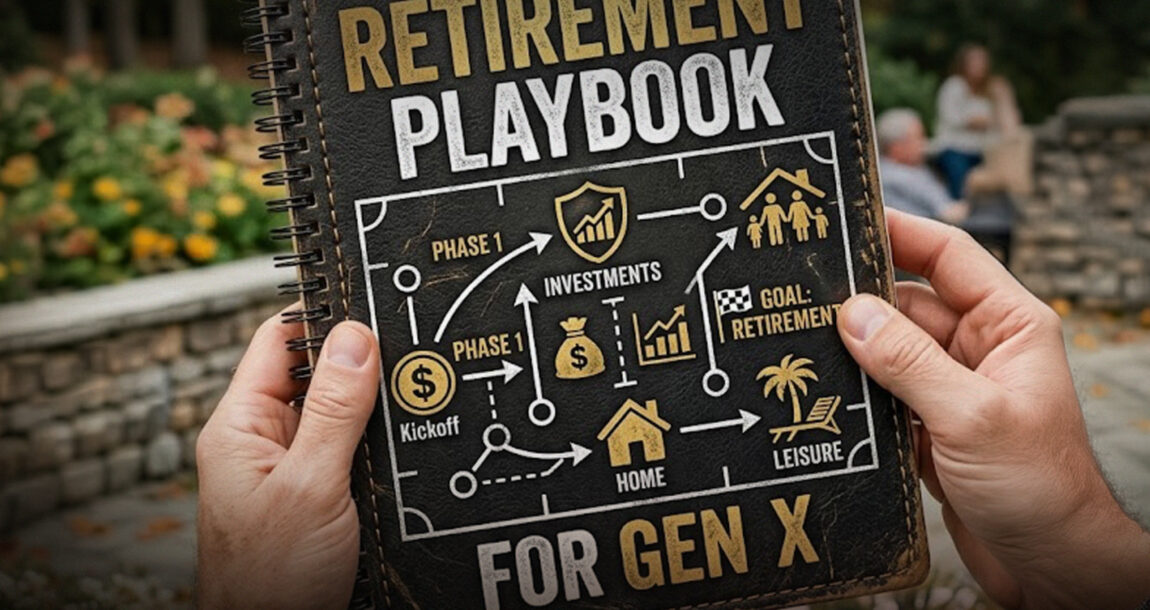
As members of Generation X move closer to retirement, many are discovering that the path their parents followed no longer fits.
For nearly a century, retirement rules were simple. Employers funded pension plans that guaranteed lifetime income. Those funds, along with entitlement programs, allowed Americans to retire with dignity at age 65.
However, that formula no longer works in today’s market. On the private side, the types of accounts available to workers have changed dramatically. While most baby boomers benefited from a guaranteed employer-funded pension, only 14% of Gen Xers, those born between 1965 and 1980, have the same arrangement.
At the same time, the public safety net Americans have long counted on may not be intact much longer. Some 22% of Gen Xers will be at retirement age in 2032, when the primary Social Security trust fund is projected to become insolvent.
Families, companies and policymakers face a similar challenge: ensuring Americans can secure a dignified retirement amid shifting private and government benefits.
Addressing a larger problem
Part of the solution lies in addressing a larger problem. Americans want to build a stronger economic future, but basic financial education still challenges far too many families.
As workers take on greater responsibility for their own financial futures, understanding how to save, invest and plan is essential. Today 42% of American adults still rely on their parents for financial support, more than 60% don’t have a written financial plan, and nearly two-thirds couldn’t pass a basic financial literacy test.
These gaps are costly. On an individual level, Americans lose $1,000 annually on average due to a lack of financial knowledge. Over a lifetime, those missed opportunities translate into tens of thousands of dollars in lost wealth.
Time to avert a crisis
It’s time for American leaders — public and private — to work together to reverse this trend before it becomes a national crisis.
Members of Congress from both sides of the aisle should encourage more Americans to start saving earlier and to build habits that support long-term financial security. That starts with making it easier for individuals and families to save more, plan ahead and access the financial guidance they need to make informed decisions.
In private industry, companies must take a proactive role by educating their employees about existing tax-advantaged plans. For example, 401(k)s allow employers and employees to turn pretax dollars into compounding retirement savings.
These tools work only if employees know how to use them. When employers pair retirement benefits with practical financial education, they give workers the knowledge and confidence to make smarter long-term decisions.
Without a significant change to America’s approach to savings and financial education, Gen Xers and eventually their children will be left behind, unable to retire like their predecessors. We cannot allow Americans to rely on the outdated belief that a pension and Social Security alone will get them across the finish line.
The retirement ecosystem has changed. Our approach to preparing Americans for it must also change. If we fail to adapt to this new reality, millions of hardworking Americans will pay the price.


NAIC adopts AG 55 guidance for reinsurance reserve reporting
AI: What it will and won’t replace
Advisor News
- Wealth planning vs. estate planning: Honoring your client’s wishes
- What to discuss during the first retirement planning meeting
- Inflation, competing priorities and uncertainty erode retirement security
- As health premiums rise, 1 in 8 workers cut retirement savings
- CT governor’s candidates claims: What’s true, and what’s misleading
More Advisor NewsAnnuity News
- National Life Group expands annuity portfolio
- AM Best to Join Life/Annuity Insurance-Focused Panel Discussion at Capitol Forum Event
- USAA Earns No. 1 Ranking in JD Power Individual Annuity Study for the Third Consecutive Year
- How flexible annuities fit today’s retirement portfolios
- Foresters Financial appoints Tom Ross as chief distribution officer for U.S. annuity sales
More Annuity NewsHealth/Employee Benefits News
- Missouri approves 2027 ACA health insurance rate hikes, most in double digits
- How the law protecting Americans from surprise medical bills is driving up healthcare costs
- Medicare Plus supplement vs. Medicare Advantage (Maybe) 2026– Healthful Hints
- ‘Medically frail’ Medicaid enrollees won’t have to prove their inability to work to keep coverage
- IMPLEMENTATION OF IMMIGRANT ELIGIBILITY RESTRICTIONS FOR ACA MARKETPLACE SUBSIDIES UNDER THE 2025 RECONCILIATION LAW: ISSUES TO CONSIDER
More Health/Employee Benefits NewsLife Insurance News
- AM Best Affirms Credit Ratings of Insignia Life S.A. de C.V.
- FINANCIAL FRAUD
- Security Benefit Announces Planned Dividend Rate Reset for Series B Preferred Stock
- Palmetto Heritage and Atlantic Coast Life Announce Discussions Regarding Potential Acquisition
- Jury finds insurance company acted in bad faith, awards Nebraska woman $11.3M
More Life Insurance News