

Why benefits brokers should rethink the LTC conversation
When benefits brokers sit down with clients to discuss workforce challenges, the conversation typically focuses on familiar topics: healthcare costs, talent attraction, retention, mental health and employee engagement.
Rarely does caregiving make the list.
That may be a mistake.
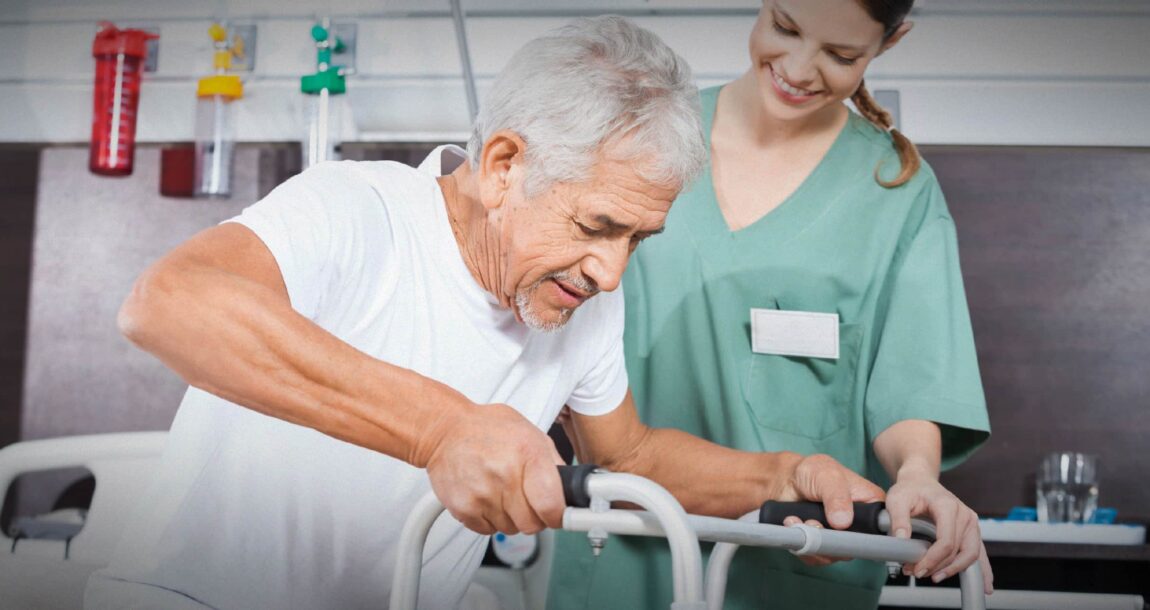
Across the country, millions of employees are quietly balancing full-time jobs while caring for aging parents, spouses, children with special needs and other loved ones. Many are coordinating doctor appointments, researching care options, managing medications, handling financial matters and responding to unexpected crises — all while trying to maintain their performance at work.
For employers, the impact often goes unnoticed until it begins affecting productivity, absenteeism and retention. For benefits advisors, that creates an opportunity.
Caregiving is emerging as one of the most significant workforce issues employers aren’t adequately measuring or addressing. Advisors who can help clients understand the scope of the challenge and identify solutions that support employees both financially and practically can elevate the conversation from benefits administration to workforce strategy.

Caregiving is no longer a niche issue
Many employers still view caregiving as a personal issue affecting a small percentage of employees nearing retirement. The reality is much different.
AARP and the National Alliance for Caregiving report that 63 million American adults provide unpaid care to another adult, yet only a fraction identify themselves as caregivers. At the same time, the Administration for Community Living reports that 70% of Americans turning age 65 will require some form of long-term care during their lifetime. Meanwhile, more than one-third of LTC recipients are younger than 65, according to the Family Care Alliance. This highlights that care needs can emerge much earlier than many employees expect.
Caregiving touches employees across generations. A mid-career manager helping an aging parent navigate Alzheimer’s disease while also caring for their own children at home. A young professional coordinating care for a disabled sibling. An executive balancing work responsibilities while supporting a spouse with a chronic illness. These situations are no longer exceptions. They are becoming increasingly common workforce realities.
The hidden costs employers are absorbing
One of the challenges with caregiving is that its costs rarely appear in a benefits utilization report or financial statement. Instead, they surface in ways that are harder to measure:
» Increased absenteeism
» Lost productivity and workday interruptions
» Burnout and emotional exhaustion
» Delayed career advancement
» Premature workforce exits
Research cited in a recent caregiving analysis found that 1 in 5 employees is actively caregiving at any given time, with caregivers losing an average of $5,600 annually in productivity and 1 in 5 leaving the workforce entirely within three years. Perhaps most striking, nearly one-third of caregivers have voluntarily left a job because of caregiving responsibilities. For employers already struggling to retain experienced talent, that’s a statistic worth paying attention to. Providing a solution will not only be in the employee’s best interest, but it also helps retain employees while keeping them more productive.
Why traditional LTC conversations fall short
For years, LTC planning has centered on future financial protection. While financial protection remains critically important, today’s workforce caregiving challenges reveal a gap in that approach.
Most caregiving journeys don’t begin with an insurance claim. They begin with a phone call.
I experienced this firsthand. A family member’s health condition took her from being fully independent to being unable to care for herself in a very short period. At that moment, I wasn’t asking about benefit payouts. I was trying to figure out what to do next. Who can help? What are the care options? How much will care cost? Who coordinates appointments? How do we manage to figure all of this out while continuing to work?
The need for support begins long before someone enters a care facility or files an LTC claim. Yet many benefit strategies continue to focus exclusively on the financial component of care. And for many, that’s a care need that we all hope is in the distant future. That’s where many employers — and many benefits brokers — have an opportunity to rethink their approach as caregiving presents a more immediate need.
What brokers should discuss with clients
Instead of limiting conversations to LTC insurance products alone, benefits brokers should help clients evaluate their broader caregiving strategy.
A few important questions include:
» How many employees in your workforce are currently caregivers?
» What impact might caregiving be having on productivity and retention?
» What resources exist today to help employees navigate care decisions?
» Are employees educated about LTC risks and planning options?
» Do benefits offerings address both financial protection and practical caregiving needs?
Increasingly, employers are recognizing that employees need more than financial coverage. They also need guidance, education and support. The most effective caregiving strategies tend to include three key elements.
Care navigation and support
Employees frequently need help finding providers, evaluating care options, understanding Medicare and Medicaid, coordinating services and managing family caregiving responsibilities. Access to care coaches and navigation resources can significantly reduce both stress and time away from work.
Education
Employees often underestimate the likelihood, complexity and cost of future care needs. Providing educational resources during enrollments as well as ongoing education can help them make more-informed decisions before a crisis occurs.
Financial protection
LTC and hybrid life and LTC solutions remain an important part of a comprehensive strategy. Financial protection helps employees prepare for potentially significant future care expenses while protecting retirement savings and family assets.
An opportunity for brokers
The best benefits brokers have always done more than sell products. They help clients identify risks, solve workforce challenges and improve employee outcomes. Caregiving is one of the largest workforce challenges many employers have yet to recognize fully.
As the population ages and care costs continue to rise, employers will increasingly look for guidance on how to support employees navigating caregiving responsibilities while remaining productive and engaged at work. Brokers who can help clients connect the dots between caregiving, workforce performance and benefit strategy will be well positioned to lead those conversations.
Caregiving is no longer simply a future retirement issue. It is a workforce issue, and it is already impacting the employees sitting in their offices today


Important year-end financial conversations every advisor must have
A perfect storm demands better planning
Advisor News
- What to discuss during the first retirement planning meeting
- Inflation, competing priorities and uncertainty erode retirement security
- As health premiums rise, 1 in 8 workers cut retirement savings
- CT governor’s candidates claims: What’s true, and what’s misleading
- Retaining clients by giving them a memorable experience
More Advisor NewsAnnuity News
- National Life Group expands annuity portfolio
- AM Best to Join Life/Annuity Insurance-Focused Panel Discussion at Capitol Forum Event
- USAA Earns No. 1 Ranking in JD Power Individual Annuity Study for the Third Consecutive Year
- How flexible annuities fit today’s retirement portfolios
- Foresters Financial appoints Tom Ross as chief distribution officer for U.S. annuity sales
More Annuity NewsHealth/Employee Benefits News
- CONSUMER ADVISORY: OPEN ENROLLMENT STARTS NOV. 1: COMPARE OPTIONS AND FIND OUT HOW TO SAVE
- GOVERNOR SPANBERGER CELEBRATES COURT RULING PROTECTING HEALTHCARE COVERAGE FOR VIRGINIANS WITH SERIOUS ILLNESSES
- Kenai renews employee health coverage despite $792K jump in costs
- Healthcare navigator: More people are dropping insurance or choosing higher-deductible plans
- UnitedHealth Group Incorporated Trademark Application for “HPN” Filed: UnitedHealth Group Incorporated
More Health/Employee Benefits NewsLife Insurance News