

The opportunity in the bottom half of the K-shaped economy
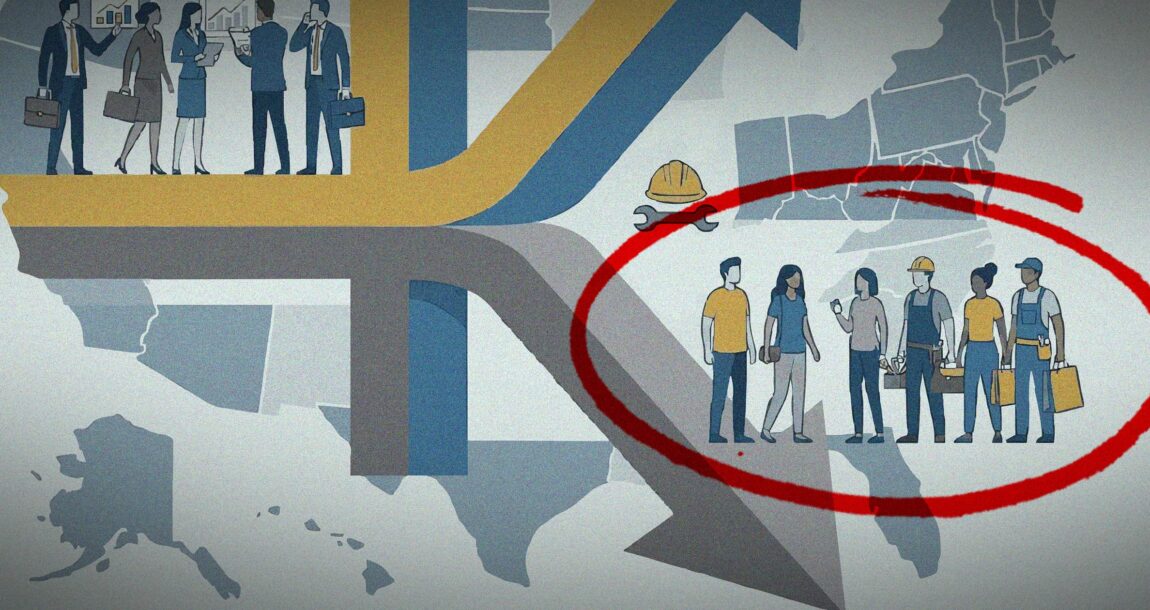
The K-shaped economy narrows in on a reality that life insurers can no longer afford to treat as secondary: Consumers are experiencing the current financial environment in very different ways, and carriers must respond accordingly.
Higher-income households may still evaluate insurance coverage through the lens of income replacement, estate planning and wealth strategy. But families on the lower half of the “K” are trying to figure out what fits into the budget now, and whether the life insurance will still be there when their family needs it. For carriers serving the middle market, or those in the $50,000 to $150,000 annual income range, this distinction should shape product strategy, distribution planning and customer engagement.
The issue becomes affordability under pressure. Inflation, elevated living costs and ongoing budget strain have made it more difficult for families to focus on protection because they’re so focused on today's expenses. This is a call to the industry to design simpler, more flexible products, remove unnecessary friction from the buying process and build trust with consumers who are making every financial decision more carefully. Industry leaders should recognize that growth in this segment will come only from understanding how families purchase the products, not from applying traditional assumptions more aggressively.
One of the clearest takeaways for life insurance leaders is that many consumers are looking for a sustainable amount of coverage, not the perfect amount the models tell them to buy. Traditional planning models usually focus on income, debt, mortgage balances or future education costs. For households under financial strain, those calculations can quickly produce premiums that feel unrealistic. It’s the difference between recommending a plan that lasts and recommending one that lapses when it’s too expensive.
If consumers are encouraged to buy more coverage than their budgets can support, the policy may lapse, the family remains vulnerable and the insurer loses credibility. For life insurance leaders, the implication is clear: Lower face-amount products should not be treated as a compromise offering, but as an essential part of a durable protection strategy. A policy with staying power delivers more value than one that is never purchased or cannot be maintained.
Accessibility is equally important and shouldn’t be separated from affordability. Simplified products, automated underwriting and instant decisioning make it easier for consumers who may already believe life insurance is too complex or out of reach. If the experience feels slow, confusing or invasive, many consumers – especially budget-conscious ones - will walk away. Leaders should prioritize purchase journeys that are easier to understand, faster to complete and designed for follow-through.

Aiming for the middle market
Distribution strategy also must evolve. Business-to-business partnerships and public-facing platforms can help carriers reach consumers looking for smaller coverage amounts and simpler purchase paths. Many traditional carriers still do not offer products that fit this segment well or make them easy to find. Leaders should view this as a market access issue as much as a marketing issue: products built for the middle market need to be present in the channels where these consumers already make financial decisions.
Transparency plays a tremendous role as well. When budgets are tight, consumers are sensitive to anything that feels complicated or misaligned with their interests. Selling based on budget, rather than coverage amount, is a trust strategy and helps in the long term. Leaders should make clear what a policy can and cannot do, position smaller policies honestly and train teams to focus on fit and retention rather than maximum face value. At these coverage levels, small policies can prevent a family from turning to crowdfunding for funeral costs, help cover immediate expenses and create breathing room after a loss.
Trust is ultimately tested at claim time. A claims experience built around speed, automation and compassion is important for financially strained households. Fast access to funds may determine whether a family can manage funeral arrangements, cover urgent expenses or avoid deeper financial distress. In a bifurcated economy, carriers will earn trust and grow relevance by making protection reachable, understandable and dependable when it matters most.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Turning 26 creates health care challenges for Americans
Living longer, retiring poorer: Why fragmented systems are failing Americans
Advisor News
- SEC settlement would require Tai Lopez, two others, to pay $6.8 million
- The Gen Z money paradox
- NAIFA applauds final SECURE 2.0 regulations
- What will Democrats in Congress do about healthcare and retirement?
- Election results cloud retirement legislation outlook, experts say
More Advisor NewsAnnuity News
- Best’s Market Segment Report: AM Best Maintains Stable Outlook on US Life/Annuity Insurance Segment
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- Boomers want retirement protection, but their actions don’t match their mindset
- NAIC task force to address LTC riders
- ‘It’s really shocking:’ Regulators scrutinize assets backing annuity sellers
More Annuity NewsHealth/Employee Benefits News
- Samantha Wildow: Mercy Health warns thousands of Medical Mutual of Ohio patients may go out-of-network in 2027
- Hooksett, Auburn, Candia, Londonderry schools face steep SchoolCare health insurance hikes
- 'Everybody missed this': Nevada's state worker insurance mismanaged for years, officials say
- Picking Medicare insurance plan is daunting task – Healthful Hints
- November Issue of Best’s Review Ranks US Life Reinsurers and More
More Health/Employee Benefits NewsProperty and Casualty News
- November Issue of Best’s Review Ranks US Life Reinsurers and More
- Capacity Marine Appoints Damon Vaughan President
- What an airspace shutdown tells us about risk
- American Family Insurance announces nearly $700 million policyholder member dividend
- Talking Central Florida: Investigating Florida’s property insurance industry
More Property and Casualty News