

Future proofing insurance companies for the next shock
Insurance investors suffered a perfect storm as they emerged from the pandemic, and had to contend with persistent inflation, investment losses and a hardening reinsurance market.
Now that we are further along in the cycle, it may be the ideal time for insurers to revisit their enterprise risk management programs and investment strategy, to ensure they are prepared for the next shock.
Reflecting on a perfect storm
Last year, inflation disrupted insurance companies on two fronts. First, rising rates caused bonds and equities to fall together for the first calendar year in almost five decades. Second, inflation eroded premiums in real terms and increased claims severity trends.
Inflation was not the only issue. Fitch estimated that 2022 was the third costliest year ever for weather-related events for insurers and reinsurers. Insurance companies had less capital available to write new business, further pushing up reinsurance costs.
The property/casualty industry has used, on average, 10% of direct premiums to buy reinsurance coverage over the last four years, S&P reported, so smaller insurers have likely exceeded that level.
Insurance companies needed to write more premiums, retaining more risk as reinsurance costs rose


Future-proofing for further storms
Insurance companies can now look more closely at the data from 2022 to test the effectiveness of their enterprise risk management programs and update their Risk Appetite Statement.
This may be particularly helpful because uncertainty and market volatility are not going away. The news cycle persists with rate and equity market volatility, as well as rising geopolitical risks leading to higher disaster probabilities and downside risk. Weather-related uncertainty will also continue. A re-evaluation of core ERM processes should be on every insurer’s agenda.
We offer three potential starting points for insurers.
The first is to work in collaboration with their investment managers and consider aligning their underwriting pricing assumptions with their capital market assumptions. This can help establish strategic investment guidelines to reduce volatility in net income and ultimately lower volatility in statutory surplus.
The second is retroactively test the effectiveness of their current ERM policies, revisit risk tolerance limits for all major risks and reinforce the need to implement a holistic approach to modeling surplus risk.
Finally, it may be worth considering how liquidity events (such as the banking sector stress from earlier this year) can expose liquidity risk and as a result, the need for diversification and awareness of where liquidity is held.
Should insurance companies consider investment and underwriting policy together?
Modeling underwriting results and investment results together is common practice in capital modeling for insurance companies.
We have worked with insurance companies that have strategically aligned total return assumptions with underwriting pricing assumptions to establish target volatility limits for investment income and underwriting income, as part of their annual capital modeling and portfolio optimization exercise.
We also believe the dominance of investment income on property/casualty insurers’ income statements presents an opportunity for insurers to leverage capital modeling to better understand downside risk to surplus relating to underwriting risk, reserve risk, liquidity risk and investment risk.
Investment income has dominated P/C historical net income results


Below is a visual representation of the impact of reinsurance coverage on income distribution.
Impact of lower reinsurance coverage on downside risk to surplus
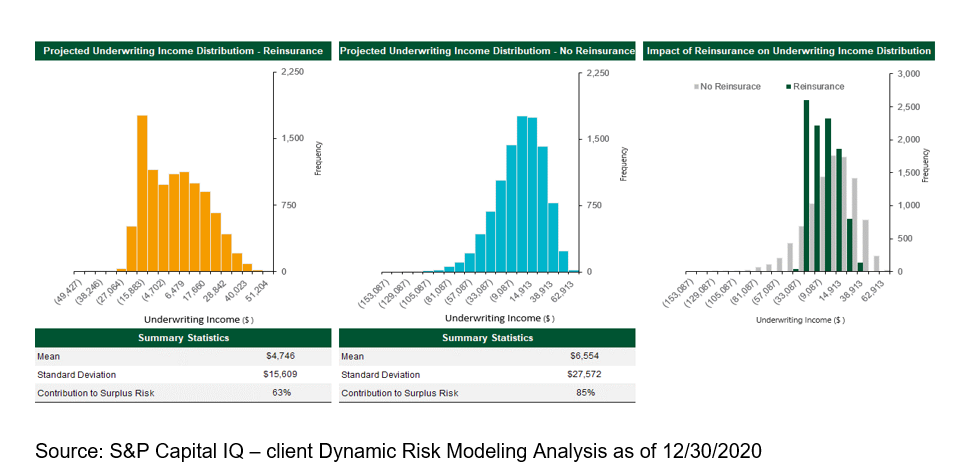
We believe the extreme range in outcomes provides further support for implementing a more holistic approach to insurance underwriting risk and investment policy objectives. An integrated approach can increase the certainty of the desired outcome being achieved.
Taking a holistic approach does require sophisticated dynamic financial analysis (which includes capital modeling, stress testing, strategic asset allocation and forecasting downside risk to statutory surplus or net position). Insurance companies may wish to partner with managers that specialize in insurance asset management and have the requisite skills and experience to obtain a second opinion on their capital modeling and portfolio optimization.
Kerry O’Brien is head of insurance portfolio management, Insight Investment. Contact her at kerry.obrien@innfeedback.com.
© Entire contents copyright 2023 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


‘Excess mortality’ continuing surge causes concerns
MassMutual embraces behavioral insurance with new program
Advisor News
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- WA CHALLENGES FEDERAL MEDICAID BARRIERS JEOPARDIZING WASHINGTONIANS' HEALTH COVERAGE
- AG RAYFIELD CHALLENGES TRUMP ADMINISTRATION PLANS TO KICK OREGONIANS OFF THE OREGON HEALTH PLAN
- Where the human-AI workflow in health care breaks down
- Enrollment open for health insurance marketplace
- Palatine Proposes Flat Levy, 8.5% Water Rate Hike In 2027 Budget
More Health/Employee Benefits NewsLife Insurance News
- Milliman’s proposed $15.5 million settlement puts life insurance underwriting data in focus
- Brighthouse Financial Announces Third Quarter 2026 Results
- Prudential earnings dip as Japan sales suspension offsets U.S. growth
- U-Haul Holding Company Reports Second Quarter Fiscal 2027 Financial Results
- Genworth Financial Announces Third Quarter 2026 Results
More Life Insurance News