

Education, delivery methods are keys to self-directed retirement planning
If Americans are to successfully master the transition to self-directed retirement planning, it is going to take a lot of education.
Financial education is one part, the vehicle to provide it is yet another piece of the puzzle, said Bryan Hodgens, corporate vice president, distribution and annuities, member benefits, LIMRA and LOMA.
Hodgens is moderating a pair of sessions today at the 2023 LIMRA Annual Conference: Forging the Future, at National Harbor outside Washington, D.C. Both sessions tackle retirement planning and how to best connect Americans with better strategies.
The need for financial advice is acute at the moment, with the transition from defined benefit to defined contribution plans nearly complete. In addition, rising interest rates, schizophrenic equity markets and rampant talk of recession has many retirees and near-retirees lacking confidence.
"There's a lot of trends now today around more of a flexible spending dynamic in terms of retirement income planning, which means you're making adjustments each year based on market conditions, inflation," Hodgens explained. "Spend more, spend less, but make adjustments versus having a static withdrawal."

Studies show underlying issues
LIMRA conducts regulars studies digging into the stubborn resistance to certain retirement products and overall holistic planning. The reasons are obvious and well known: people put off retirement and mortality discussions, and they don't know enough about annuities to trust the products.
Its most-recent study, titled "The Evolving Retirement Landscape: the Consumer View" returned some interesting answers to questions such as, "I am confident that I will be able to live the retirement lifestyle I want.”
"These consumers have a household investable assets of at least $100,000 or more," Hodgens said. "So it is not pulling in everybody."
The survey found a historically low 20% "strongly agreed" with that statement, but another 49% "somewhat agreed." Together, 69% is at the high end of a decade-long trend line, and it shows that the industry has a confident and enthusiastic majority of Americans seeking financial help.

The answer to boost Americans' retirement comfort level might be found at the office, Hodgens said. Much like employers provide health care insurance options for millions of Americans, financial education and planning could start at work as well.
"We'll talk about how another trend that's occurring is holistic financial wellness that's occurring in the workplace," Hodgens explained. "We think that trend is going to continue and grow exponentially, because what we're seeing is employees are asking employers, 'Help me with my overall holistic financial planning while I'm in the workforce [and] working at your company.'"
Guaranteed income needed
Several LIMRA sessions will touch on guaranteed lifetime income, usually annuities, and how to better position these product promises that surveys show repeatedly that Americans hold in high regard.
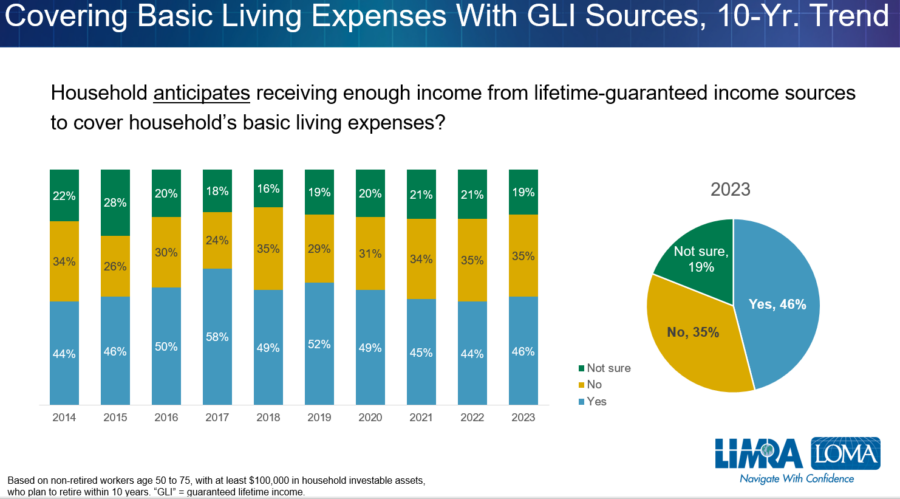
The LIMRA survey of consumers revealed a growing percentage of Americans who do not believe they will be able to cover "basic living expenses" with guaranteed living income sources, or income to supplement Social Security.
The Setting Every Community Up for Retirement Enhancement (SECURE) Act of 2019 and the followup Secure Act 2.0, signed into law in December, cleared the way for employer plans to offer annuity options -- among other things. SECURE 2.0 contains 92 new or modified provisions addressing retirement.
As a result, LIMRA researchers expect employers to embrace the idea of offering annuities inside plans.
"They have this view that they need to take care of their employees with a guaranteed income lifetime guaranteed income like the pension was," Hodgens said. "So, they're very interested in adding these guaranteed lifetime or annuity products to the to the workplace benefit plan."
InsuranceNewsNet Senior Editor John Hilton covered business and other beats in more than 20 years of daily journalism. John may be reached at john.hilton@innfeedback.com. Follow him on Twitter @INNJohnH.
© Entire contents copyright 2023 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.

Advisor News
- After the midterms: Addressing your clients’ tax concerns
- Berkeley arts tax heads toward passage while public bank measure looks likely to fail
- Americans’ sense of overall prosperity still ticks upward
- Turning expanded eligibility into a better coverage plan for federal clients
- Election 2026: Which of Berkeley's 7 ballot measures will pass?
More Advisor NewsAnnuity News
- AM Best Affirms Credit Ratings of Knighthead Annuity & Life Assurance Company and Merit Life Insurance Co.
- Jackson reports record annuity sales, increases share repurchase authorization
- Why the market doesn’t need more carriers
- Equitable, Corebridge steam toward merger with strong Q3 annuity sales
- Jackson Announces New Annuity Offering for AARP Members
More Annuity NewsHealth/Employee Benefits News
- Boeing retirees ‘shocked’ by 400% jump in health insurance premiums
- MEDICAID PAYMENT TRANSPARENCY RULES: STATE REPORTING REQUIREMENTS AND LIMITATIONS
- Medicare open enrollment continues through Dec. 7
- Pike County facing year-end employee healthcare lapse
- Investigators at University of Pennsylvania Report New Data on Managed Care (In-hospital Medicaid enrollment facilitates follow-up care for emergency general surgery patients): Managed Care
More Health/Employee Benefits NewsLife Insurance News
- AM Best Affirms Credit Ratings of Central States Indemnity Co. of Omaha and Its Subsidiary
- National Life Group Approves $23 Million Dividends for 2027
- Milliman’s proposed $15.5 million settlement puts life insurance underwriting data in focus
- Brighthouse Financial Announces Third Quarter 2026 Results
- Prudential earnings dip as Japan sales suspension offsets U.S. growth
More Life Insurance News