

New LTC solutions fill a critical gap for clients
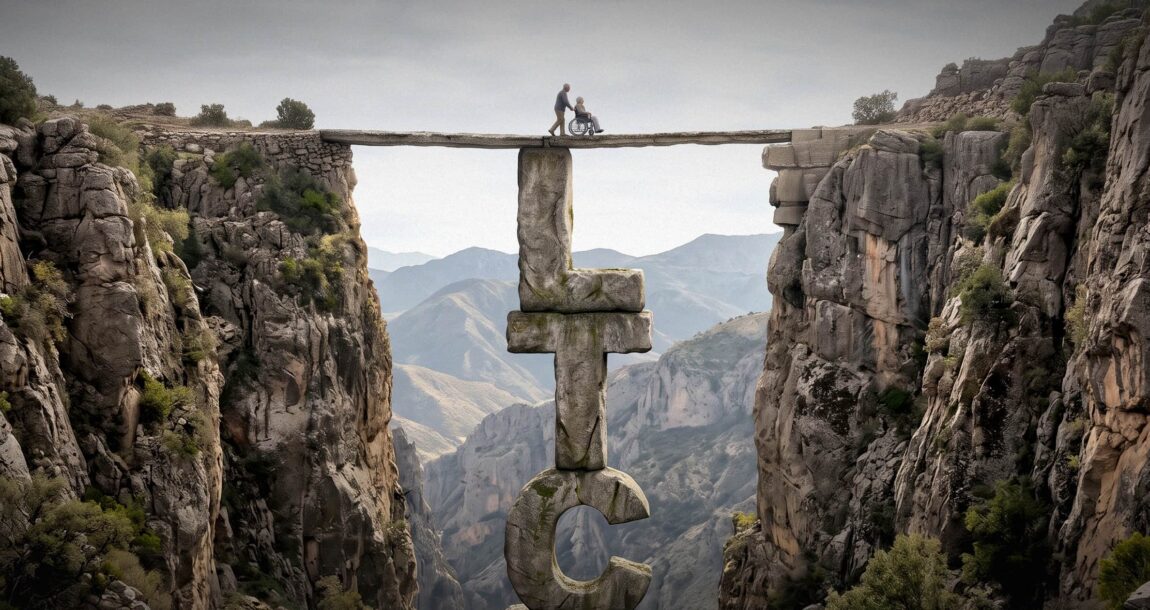
Long-Term Care Awareness Month is a useful reminder of a planning reality that too often remains unaddressed: Most Americans do not have meaningful protection against the cost of long-term care, and many have never discussed the risk with a financial professional.
That should concern all of us in the financial services business. It represents a major protection gap for clients and their families. It also represents an opportunity for advisors to lean into the value of holistic planning by helping clients prepare for a risk that can have a significant impact on retirement income, legacy planning and the responsibilities of future caregivers.
The numbers make the need for a conversation clear. LIMRA estimates that only 3% to 4% of Americans age 50 and older have long-term care protection. Nationwide Retirement Institute research shows that just 18% of consumers have discussed long-term care costs with a financial professional. Meanwhile, 49% say it is important for a financial professional to discuss those costs with them, and 63% of people who have not had the conversation say they plan to do so.
In other words, consumers are not necessarily rejecting the conversation. In many cases, they are waiting for someone to start it.
The advisor’s role is changing
Advisors have long been expected to help clients plan for market volatility, longevity, healthcare expenses and income needs in retirement. Long-term care belongs in that same conversation. Yet it is often left out because it feels difficult to explain, uncomfortable to raise or disconnected from the rest of a client’s financial plan.
Some advisors may also be working from outdated assumptions about today's available solutions. The long-term care marketplace has evolved a lot over the past decade, most notably through the growth of hybrid life insurance and annuity products with linked benefits. According to LIMRA, sales of linked-benefit long-term care products grew 30% year over year.

That momentum reflects a broader shift in how clients and advisors can think about addressing this challenge. A long-term care solution does not have to be viewed only as a stand-alone expense or as coverage that may never be used. Depending on the product, a hybrid policy can provide long-term care benefits if needed and a death benefit for beneficiaries if they are not. A wide variety of new linked-benefit products have entered the market in recent years. This newer generation of solutions give clients more flexibility in how they address an uncertain future need.
The right solution will not be the same for every client. However, the solution set is broader and more flexible than many advisors realize. That makes it critically important for advisors to understand the solutions available to drive meaningful conversations with clients.
Reframing common objections
A first step is recognizing the concerns that can keep advisors from bringing up long-term care in the first place.
One common perception is that a client will “use it or lose it.” Hybrid policies can challenge that assumption by offering a death benefit for loved ones when long-term care benefits are not needed.
Another concern is affordability. Longer payment periods, joint-policy designs and a wider range of products can give advisors more ways to structure a solution around a client’s circumstances.
Clients may also worry that premiums could increase unexpectedly or that purchasing coverage will tie up money they might need for another purpose. Some hybrid solutions offer guaranteed premiums and provide access to cash value for needs beyond long-term care. These features do not eliminate the need for careful analysis, but they can make the conversation more nuanced than a simple choice between buying coverage and self-funding.
Qualification and benefit restrictions are additional areas where product design matters. Annuity-based hybrid options may be easier for some clients to qualify for, while indemnity benefits can provide greater flexibility in how benefits are used than reimbursement designs. Advisors should understand the distinctions and explain them in plain language, with support from specialists when appropriate.
The goal is not to minimize the complexity of long-term care planning. It is to make that complexity more accessible and manageable for the client. Many providers offer a dedicated sales team to help advisors compare designs, understand the trade-offs, and tailor recommendations to a client’s goals.
A conversation with a broader purpose
Long-term care planning is about more than a policy. It is about helping clients maximize their options before a health event forces them to make big decisions under pressure.
According to research from the Nationwide Retirement Institute, clients who work with advisors are more likely to say they understand long-term care, identify potential caregivers, and discuss care costs with family members. Those conversations can help families clarify who may provide care, how expenses could be funded and how a retirement plan might respond if care is needed for an extended period.
The need is becoming more visible as the Peak 65 generation moves through retirement and the sandwich generation struggles to help parents navigate aging while managing their own financial obligations. For many families, the question is no longer whether long-term care could affect them. It is whether they have a plan for what happens if it does.
Long-Term Care Awareness Month gives advisors a timely reason to boost their knowledge of today’s long-term care solutions so they can start engaging their clients. The conversation does not need to start with a product recommendation. It can begin with a question: What would happen to your retirement plan, your family or your legacy if you needed care for an extended period?
From there, advisors can listen, identify the gaps and evaluate the full range of strategies available. That approach can turn an uncomfortable subject into a practical planning discussion — and help more Americans move from uncertainty to preparedness.
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Survery: Most Americans still feel prosperous despite economic worries
Advisor News
- Survery: Most Americans still feel prosperous despite economic worries
- SEC settlement would require Tai Lopez, two others, to pay $6.8 million
- The Gen Z money paradox
- NAIFA applauds final SECURE 2.0 regulations
- What will Democrats in Congress do about healthcare and retirement?
More Advisor NewsAnnuity News
- Best’s Market Segment Report: AM Best Maintains Stable Outlook on US Life/Annuity Insurance Segment
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- Boomers want retirement protection, but their actions don’t match their mindset
- NAIC task force to address LTC riders
- ‘It’s really shocking:’ Regulators scrutinize assets backing annuity sellers
More Annuity NewsLife Insurance News
- November Issue of Best’s Review Ranks US Life Reinsurers and More
- Nebraska widow’s big win against life insurer in legal limbo
- New York Life Announces Record $3.1 Billion in Policy Owner Dividends for 2027
- AM Best Affirms Credit Ratings of Massachusetts Mutual Life Insurance Company and Its Subsidiaries
- U-Haul Holding Company to Participate in Deutsche Bank Conference
More Life Insurance NewsProperty and Casualty News
- November Issue of Best’s Review Ranks US Life Reinsurers and More
- Capacity Marine Appoints Damon Vaughan President
- What an airspace shutdown tells us about risk
- American Family Insurance announces nearly $700 million policyholder member dividend
- Talking Central Florida: Investigating Florida’s property insurance industry
More Property and Casualty News