

Making insurance easy has never been harder
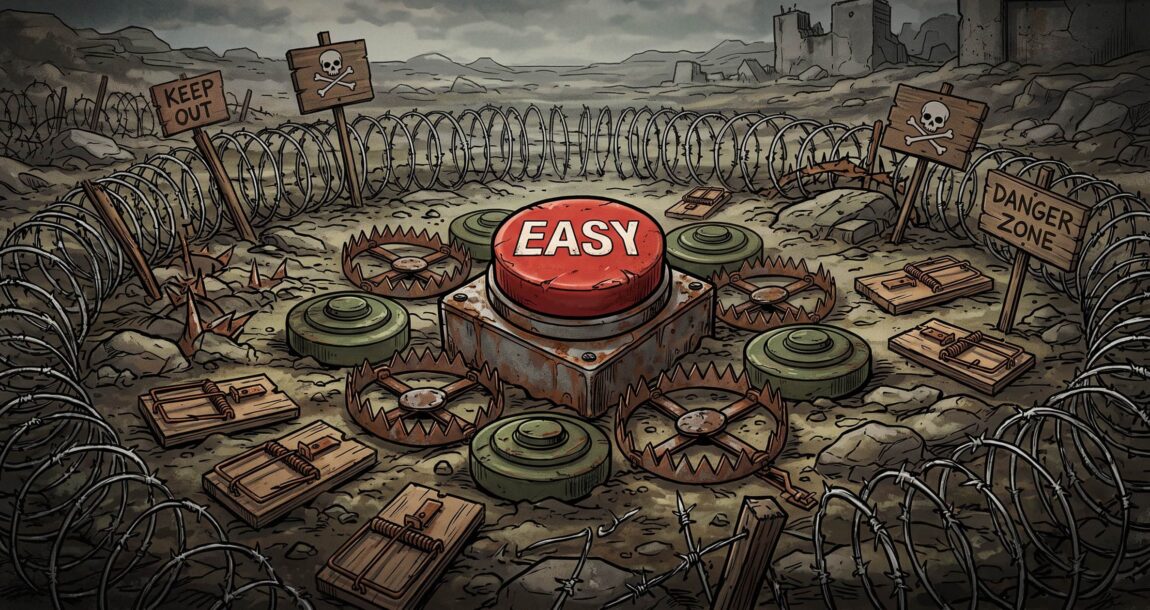
I can order almost anything in the world and know when it was ordered, when it shipped, where it is and exactly when it will arrive. I can get blood drawn in the morning and see the test results on my phone before lunch.
Ask me when an endorsement request will be processed, though, and sometimes my best answer is, "Hopefully soon." Somehow, I can track a $14 sandwich to within 25 feet, but neither I nor my client can see where an endorsement is in a carrier's workflow.
The insurance industry talks constantly about technology, automation, artificial intelligence and making it easier to do business. To be fair, we've made tremendous technological advances. Carriers have access to more data, better analytics, satellite imagery, predictive modeling and increasingly sophisticated underwriting tools.
Insurance isn't technologically primitive. Its technological sophistication is disproportionately concentrated in areas that benefit risk selection and internal operations rather than the customer experience.
Information still doesn't flow easily between insureds, agencies and carriers. Many carrier systems don't communicate easily with agency systems, and application programming interfaces are not readily available. Information submitted once often must be submitted again. Status updates require emails and phone calls. Clients have very little visibility into what's happening behind the scenes.
At the same time, the insurance process itself is becoming more complicated. Supplemental applications get longer, underwriting questions become more detailed, inspections become more frequent, and documentation requirements continue to grow.
There are legitimate reasons for that. Property losses and replacement costs have increased dramatically, reinsurance has become more expensive, businesses are changing faster than ever, and staffing remains a challenge across the industry. Good underwriting protects everyone. This isn't an argument for less underwriting. It's an argument against unnecessary friction.
Digitizing but not redesigning
Insurance has digitized many processes without actually redesigning the experience. Paper applications became PDFs. Mail became email. Manual rating became carrier portals. Physical files became agency management systems. That's progress, but the underlying process often looks remarkably familiar.
The insured provides information. The agency submits it. Underwriting asks more questions. We go back to the insured. We submit the answers. We wait. An inspection is ordered. We wait again. The client asks for an update, so the agency asks the carrier for an update.
We've digitized the steps without necessarily eliminating the friction between them.
There is evidence that clients notice. J.D. Power's 2025 U.S. Claims Digital Experience Study found that adequate digital status updates were one of the top drivers of customer satisfaction, yet insurers delivered on that measure only 22% of the time.
If I submit an endorsement request, why can't my client see that it was received, assigned, reviewed and completed? Why can't they receive automated updates as their renewal moves through the process? This doesn't require some revolutionary application of AI. FedEx figured out package tracking decades ago.
Why is this considered aspirational in insurance when consumers have considered it baseline functionality everywhere else for years?
Problems with information
There is a similar problem with the information itself. Every agency has experienced a renewal where a carrier asks for the same underwriting information submitted the year before, even though nothing material has changed. The carrier already insures the building. The roof is the same roof. The electrical system that was brand new five years ago is still the same electrical system. Yet everyone starts over.
Insurance is incredibly good at collecting data. We're much less effective at retaining and using what we've already collected.
If quality underwriting information is already available and nothing material has changed, we shouldn't rebuild the file from scratch every year. Ask new questions when they're necessary and update information that may have changed, but don't repeat old questions simply because they're on a checklist.
This isn't only a carrier problem. Staff turnover and inconsistent processes inside agencies mean valuable information gets lost too. Sometimes an account has "auto-renewed" for years and no one has taken a fresh look at what the insured actually does.
Agencies also have an important role in deciding how much complexity actually reaches the client. If an underwriter sends 15 questions, a knowledgeable commercial agent shouldn't automatically forward all 15. Maybe we already know the answers to seven. Maybe another three can be answered through assessor records, building permits, multilist service listings, satellite imagery, prior inspections or information already sitting in our management system.
That leaves five questions that actually require the client's input instead of 15. That's part of the value of a knowledgeable insurance professional. Our job is to understand the risk, use the information already available to us, and absorb as much of the complexity as possible before passing work along to the client.
There is also a reason some of this inefficiency persists: the person creating the friction often isn't the person dealing with its consequences. Another supplemental application means work for the agency and insured. Another round of underwriting questions means more work for the agency and insured. No automated carrier status means the client calls the agency, the agency calls the carrier, and everyone waits.
The cost of inefficient processes gets pushed downstream, ultimately landing with the insured.
Measuring could be the answer
Maybe friction itself needs to become a metric.
We measure almost everything in insurance. Carriers measure loss ratios, quote ratios, retention and turnaround time. Agencies measure retention, new business, revenue and productivity. What we rarely measure is how difficult we made the transaction for the client.
How many times did we ask them for information? How much of it did we already have? How long did they go without an update? How many emails, forms, portals and follow-ups did it take to get from renewal review to bound coverage?
If we actually measured those things, we might start designing our processes differently. Maybe we'd stop asking for information we already have. Maybe we'd prioritize connectivity over another portal or dashboard. Maybe agencies would spend more time maintaining good underwriting information instead of recreating it every year.
Commercial insurance isn't going to become simple. The goal should be to make that complexity easier to navigate and pay more attention to the cost of the process itself.
The next time a client asks me when their endorsement will be processed or when they can expect their renewal quote, I'd like to give them a better answer than, "Hopefully soon."
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


Ask the right questions to turn clients into raving fans
What happens to insurance planning when a client retires early?
Advisor News
- What happens to insurance planning when a client retires early?
- Ask the right questions to turn clients into raving fans
- The first 5 years of your career could determine the next 50
- Your client’s $3 million portfolio doesn’t tell you their insurance needs
- How life insurance can provide liquidity for wealthy families
More Advisor NewsAnnuity News
- What lower interest rates mean to annuity payouts
- AM Best downgrades A-Cap insurers amid financial and regulatory troubles
- Lawsuit claims Delaware Life hid billions in insurer-linked investments
- AM Best to Deliver Presentation at 2026 ACLI Annual Conference
- Global Atlantic Announces Launch of ForeLifetime Income, a New Fixed Index Annuity
More Annuity NewsHealth/Employee Benefits News
Life Insurance News