

Addressing the longevity paradox
In September, AgeTech Connect hosted its annual summit at the Buck Institute for Research on Aging in San Francisco. This was a gathering of hundreds of scientists, academics, financial advisors and care providers, as well as founders and funders, all dedicated to increasing human longevity and extending quality of life.
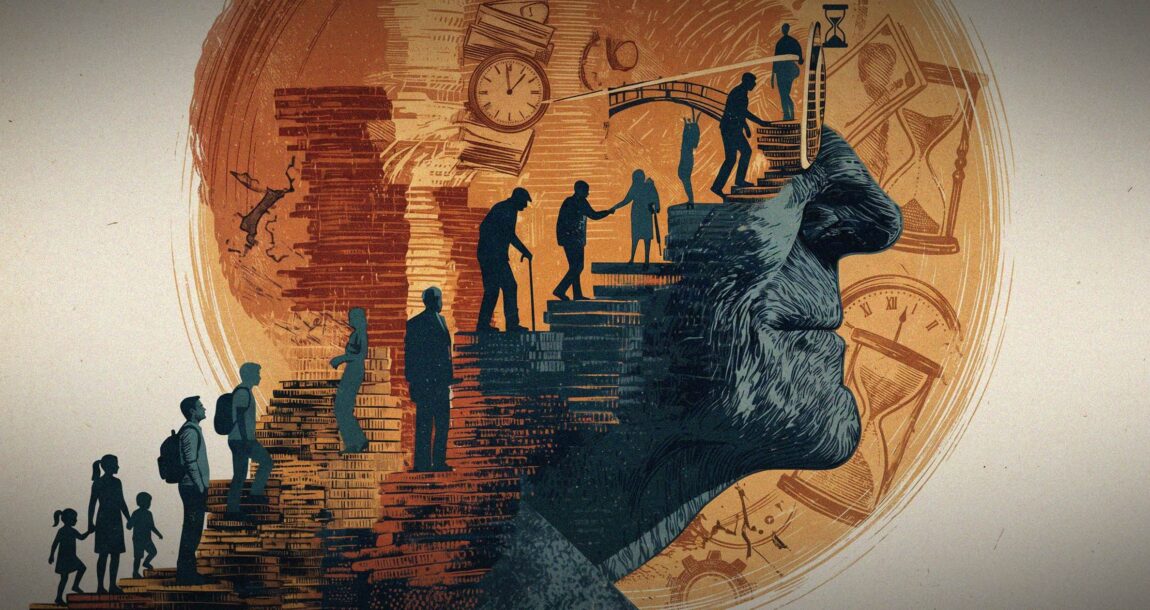
Much of the focus on longevity to age 100+ has been on the scientific and biological factors of aging. But without addressing the financial realities of aging and declining health, the positive experiences of healthspan and wealthspan across a lifespan could become attainable only to a small, elite percentage of the population, and out of reach for the remaining majority.
In my remarks to the gathered body of this summit, I pointed out that over the last three decades of working on both the political and financial services sides of aging and financial security, there has been an unresolved paradox that has exacerbated the growing financial crisis: The money side doesn't want to talk about the realities of care and the care side doesn't want to talk about the realities of money.
The disconnect in longevity planning
This disconnect plays out every day: 85% of people don't think they'll need long-term care, but 70% of people over 65 will need formal extended care support and services. Aging and the eventual need for care are expensive and can quickly wipe out people's retirement savings. Higher net worth individuals can self-insure, and the disadvantaged can turn to Medicaid. But the middle majority are stuck in the middle. They can’t afford to pay out of pocket month after month, and they can’t access Medicaid without undergoing a spenddown process taking them to below the poverty line.
People must understand the role entitlement programs play in creating financial security. Medicaid is means-based and the payor of last resort, but it has become the default payor of skilled long-term care in the United States. Medicare is age-based and won't cover extended care, but about half of Americans think it does. And the foundation for most, Social Security, is facing bankruptcy in less than 10 years.
The One Big Beautiful Bill cut $1 trillion from Medicaid, eliminated Affordable Care Act subsidies, reduced SNAP benefits, and cut $500 billion from Medicare. About 3 million people have dropped from ACA coverage, reducing total enrollment to roughly 19 million people. In fact, today is the best day for government entitlement programs for the rest of our lives.

This is why advisors, care providers and individuals must focus on access to financial resources designed to address the expensive costs of extended care with the “Big 5 Private Pay” options:
- Long-term care insurance. About 7 million long-term care insurance policies are in force in the U.S.
- About $3 trillion of in-force annuity premium is in force in the U.S.
- Life settlements. About 267 million life insurance policies are in force in the U.S.
- Reverse mortgage. About $9.65 billion in loans have been transacted.
- VA Aid & Attendance benefit. About 8.2 million veterans age 65 and above are eligible for this.
The sooner people prepare, the better their results will be with long-term care insurance and annuities. But options such as life settlements, reverse mortgages and the VA benefit kick in once you are aging or in declining health. Yet families don't want to talk about the possibility of extended care, and it's a can they can easily kick down the road.
Most families deal with it too late
Most families end up confronting this reality only when it's too late and a loved one is in a hospital with about 48 hours left until they are discharged to a skilled rehabilitation facility and care providers are asking them what resources they have in place. For most Americans, this is when they first confront the realities of navigating the “Long-Term Care Industrial Complex.”
Everyone would prefer to age in place, but that's expensive and out of reach for most people. So are assisted living, memory care and skilled nursing care. Care providers, advisors and longevity innovators must get their arms around the financial realities of both government and private funding sources needed to achieve financial security out to age 100.
We must fix the disconnect between financial advisors and care providers. We must stop ignoring the flip side of the coin between care and costs because the solution requires people to be well informed and have access to all available resources. To benefit from longevity breakthroughs, we must address financial realities and make financial tools accessible to everyone, because what good is living to 100 if you're broke and miserable?
© Entire contents copyright 2026 by InsuranceNewsNet.com Inc. All rights reserved. No part of this article may be reprinted without the expressed written consent from InsuranceNewsNet.com.


HAFA filing suit over ACA agent moratorium
What’s behind the growth of CHOICE arrangements?
Advisor News
- Addressing the longevity paradox
- Employers shift focus from retirement access to financial outcomes
- Helping widowed clients navigate their new financial reality
- Navigating client communication in a digital age
- Can your advisory firm survive without you?
More Advisor NewsAnnuity News
- Farm Bureau P&C insurers post first underwriting gain since 2021
- Legacy Marketing, Malibu Life launch two fixed indexed annuities
- Changing client priorities are reshaping annuity conversations
- Solen Software acquires annuity software provider Cooperative Technologies
- MassMutual Expands Lending Options With New Secured Credit Line
More Annuity NewsLife Insurance News
Property and Casualty News
- Editorial: FEMA flap
- New FEMA digital tool help residents purchase flood insurance
- Same driver, same car: Why auto insurance quotes can differ by nearly $5,000 a year
- Who Pays When a Delivery Driver Hits a Pedestrian While on the Job?
- New FEMA digital tools helps residents purchase flood insurance
More Property and Casualty News